



 Chat with AI
Exam 4: Corporations: Organization and Capital Structure

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


In order to retain the services of Bonnie, a key employee in Ralph's sole proprietorship, Ralph contracts with Bonnie to make her a 25% owner. Ralph incorporates the business receiving in return 100% of the stock. Three days later, Ralph transfers 25% of the stock to Bonnie. Under these circumstances, § 351 will not apply to the incorporation of Ralph's business.
(True/False)
4.9/5  (72)
(72) If a corporation is thinly capitalized, all debt is reclassified as equity.
(True/False)
4.8/5 (74)
(74) A shareholder lends money to his corporation in his capacity as an investor. If the loans become worthless, a business bad debt results.
(True/False)
4.7/5 (93)
(93) Tara incorporates her sole proprietorship, transferring it to newly formed Black Corporation. The assets transferred have an adjusted basis of $240,000 and a fair market value of $300,000. Also transferred was $10,000 in liabilities, $1,000 of which was personal and the balance of $9,000 being business related. In return for these transfers, Tara receives all of the stock in Black Corporation.
(Multiple Choice)
4.9/5 (72)
(72) Joe and Kay form Gull Corporation. Joe transfers cash of $250,000 for 200 shares in Gull Corporation. Kay transfers property with a basis of $50,000 and fair market value of $240,000. She agrees to accept 200 shares in Gull Corporation for the property and for providing bookkeeping services to the corporation in its first year of operation. The value of Kay's services is $10,000. With respect to the transfer:
(Multiple Choice)
4.9/5 (80)
(80) Carmen and Carlos form White Corporation. Carmen transfers cash of $100,000 for 100 shares in White. Carlos transfers property (basis of $20,000 and fair market value of $80,000) and agrees to serve as manager of White Corporation for one year; in return, Carlos receives 100 shares in White. The value of Carlos's services is $20,000. White Corporation can deduct $20,000 as compensation expense for the value of the services Carlos will render.
(True/False)
4.9/5 (78)
(78) In order to induce Yellow Corporation to build a new manufacturing facility in Knoxville, Tennessee, the city donates land (fair market value of $400,000) and cash of $100,000 to the corporation. Several months after the donation, Yellow Corporation spends $450,000 (which includes the $100,000 received from Knoxville) on the construction of a new plant located on the donated land.
(Multiple Choice)
4.7/5 (76)
(76) In a § 351 transfer, the receipt of boot is not taxed if the shareholder has a realized loss.
(True/False)
4.9/5 (86)
(86) Jill transfers property worth $200,000 (basis of $190,000) to Blue Corporation. In return, she receives 80% of the stock in Blue Corporation (fair market value of $180,000) and a long-term note, executed by Blue and made payable to Jill (fair market value of $20,000). Jill recognizes gain of $20,000 on the transfer.
(True/False)
5.0/5 (86)
(86) Sarah and Tony (mother and son) form Dove Corporation with the following investments: cash by Sarah of $55,000; land by Tony (basis of $35,000 and fair market value of $45,000). Dove Corporation issues 200 shares of stock, 100 each to Sarah and Tony. Thus, each receives stock in Dove worth $50,000.
(Multiple Choice)
4.9/5 (76)
(76) Jane and Walt form Orange Corporation. Jane transfers equipment worth $475,000 (basis of $100,000) and cash of $25,000 to Orange Corporation for 50% of its stock. Walt transfers a building and land worth $525,000 (basis of $200,000) for 50% of Orange's stock and $25,000 cash.
(Multiple Choice)
5.0/5 (85)
(85) In 2004, Donna transferred assets (basis of $300,000 and fair market value of $250,000) to Egret Corporation in return for 200 shares of § 1244 stock. Due to § 351, the transfer was nontaxable; therefore, Donna's basis in the Egret stock is $300,000. In 2005, Donna sells 100 of these shares to Walter (a family friend) for $100,000. In 2011, Egret Corporation files for bankruptcy, and its stock becomes worthless.
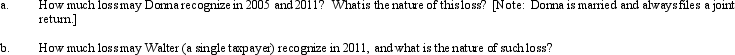
(Essay)
4.9/5 (82)
(82) Barry and Irv form Swift Corporation. Barry transfers cash of $100,000 and equipment (basis of $300,000 and fair market value of $400,000) for 50% of Swift's stock. Irv transfers land and building (basis of $510,000 and fair market value of $450,000) and agrees to manage the business for one year for the other 50% of Swift's stock. The value of Irv's services for one year is $50,000.
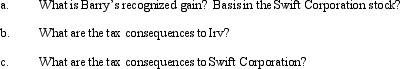
(Essay)
4.8/5 (73)
(73) Wade and Paul form Swan Corporation with the following investments. Wade transfers machinery (basis of $40,000 and fair market value of $100,000), while Paul transfers land (basis of $20,000 and fair market value of $90,000) and services rendered (worth $10,000) in organizing the corporation. Each is issued 25 shares in Swan Corporation. With respect to the transfers:
(Multiple Choice)
4.9/5 (80)
(80) Wren Corporation (a minority shareholder in Lark Corporation) has made loans to Lark Corporation that become worthless in the current year.
(Multiple Choice)
5.0/5 (80)
(80) A shareholder's holding period for stock received under § 351 includes the holding period of the property transferred to the corporation.
(True/False)
4.8/5 (91)
(91) Allen transfers marketable securities with an adjusted basis of $120,000, fair market value of $300,000, for 85% of the stock of Heron Corporation. In addition, he receives cash of $40,000. Allen recognizes a capital gain of $40,000 on the transfer.
(True/False)
4.9/5 (64)
(64) When depreciable property is transferred to a controlled corporation under § 351, any recapture potential disappears and does not carry over to the corporation.
(True/False)
4.9/5 (75)
(75) If both §§ 357(b) and (c) apply to the same transfer (i.e., the liability is not supported by a bona fide business purpose and also exceeds the basis of the properties transferred), § 357(c) predominates.
(True/False)
4.9/5 (82)
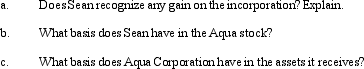
(82) Sean, a sole proprietor, is engaged in a service business and uses the cash basis of accounting. In the current year, Sean incorporates his business by forming Aqua Corporation. In exchange for all of its stock, Aqua receives: assets (basis of $400,000 and fair market value of $2 million), trade accounts payable of $110,000, and loan due to a bank of $390,000. The proceeds from the bank loan were used by Sean to provide operating funds for the business. Aqua Corporation assumes all of the liabilities transferred to it.
(Essay)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)