



 Chat with AI
Exam 4: The Market Forces of Supply and Demand

Exam 1: Ten Lessons From Economics149 Questions
Exam 2: Thinking Like an Economist147 Questions
Exam 3: Interdependence and the Gains From Trade153 Questions
Exam 4: The Market Forces of Supply and Demand222 Questions
Exam 5: Elasticity and Its Application181 Questions
Exam 6: Supply, Demand and Government Policies148 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets177 Questions
Exam 8: Application: The Costs of Taxation141 Questions
Exam 9: Application: International Trade161 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets200 Questions
Exam 15: Monopoly214 Questions
Exam 16: Business Strategy184 Questions
Exam 17: Competition Policy104 Questions
Exam 18: Monopolistic Competition214 Questions
Exam 19: The Markets for the Factors of Production215 Questions
Exam 20: Earnings, Unions and Discrimination206 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice161 Questions
Exam 23: Frontiers of Microeconomics120 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living52 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment59 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy64 Questions
Exam 33: Aggregate Demand and Aggregate Supply82 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment58 Questions
Exam 36: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


Given the following demand schedule, graph Lee's weekly demand curve for Coffee.
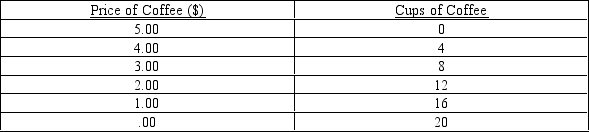
(Essay)
4.8/5  (82)
(82) Supply and demand determine prices and prices allocate the economy's scarce resources.
(True/False)
4.9/5 (76)
(76) Other things being equal, explain the effect each of the following situations will have on either the demand or supply of corn. Explain also what the effect will be on equilibrium price and quantity.
a. corn is now considered by doctors to be the most healthy vegetable
b. there is a decline in the amount of land used to grow corn
c. producers expect the price of corn to fall in the future
d. the price of peas, a substitute for corn, goes up
e. corn is a normal good and incomes fall
f. the price of fertiliser rises
(Short Answer)
4.8/5 (74)
(74) Graph 4-2
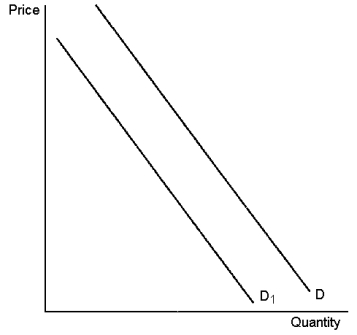 -Refer to Graph 4-2. If the demand curve shifts from D1 to D on the graph, this means that:
 (Multiple Choice)
4.7/5 (81)
(81) Analysing how an event affects a market can be accomplished in two steps.
(True/False)
4.7/5 (75)
(75) A reduction in the price of a product and an increase in the number of buyers in the market affect the demand curve in the same general way.
(True/False)
4.8/5 (66)
(66) Why is the ceteris paribus assumption so important when constructing a demand or supply curve?
(Essay)
4.8/5 (70)
(70) The computer software industry is an example of a perfectly competitive industry.
(True/False)
4.8/5 (80)
(80) Suppose you make jewellery. If the price of gold falls, we would expect you to:
(Multiple Choice)
4.8/5 (87)
(87)  -Refer to the Graph 4-6. If the price were $25:
All else being constant, an increase in the number of cattle delivered to an auction to be marketed would:
(Multiple Choice)
4.9/5 (84)
(84) What will happen to supply or quantity supplied under each of the following situations?
a. the price of the product falls
b. technology improves
c. input prices rise
d. expectations change - you expect the price of your product to rise next month
(Essay)
4.9/5 (74)
(74) Firms that sell their products in a competitive market have limited pricing power because:
(Multiple Choice)
4.8/5 (77)
(77) In a market economy, prices determine who produces each good and how much is produced.
(True/False)
4.8/5 (82)
(82) A market is a group of buyers and sellers of a particular product.
(True/False)
4.9/5 (83)
(83) New Zealand exports possum skins that are used to make leather products. What determinants of demand would be influenced by the following events?
a. New Zealand's possum skin industry is recognised as having conservation benefits as possums are a feral pest in New Zealand.
b. incomes in China grow rapidly
c. the price of calf leather becomes more expensive
(Essay)
4.7/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)