



 Chat with AI
Exam 4: The Market Forces of Supply and Demand

Exam 1: Ten Lessons From Economics149 Questions
Exam 2: Thinking Like an Economist147 Questions
Exam 3: Interdependence and the Gains From Trade153 Questions
Exam 4: The Market Forces of Supply and Demand222 Questions
Exam 5: Elasticity and Its Application181 Questions
Exam 6: Supply, Demand and Government Policies148 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets177 Questions
Exam 8: Application: The Costs of Taxation141 Questions
Exam 9: Application: International Trade161 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets200 Questions
Exam 15: Monopoly214 Questions
Exam 16: Business Strategy184 Questions
Exam 17: Competition Policy104 Questions
Exam 18: Monopolistic Competition214 Questions
Exam 19: The Markets for the Factors of Production215 Questions
Exam 20: Earnings, Unions and Discrimination206 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice161 Questions
Exam 23: Frontiers of Microeconomics120 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living52 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment59 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy64 Questions
Exam 33: Aggregate Demand and Aggregate Supply82 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment58 Questions
Exam 36: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


Sally tells you that she thinks the price of her favourite stationery will increase in the near future. She will probably respond by:
(Multiple Choice)
4.7/5  (80)
(80) Fill in the accompanying table, showing whether equilibrium price and equilibrium quantity go up, down or stay the same.
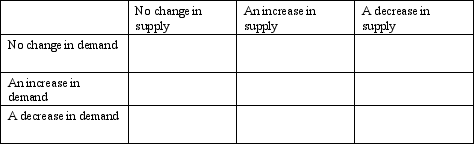
(Essay)
4.9/5 (83)
(83) At the equilibrium price, quantity demanded is equal to quantity supplied.
(True/False)
4.8/5 (82)
(82) Suppose that the equilibrium price in a market is $100, but the existing market price is $80. What will happen in the market? What if the existing market price is $150?
(Essay)
4.9/5 (89)
(89) In a market, to find the total amount supplied at a particular price:
(Multiple Choice)
4.8/5 (89)
(89) Suppose that the demand for crocodile leather falls after a decrease in incomes. This would mean that crocodile leather is:
(Multiple Choice)
4.7/5 (82)
(82) Suppose at the current price of sugar, sugar suppliers have a surplus. This must mean that:
(Multiple Choice)
4.8/5 (76)
(76) In a free market system, what coordinates the actions of millions of people with their varying abilities and desires?
(Multiple Choice)
4.8/5 (80)
(80) The intersection of the demand and supply curves is a unique point termed:
(Multiple Choice)
4.8/5 (95)
(95) If a good is 'normal', then an increase in income will result in:
(Multiple Choice)
4.8/5 (88)
(88) Table 4-2
 -Refer to Table 4-2. In the table shown, suppose the current price was $40. This would mean:
 (Multiple Choice)
4.9/5 (69)
(69) If an event occurred which changed a market equilibrium, how would an economist go about analysing the change in equilibrium?
(Essay)
4.9/5 (73)
(73) There are thousands of wheat farmers who produce and sell wheat, and there are millions of consumers who use wheat and wheat products. The market for wheat would be considered:
(Multiple Choice)
4.8/5 (77)
(77) A competitive market is a market in which there are enough buyers and sellers that each has a negligible impact on the market price.
(True/False)
4.9/5 (88)
(88) Which of the following are the words most commonly used by economists?
(Multiple Choice)
4.8/5 (89)
(89) The price of any good adjusts until quantity demanded equals quantity supplied.
(True/False)
4.8/5 (75)
(75) Supply and demand are the concepts that economists use most often.
(True/False)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)