



 Chat with AI
Exam 8: Perfect Competition

Exam 1: Introducing the Economic Way of Thinking85 Questions
Exam 2: Production Possibilities Opportunity Cost and Economic Growth107 Questions
Exam 3: Market Demand and Supply176 Questions
Exam 4: Markets in Action137 Questions
Exam 5: Price Elasticity of Demand and Supply151 Questions
Exam 6: Consumer Choice Theory96 Questions
Exam 7: Production Costs131 Questions
Exam 8: Perfect Competition126 Questions
Exam 9: Monopoly81 Questions
Exam 10: Monopolistic Competition and Oligopoly97 Questions
Exam 11: Labor Markets105 Questions
Exam 12: Income Distribution Poverty and Discrimination57 Questions
Exam 13: Antitrust and Regulation96 Questions
Exam 14: Environmental Economics47 Questions
Exam 15: Gross Domestic Product109 Questions
Exam 16: Business Cycles and Unemployment94 Questions
Exam 17: Inflation56 Questions
Exam 18: The Keynesian Model111 Questions
Exam 19: The Keynesian Model in Action105 Questions
Exam 20: Aggregate Demand and Supply94 Questions
Exam 21: Fiscal Policy108 Questions
Exam 22: The Public Sector55 Questions
Exam 23: Federal Deficits Surpluses and the National Debt42 Questions
Exam 24: Money and the Federal Reserve System75 Questions
Exam 25: Money Creation117 Questions
Exam 26: Monetary Policy106 Questions
Exam 27: The Phillips Curve and Expectations Theory59 Questions
Exam 28: International Trade and Finance127 Questions
Exam 29: Economies in Transition46 Questions
Exam 30: Growth and the Less Developed Countries55 Questions
Exam 31: Understanding Direct and Inverse Relationships between Variables172 Questions
Select questions type


The neighborhood ice cream shop finds that when it charges $3 per ice cream cone, its total revenues are $90,000. It has total variable costs of $30,000 and total fixed costs of $40,000. From this we can infer the:
(Multiple Choice)
5.0/5  (81)
(81) Exhibit 8-3 Cost per unit curves
 As shown in Exhibit 8-3, the firm will produce in the short run if the price is at least equal to:
 (Multiple Choice)
4.9/5 (84)
(84) Exhibit 8-12 Marginal revenue and cost per unit curves
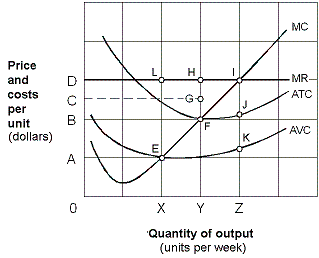 As shown in Exhibit 8-12, the firm will shut down in the short-run at a price below:
 (Multiple Choice)
4.9/5 (89)
(89) In the short run, a firm will stay in business as long as:
(Multiple Choice)
4.8/5 (75)
(75) Exhibit 8-3 Cost per unit curves
 As shown in Exhibit 8-3, the price at which the firm earns zero economic profit in the short-run is:
 (Multiple Choice)
4.8/5 (77)
(77) If the expansion of output in an industry leads to unchanged resource prices, the industry is most likely to be a(n):
(Multiple Choice)
4.8/5 (77)
(77) Exhibit 8-12 Marginal revenue and cost per unit curves
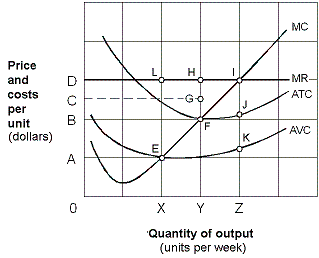 As shown in Exhibit 8-12, the firm will not produce in the short-run if the price is below:
 (Multiple Choice)
4.9/5 (76)
(76) Consider a firm operating with the following: price = 10; MR = 10; MC = 10; ATC = 10. This firm is:
(Multiple Choice)
4.9/5 (78)
(78) Exhibit 8-4 Marginal cost and revenue for a firm
 In Exhibit 8-4, what is this firm's profit-maximizing rate of output?
 (Multiple Choice)
4.9/5 (74)
(74) A perfectly competitive firm sells its output for $100 per unit and marginal cost is $100 per unit. To maximize short-run profit, the firm should:
(Multiple Choice)
4.8/5 (91)
(91) The price-taker firm should discontinue production immediately if:
(Multiple Choice)
4.8/5 (84)
(84) In a perfectly competitive industry, assume the short-run average total cost increases as the output of the industry expands. In the long run, the industry supply curve will:
(Multiple Choice)
4.9/5 (83)
(83) The profit maximizing or loss minimizing quantity of output for any firm to produce exists at that output level in which:
(Multiple Choice)
4.9/5 (91)
(91) Exhibit 8-19 Long-run perfectly competitive industry
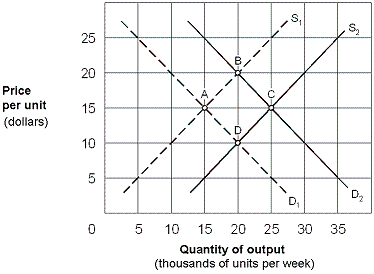 As shown in Exhibit 8-19, assume that a perfectly competitive industry is in long-run equilibrium at point A and the demand curve shifts from D1 to D2. The result is a long-run supply curve drawn from point:
 (Multiple Choice)
4.8/5 (81)
(81) The demand for the product of a competitive price-taker firm is:
(Multiple Choice)
4.8/5 (79)
(79) The market price for wallets is $20. Your technology is such that at your most efficient production point, the average total cost of producing a wallet is $2.50. Your manager runs into your office and shouts, "Boss!!! Average costs are rising!! Average costs are rising!!" To make a profit-maximizing decision, you should:
(Multiple Choice)
4.9/5 (73)
(73) Which of the following best describes why a perfectly competitive firm will sometimes continue producing in the short run even if it incurs a loss?
(Multiple Choice)
4.9/5 (72)
(72) A firm operating in a perfectly competitive market is a price taker because:
(Multiple Choice)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)