



 Chat with AI
Exam 10: Monopolistic Competition and Oligopoly

Exam 1: Introducing the Economic Way of Thinking85 Questions
Exam 2: Production Possibilities Opportunity Cost and Economic Growth107 Questions
Exam 3: Market Demand and Supply176 Questions
Exam 4: Markets in Action137 Questions
Exam 5: Price Elasticity of Demand and Supply151 Questions
Exam 6: Consumer Choice Theory96 Questions
Exam 7: Production Costs131 Questions
Exam 8: Perfect Competition126 Questions
Exam 9: Monopoly81 Questions
Exam 10: Monopolistic Competition and Oligopoly97 Questions
Exam 11: Labor Markets105 Questions
Exam 12: Income Distribution Poverty and Discrimination57 Questions
Exam 13: Antitrust and Regulation96 Questions
Exam 14: Environmental Economics47 Questions
Exam 15: Gross Domestic Product109 Questions
Exam 16: Business Cycles and Unemployment94 Questions
Exam 17: Inflation56 Questions
Exam 18: The Keynesian Model111 Questions
Exam 19: The Keynesian Model in Action105 Questions
Exam 20: Aggregate Demand and Supply94 Questions
Exam 21: Fiscal Policy108 Questions
Exam 22: The Public Sector55 Questions
Exam 23: Federal Deficits Surpluses and the National Debt42 Questions
Exam 24: Money and the Federal Reserve System75 Questions
Exam 25: Money Creation117 Questions
Exam 26: Monetary Policy106 Questions
Exam 27: The Phillips Curve and Expectations Theory59 Questions
Exam 28: International Trade and Finance127 Questions
Exam 29: Economies in Transition46 Questions
Exam 30: Growth and the Less Developed Countries55 Questions
Exam 31: Understanding Direct and Inverse Relationships between Variables172 Questions
Select questions type


The kinked demand theory attempts to explain why an oligopolistic firm:

Free
(Multiple Choice)
4.9/5  (85)
(85) Correct Answer: Verified
C
The automobile, steel, and oil markets are all examples of:
Free
(Multiple Choice)
4.8/5 (98)
(98) Correct Answer:Verified
VerifiedD
Exhibit 10-2 A monopolistic competitive firm
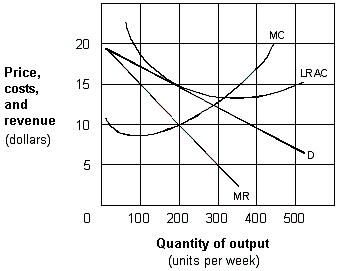 If all firms in a monopolistic competitive industry have demand and cost curves like those shown in Exhibit 10-2, we would expect that in the long run:
Free
(Multiple Choice)
4.8/5 (75)
(75) Correct Answer:Verified
VerifiedC
Which of the following is always associated with monopolistic competition?
(Multiple Choice)
4.9/5 (72)
(72) Exhibit 10-2 A monopolistic competitive firm
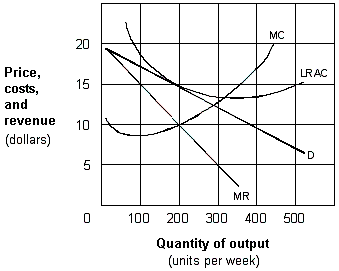 To maximize long-run profits, the monopolistically competitive firm shown in Exhibit 10-2 will charge a price per unit of:
 (Multiple Choice)
4.8/5 (83)
(83) The theory of monopolistic competition predicts that in long-run equilibrium a monopolistically competitive firm will:
(Multiple Choice)
4.8/5 (92)
(92) When the price and output decisions of one firm include the possible price and output reactions of the firm's rivals, the market is
(Multiple Choice)
5.0/5 (73)
(73) Which of the following is a distinction between perfectly competitive and monopolistic competition?
(Multiple Choice)
4.9/5 (79)
(79) The industry that most closely approximates the conditions of the oligopoly model is:
(Multiple Choice)
4.8/5 (71)
(71) Compared to monopoly, the market results with monopolistic competition are usually expected to be:
(Multiple Choice)
4.9/5 (75)
(75) Suppose Ford, GM, and Dodge make the majority of pick-up trucks sold in the United States If they all sell for approximately the same price, and Ford offers a $2,000 rebate on new truck sales, what can Ford expect to see?
(Multiple Choice)
4.8/5 (88)
(88) Exhibit 10-1 A monopolistic competitive firm
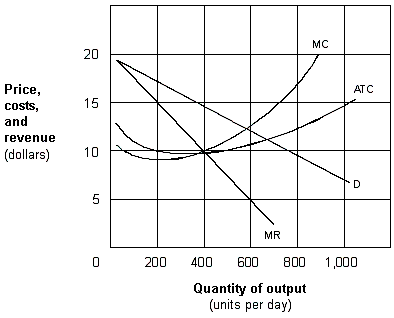 As represented in Exhibit 10-1, the maximum long-run economic profit earned by this monopolistic competitive firm is:
 (Multiple Choice)
4.8/5 (77)
(77) Which of the following is true for perfect competition, monopolistic competition, and monopoly?
(Multiple Choice)
4.7/5 (78)
(78) Exhibit 10-2 A monopolistic competitive firm
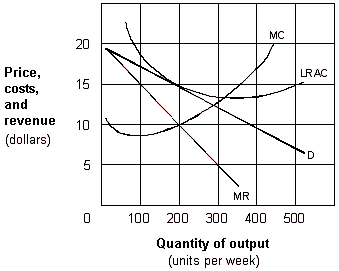 Comparing the monopolistically competitive firm in Exhibit 10-2 to the long-run profit-maximizing outcome for a perfectly competitive firm with a price of $15 per unit and a quantity of 600,
 (Multiple Choice)
4.8/5 (76)
(76) In long-run equilibrium, output is expanded to the minimum long-run average total cost by:
(Multiple Choice)
4.9/5 (74)
(74) The market for Product A has many sellers, selling identical products, each earning an economic profit of zero in the long run. The market for Product B has many sellers, selling differentiated products, each earning an economics profit of zero in the long run. Given this information, one can conclude that
(Multiple Choice)
4.8/5 (82)
(82) Which of the following most closely approximates the conditions of a monopolistically competitive market?
(Multiple Choice)
4.7/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)