



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


Figure 7-22 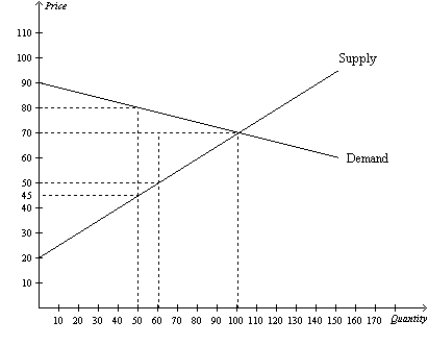 -Refer to Figure 7-22. If the price decreases from $80 to $70 due to a shift in the supply curve, consumer surplus increases by
 (Multiple Choice)
4.9/5  (77)
(77) Table 7-14
Seller
Cost
LeBron
$700
Kobe
$600
Kevin
$450
Steve
$400
-Refer to Table 7-14. You and your best friend want to hire a professional photographer to take pictures of your two families. The table shows the costs of the four potential sellers in the local photography market. You and your friend take bids from the sellers. Who offers the two winning bids, and what do they offer to charge for the photography sessions?
(Multiple Choice)
4.9/5 (75)
(75) David tunes pianos in his spare time for extra income. Buyers of his service are willing to pay $135 per tuning. One particular week, David is willing to tune the first piano for $115, the second piano for $125, the third piano for $140, and the fourth piano for $175. Assume David is rational in deciding how many pianos to tune. His producer surplus is
(Multiple Choice)
5.0/5 (77)
(77) Jeff decides that he would pay as much as $3,000 for a new laptop computer. He buys the computer and realizes consumer surplus of $700. How much did Jeff pay for his computer?
(Multiple Choice)
4.9/5 (84)
(84) Consumer surplus is the amount a buyer actually has to pay for a good minus the amount the buyer is willing to pay for it.
(True/False)
4.9/5 (76)
(76) All else equal, an increase in demand will always increase consumer surplus.
(True/False)
4.9/5 (88)
(88) Figure 7-19 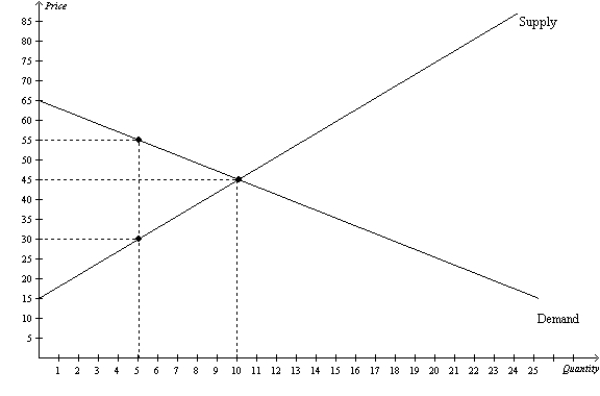 -Refer to Figure 7-19. If the government imposes a price floor of $55 in this market, then total surplus will be
 (Multiple Choice)
4.9/5 (81)
(81) Table 7-1 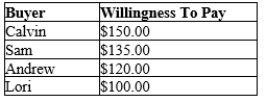 -Refer to Table 7-1. If price of the product is $135, then the total consumer surplus is
 (Multiple Choice)
4.9/5 (71)
(71) Table 7-6
For each of three potential buyers of apples, the table displays the willingness to pay for the first three apples of the day. Assume Xavier, Yadier, and Zavi are the only three buyers of apples, and only three apples can be supplied per day. 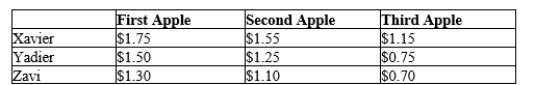 -Refer to Table 7-6. If the market price of an apple increases from $1.40 to $1.60, then consumer surplus
 (Multiple Choice)
4.9/5 (67)
(67) Table 7-10
The following table represents the costs of five possible sellers.
Seller
Cost
Abby
$1,600
Bobby
$1,300
Dianne
$1,100
Evaline
$900
Carlos
$800
-Refer to Table 7-10. If the price is $1,l50, who would be willing to supply the product?
(Multiple Choice)
4.8/5 (79)
(79) Scenario 7-2
Suppose market demand and market supply are given by the equations:  -Refer to Scenario 7-2. How much is total producer surplus at the equilibrium price in this market?
 (Essay)
4.8/5 (70)
(70) Which of the following is true when the price of a good or service rises?
(Multiple Choice)
4.9/5 (79)
(79) Figure 7-4 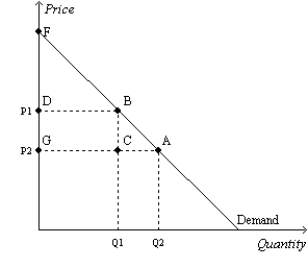 -Refer to Figure 7-4. Which area represents consumer surplus at a price of P2?
 (Multiple Choice)
4.8/5 (72)
(72) Table 7-14
Seller
Cost
LeBron
$700
Kobe
$600
Kevin
$450
Steve
$400
-Refer to Table 7-14. You want to hire a professional photographer to take pictures of your family. The table shows the costs of the four potential sellers in the local photography market. You hire Kevin for a price of $500. What is his producer surplus?
(Multiple Choice)
4.9/5 (89)
(89) Efficiency is related to the size of the economic pie, whereas equality is related to how the pie gets sliced and distributed.
(True/False)
4.9/5 (70)
(70) Kristi sells purses. Her cost is $35 per purse. On a certain day, she sells 12 purses, and her producer surplus for that day amounts to $180. Kristi sold each purse for
(Multiple Choice)
4.8/5 (84)
(84) Figure 7-15  -Refer to Figure 7-15. Suppose producer surplus is larger than C but smaller than A+B+C. The price of the good must be
 (Multiple Choice)
4.9/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)