



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


Figure 7-16 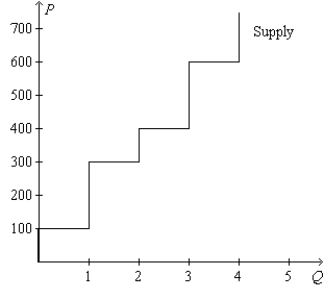 -Refer to Figure 7-16. If the price of the good is $500, then producer surplus amounts to
 (Multiple Choice)
4.8/5  (81)
(81) Figure 7-27  -Refer to Figure 7-27. Buyers who value this good less than the equilibrium price are represented by which line segment?
 (Multiple Choice)
4.8/5 (86)
(86) Given the following two equations:
1)Total Surplus = Consumer Surplus + Producer Surplus
2)Total Surplus = Value to Buyers - Cost to Sellers
Show how equation (1) can be used to derive equation (2).
(Essay)
4.9/5 (88)
(88) Figure 7-34 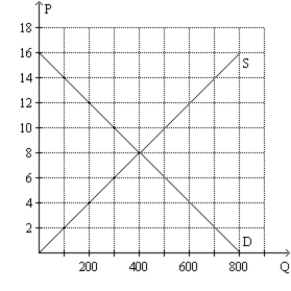 -Refer to Figure 7-34. Suppose there is initially a price floor set at $10 in this market. If the government removed the price floor, by how much would total consumer surplus increase for those consumers who were purchasing the good when the price floor was in place?
 (Essay)
4.9/5 (84)
(84) Table 7-5
For each of three potential buyers of oranges, the table displays the willingness to pay for the first three oranges of the day. Assume Allison, Bob, and Charisse are the only three buyers of oranges, and only three oranges can be supplied per day. 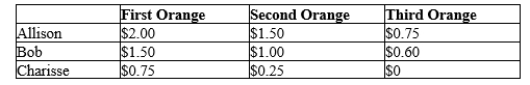 -Refer to Table 7-5. Which of the following statements is correct?
 (Multiple Choice)
4.9/5 (70)
(70) Table 7-12
The numbers reveal the opportunity costs of providing 10 piano lessons of equal quality.
Seller
Cost
Marcia
$200
Jan
$250
Cindy
$350
Greg
$400
Peter
$700
Bobby
$800
-Refer to Table 7-12. The equilibrium market price for 10 piano lessons is $400. What is the total producer surplus in the market?
(Multiple Choice)
5.0/5 (67)
(67) Table 7-4
The numbers in Table 7-1 reveal the maximum willingness to pay for a ticket to a Chicago Cubs vs. St. Louis Cardinal's baseball game at Wrigley Field. 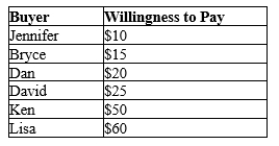 -Refer to Table 7-4. If you have a ticket that you sell to the group in an auction, who will buy the ticket?
 (Multiple Choice)
5.0/5 (83)
(83) When markets fail, public policy can potentially remedy the problem and increase economic efficiency.
(True/False)
4.9/5 (73)
(73) Figure 7-26 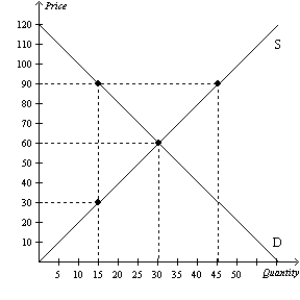 -Refer to Figure 7-26. If the government imposes a price floor of $90 in this market, then consumer surplus will be
 (Multiple Choice)
4.8/5 (56)
(56) Suppose that the equilibrium price in the market for widgets is $5. If a law increased the minimum legal price for widgets to $6, producer surplus
(Multiple Choice)
4.8/5 (79)
(79) Figure 7-16
-Refer to Figure 7-16. Producer surplus amounts to $300 if the price of the good is
-Refer to Figure 7-16. Producer surplus amounts to $300 if the price of the good is (Multiple Choice)
4.8/5 (91)
(91) Figure 7-19 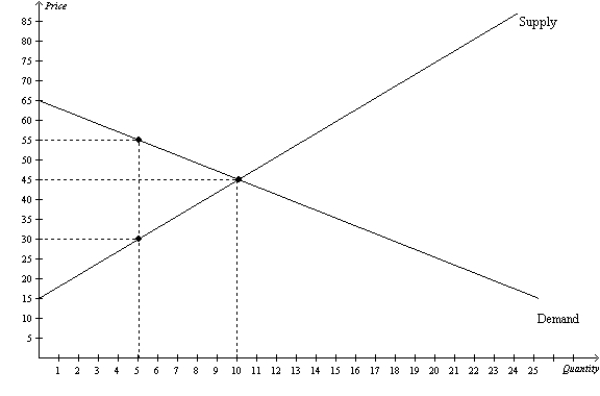 -Refer to Figure 7-19. At the equilibrium price, total surplus is
 (Multiple Choice)
4.9/5 (69)
(69) The maximum price that a buyer will pay for a good is called
(Multiple Choice)
4.9/5 (65)
(65) Figure 7-10 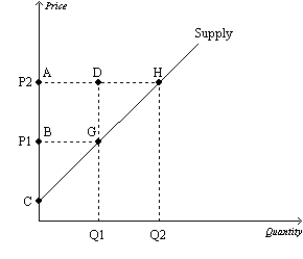 -Refer to Figure 7-10. When the price rises from P1 to P2, which area represents the increase in producer surplus to existing producers?
 (Multiple Choice)
5.0/5 (91)
(91) If the current allocation of resources in the market for wallpaper is efficient, then it must be the case that
(Multiple Choice)
4.8/5 (85)
(85) Figure 7-11 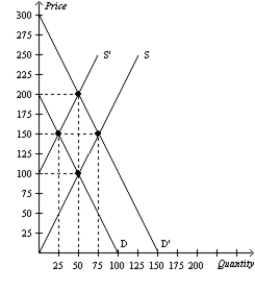 -Refer to Figure 7-11. If the supply curve is S and the demand curve shifts from D to D', what is the increase in producer surplus to existing producers?
 (Multiple Choice)
4.8/5 (77)
(77) Which of the following will cause no change in producer surplus?
(Multiple Choice)
4.9/5 (84)
(84) Janine would be willing to pay $50 to see Les Misérables, but she buys a ticket for only $30. Janine values the performance at
(Multiple Choice)
4.7/5 (82)
(82) Answer each of the following questions about demand and consumer surplus.
a.What is consumer surplus, and how is it measured?
b.What is the relationship between the demand curve and the willingness to pay?
c.Other things equal, what happens to consumer surplus if the price of a good falls? Why? Illustrate using a demand curve.
d.In what way does the demand curve represent the benefit consumers receive from participating in a market? In addition to the demand curve, what else must be considered to determine consumer surplus?
(Essay)
4.8/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)