



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


Efficiency refers to whether a market outcome is fair, while equality refers to whether the maximum amount of output was produced from a given number of inputs.
(True/False)
4.9/5  (80)
(80) Market power and externalities are examples of market failures.
(True/False)
4.8/5 (94)
(94) Suppose that the equilibrium price in the market for widgets is $5. If a law increased the minimum legal price for widgets to $6,
(Multiple Choice)
4.9/5 (73)
(73) Table 7-3
The only four consumers in a market have the following willingness to pay for a good: 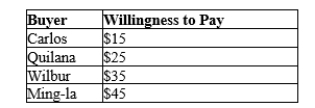 -Refer to Table 7-3. If the price is $20, then consumer surplus in the market is
 (Multiple Choice)
4.7/5 (78)
(78) Ray buys a new tractor for $118,000. He receives consumer surplus of $13,000 on his purchase. Ray's willingness to pay is
(Multiple Choice)
4.9/5 (84)
(84) Table 7-3
The only four consumers in a market have the following willingness to pay for a good:
-Refer to Table 7-3. Who experiences the largest loss of consumer surplus when the price of the good increases from $20 to $22?
-Refer to Table 7-3. Who experiences the largest loss of consumer surplus when the price of the good increases from $20 to $22? (Multiple Choice)
4.7/5 (93)
(93) If a consumer places a value of $15 on a particular good and if the price of the good is $17, then the
(Multiple Choice)
4.9/5 (84)
(84) Suppose John's cost for performing some carpentry work is $120. If John is paid $200 for the carpentry work, what is his producer surplus?
(Short Answer)
4.8/5 (72)
(72) Scenario 7-2
Suppose market demand and market supply are given by the equations:  -Refer to Scenario 7-2. Suppose a reduction in input prices shifts the market supply curve to
 By how much does total producer surplus increase as a result of this supply shift?
-Refer to Scenario 7-2. Suppose a reduction in input prices shifts the market supply curve to
By how much does total producer surplus increase as a result of this supply shift? (Essay)
4.9/5 (80)
(80) Figure 7-12 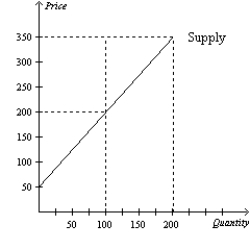 -Refer to Figure 7-12. If the equilibrium price is $200, what is the producer surplus?
 (Multiple Choice)
4.8/5 (87)
(87) Producer surplus is the cost of production minus the amount a seller is paid.
(True/False)
4.8/5 (90)
(90) Figure 7-1 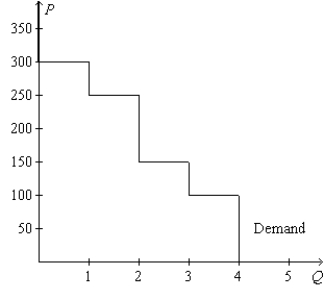 -Refer to Figure 7-1. The value of the good to consumers minus the cost of the good to consumers amounts to $325 if the price of the good is
 (Multiple Choice)
4.9/5 (83)
(83) Which of the following will cause an increase in producer surplus?
(Multiple Choice)
4.8/5 (74)
(74) A seller is willing to sell a product only if the seller receives a price that is at least as great as the
(Multiple Choice)
4.9/5 (73)
(73) Bill created a new software program he is willing to sell for $200. He sells his first copy and enjoys a producer surplus of $150. What is the price paid for the software?
(Multiple Choice)
4.7/5 (76)
(76) Figure 7-34 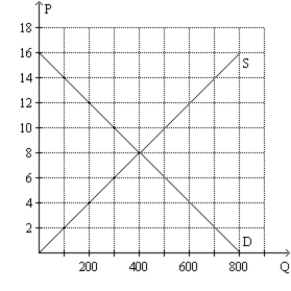 -Refer to Figure 7-34. Suppose there is initially a price floor set at $10 in this market. If the government removed the price floor, by how much would total producer surplus change, assuming the producers with the lowest cost were the ones supplying the market when the price floor was in place?
 (Essay)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)