



 Chat with AI
Exam 2: The Production Possibility Model, Trade, and Globalization

Exam 1: Economics and Economic Reasoning158 Questions
Exam 2: The Production Possibility Model, Trade, and Globalization133 Questions
Exam 3: Economic Institutions163 Questions
Exam 4: Supply and Demand182 Questions
Exam 5: Using Supply and Demand163 Questions
Exam 6: Describing Supply and Demand: Elasticities216 Questions
Exam 7: Taxation and Government Intervention201 Questions
Exam 8: Market Failure Versus Government Failure197 Questions
Exam 9: Comparative Advantage, Exchange Rates, and Globalization118 Questions
Exam 10: International Trade Policy99 Questions
Exam 11: Production and Cost Analysis I194 Questions
Exam 12: Production and Cost Analysis II152 Questions
Exam 13: Perfect Competition170 Questions
Exam 14: Monopoly and Monopolistic Competition274 Questions
Exam 15: Oligopoly and Antitrust Policy142 Questions
Exam 16: Real-World Competition and Technology108 Questions
Exam 17: Work and the Labor Market150 Questions
Exam 18: Who Gets What the Distribution of Income131 Questions
Exam 19: The Logic of Individual Choice: the Foundation of Supply and Demand170 Questions
Exam 20: Game Theory, Strategic Decision Making, and Behavioral Economics103 Questions
Exam 21: Thinking Like a Modern Economist97 Questions
Exam 22: Behavioral Economics and Modern Economic Policy126 Questions
Exam 23: Microeconomic Policy, Economic Reasoning, and Beyond134 Questions
Exam 24: Economic Growth, Business Cycles, and Unemployment124 Questions
Exam 25: Measuring and Describing the Aggregate Economy229 Questions
Exam 26: The Keynesian Short-Run Policy Model: Demand-Side Policies220 Questions
Exam 27: The Classical Long-Run Policy Model: Growth and Supply-Side Policies133 Questions
Exam 28: The Financial Sector and the Economy214 Questions
Exam 29: Monetary Policy243 Questions
Exam 30: Financial Crises, Panics, and Unconventional Monetary Policy109 Questions
Exam 31: Deficits and Debt: the Austerity Debate150 Questions
Exam 32: The Fiscal Policy Dilemma119 Questions
Exam 33: Jobs and Unemployment78 Questions
Exam 34: Inflation, Deflation, and Macro Policy175 Questions
Exam 35: International Financial Policy211 Questions
Exam 36: Macro Policy in a Global Setting134 Questions
Exam 37: Structural Stagnation and Globalization125 Questions
Exam 38: Macro Policy in Developing Countries142 Questions
Select questions type


Up through the early decades of the 20th century, many countries remained closed to trade, charging high tariffs or imposing strict quotas on imported goods. In 1948, 23 countries joined the General Agreement on Tariffs and Trade (GATT), which sought to set out rules for trade and enhance future negotiations. The reduction in tariffs as a result of GATT probably brought about:
(Multiple Choice)
4.8/5  (80)
(80) This production possibility table illustrates: Eggs Rye 10 0 8 10 6 20 4 30 2 40 0 50
(Multiple Choice)
4.9/5 (79)
(79) Two nations with differing comparative advantages will be able to consume more if they specialize and trade with each other than if they did not specialize or trade with each other.
(True/False)
4.8/5 (81)
(81) Increasing marginal opportunity cost means that the production possibility curve is:
(Multiple Choice)
4.9/5 (83)
(83) What is the argument for laissez faire policy in the context of benefits from trade?
(Essay)
4.8/5 (80)
(80) What two lessons can you learn from a production possibilities curve?
(Essay)
4.9/5 (86)
(86) Assume that Belgium and Pakistan have linear production possibilities curves as shown in the graph below.Explain how they can both consume a combination of textiles and chocolate that lies outside their individual production possibility curves.
(Essay)
4.9/5 (88)
(88) To graphically demonstrate the principle of increasing marginal opportunity cost, the production possibility curve must be:
(Multiple Choice)
4.8/5 (77)
(77) Refer to the graph below. 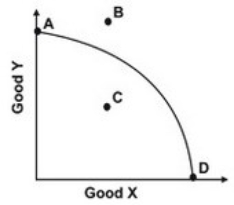 If the production possibility curve shifts along the Good Y axis, which point will remain as a point of efficiency?
 (Multiple Choice)
4.9/5 (73)
(73) What does it mean when we say that a country has comparative advantage in a specific good?
(Essay)
5.0/5 (84)
(84) Refer to the graph below. 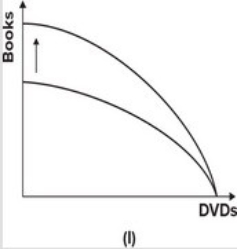
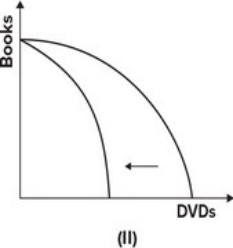
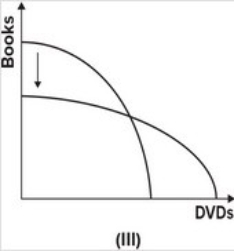
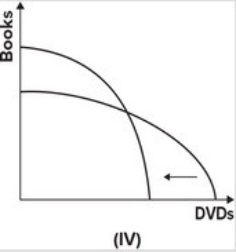 Which of the shifts explains what will happen to the production possibility curve if the cost of producing books goes down while the cost of producing DVDs goes up?
 (Multiple Choice)
4.9/5 (68)
(68) Refer to the graphs shown. The discovery of a new supply of resources used only in the production of guns can be shown by which shift? 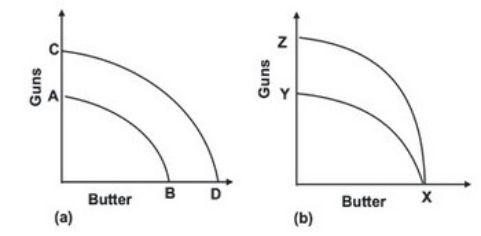
(Multiple Choice)
4.9/5 (97)
(97) Given the production possibility curve shown below, the opportunity cost of listening to each additional album when moving from point B to point A is on average: 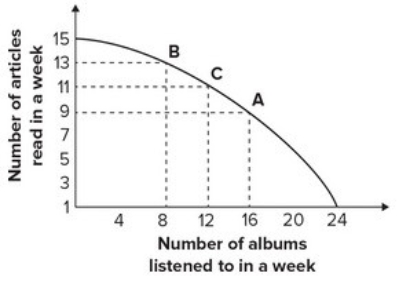
(Multiple Choice)
4.9/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)