



 Chat with AI
Exam 15: Monopoly

Exam 1: Ten Principles of Economics439 Questions
Exam 2: Thinking Like an Economist617 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand697 Questions
Exam 5: Elasticity and Its Application594 Questions
Exam 6: Supply, Demand, and Government Policies645 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets549 Questions
Exam 8: Application: the Costs of Taxation513 Questions
Exam 9: Application: International Trade492 Questions
Exam 10: Externalities524 Questions
Exam 11: Public Goods and Common Resources433 Questions
Exam 12: The Design of the Tax System549 Questions
Exam 13: The Costs of Production420 Questions
Exam 14: Firms in Competitive Markets543 Questions
Exam 15: Monopoly637 Questions
Exam 16: Monopolistic Competition580 Questions
Exam 17: Oligopoly488 Questions
Exam 18: The Markets for the Factors of Production564 Questions
Exam 19: Earnings and Discrimination490 Questions
Exam 20: Income Inequality and Poverty455 Questions
Exam 21: The Theory of Consumer Choice431 Questions
Exam 22: Frontiers of Microeconomics440 Questions
Exam 23: Measuring a Nations Income520 Questions
Exam 24: Measuring the Cost of Living529 Questions
Exam 25: Production and Growth505 Questions
Exam 26: Saving, Investment, and the Financial System564 Questions
Exam 27: The Basic Tools of Finance500 Questions
Exam 28: Unemployment678 Questions
Exam 29: The Monetary System515 Questions
Exam 30: Money Growth and Inflation481 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts522 Questions
Exam 32: A Macroeconomic Theory of the Open Economy475 Questions
Exam 33: Aggregate Demand and Aggregate Supply562 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand508 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment491 Questions
Exam 36: Six Debates Over Macroeconomic Policy372 Questions
Select questions type


When a firm experiences continually declining average total costs,
(Multiple Choice)
4.7/5  (87)
(87) Copyrights and patents are examples of barriers to entry that give firms monopoly pricing powers.
(True/False)
4.8/5 (80)
(80) Monopoly pricing prevents some mutually beneficial trades from taking place. These unrealized, mutually beneficial trades are
(Multiple Choice)
4.9/5 (81)
(81) Natural monopolies differ from other forms of monopoly because they are
(Multiple Choice)
4.9/5 (84)
(84) Figure 15-18  -Refer to Figure 15-18. If there are no fixed costs of production, monopoly profit without price discrimination equals
 (Multiple Choice)
4.9/5 (87)
(87) Which of the following is the preferred strategy for the government to follow to remedy the inefficient allocation of resources associated with monopolies?
(Multiple Choice)
4.8/5 (66)
(66) Selling a good at a price determined by the intersection of the demand curve and the marginal cost curve is consistent with the
(Multiple Choice)
4.8/5 (73)
(73) Scenario 15-7
Black Box Cable TV is able to purchase an exclusive right to sell a premium movie channel (PMC) in its market area. Let's assume that Black Box Cable pays $150,000 a year for the exclusive marketing rights to PMC. Since Black Box has already installed cable to all of the homes in its market area, the marginal cost of delivering PMC to subscribers is zero. The manager of Black Box needs to know what price to charge for the PMC service to maximize her profit. Before setting price, she hires an economist to estimate demand for the PMC service. The economist discovers that there are two types of subscribers who value premium movie channels. First are the 4,000 die-hard TV viewers who will pay as much as $150 a year for the new PMC premium channel. Second, the PMC channel will appeal to 20,000 occasional TV viewers who will pay as much as $20 a year for a subscription to PMC.
-Refer to Scenario 15-7. If Black Box Cable TV is able to price discriminate, what would be the maximum amount of profit it could generate?
(Multiple Choice)
4.8/5 (79)
(79) Some companies merge in order to lower costs through efficient joint production.
(True/False)
4.8/5 (79)
(79) Figure 15-19  -Refer to Figure 15-19. If the monopoly firm perfectly price discriminates, then consumer surplus amounts to
 (Multiple Choice)
4.7/5 (76)
(76) Figure 15-14 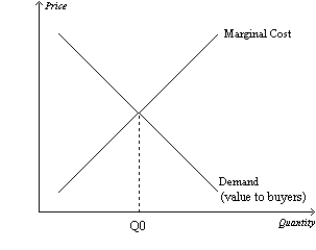 -Refer to Figure 15-14. If the monopoly operates at an output level less than Q0, then an increase in output toward (but not exceeding) Q0 would
 (Multiple Choice)
5.0/5 (83)
(83) Firms with substantial monopoly power are quite common because many goods are unique.
(True/False)
4.8/5 (83)
(83) Figure 15-23  -Refer to Figure 15-23. If a regulator requires the firm to charge an average cost price, what quantity will the firm produce?
 (Short Answer)
4.8/5 (74)
(74) Granting a pharmaceutical company a patent for a new medicine will lead to
(Multiple Choice)
4.9/5 (79)
(79) Table 15-19
A monopolist faces the following demand curve:  -Refer to Table 15-19. If a monopolist faces a constant marginal cost of $5, how much output should the firm produce in order to equate marginal revenue with marginal cost?
 (Multiple Choice)
4.7/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)