



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics439 Questions
Exam 2: Thinking Like an Economist617 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand697 Questions
Exam 5: Elasticity and Its Application594 Questions
Exam 6: Supply, Demand, and Government Policies645 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets549 Questions
Exam 8: Application: the Costs of Taxation513 Questions
Exam 9: Application: International Trade492 Questions
Exam 10: Externalities524 Questions
Exam 11: Public Goods and Common Resources433 Questions
Exam 12: The Design of the Tax System549 Questions
Exam 13: The Costs of Production420 Questions
Exam 14: Firms in Competitive Markets543 Questions
Exam 15: Monopoly637 Questions
Exam 16: Monopolistic Competition580 Questions
Exam 17: Oligopoly488 Questions
Exam 18: The Markets for the Factors of Production564 Questions
Exam 19: Earnings and Discrimination490 Questions
Exam 20: Income Inequality and Poverty455 Questions
Exam 21: The Theory of Consumer Choice431 Questions
Exam 22: Frontiers of Microeconomics440 Questions
Exam 23: Measuring a Nations Income520 Questions
Exam 24: Measuring the Cost of Living529 Questions
Exam 25: Production and Growth505 Questions
Exam 26: Saving, Investment, and the Financial System564 Questions
Exam 27: The Basic Tools of Finance500 Questions
Exam 28: Unemployment678 Questions
Exam 29: The Monetary System515 Questions
Exam 30: Money Growth and Inflation481 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts522 Questions
Exam 32: A Macroeconomic Theory of the Open Economy475 Questions
Exam 33: Aggregate Demand and Aggregate Supply562 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand508 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment491 Questions
Exam 36: Six Debates Over Macroeconomic Policy372 Questions
Select questions type


Scenario 14-5
A study sponsored by the Food Consumer Safety Board found that consumption of irradiated tomatoes increased the health of laboratory rats. As a result of national press coverage of the report, the demand for irradiated tomatoes increased dramatically. Organic farmers were able to switch from organic production of tomatoes to irradiated production with no additional cost. Assume that the tomato market satisfies all of the assumptions of perfect competition.
-Refer to Scenario 14-5. If the increased production of irradiated tomatoes caused a rise in the marginal transportation costs of moving irradiated tomatoes to market, the

Free
(Multiple Choice)
4.8/5  (80)
(80) Correct Answer: Verified
D
Firms that operate in perfectly competitive markets try to
Free
(Multiple Choice)
4.8/5 (72)
(72) Correct Answer:Verified
VerifiedB
When new firms have an incentive to enter a competitive market, their entry will
Free
(Multiple Choice)
4.9/5 (91)
(91) Correct Answer:Verified
VerifiedB
Table 14-4
The table represents a demand curve faced by a firm in a competitive market.  -Refer to Table 14-4. For this firm, the price is
 (Multiple Choice)
4.7/5 (78)
(78) Mr. Rogers sells colored pencils. The colored-pencil industry is competitive. Mr. Rogers hires a business consultant to analyze his company's financial records. The consultant recommends that Mr. Rogers increase his production. The consultant must have concluded that Mr. Roger's
(Multiple Choice)
4.8/5 (61)
(61) Table 14-7
Suppose that a firm in a competitive market faces the following revenues and costs: 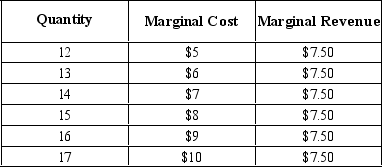 -Refer to Table 14-7. If the firm is currently producing 14 units, what would you advise the owners?
 (Multiple Choice)
5.0/5 (94)
(94) A profit-maximizing firm will shut down in the short run when
(Multiple Choice)
4.8/5 (74)
(74) Table 14-5
The table represents a demand curve faced by a firm in a competitive market.  -Refer to Table 14-5. For this firm, the average revenue when 14 units are produced and sold is
(Multiple Choice)
4.9/5 (89)
(89) For a firm, marginal revenue minus marginal cost is equal to
(Multiple Choice)
4.9/5 (86)
(86) Suppose a firm in a competitive market produces and sells 150 units of output and earns $1,800 in total revenue from the sales. If the firm increases its output to 200 units, the average revenue of the 200th unit will be
(Multiple Choice)
4.7/5 (73)
(73) Mrs. Smith operates a business in a competitive market. The current market price is $8.50. At her profit- maximizing level of production, the average variable cost is $8.00, and the average total cost is $8.25. Mrs. Smith should
(Multiple Choice)
4.9/5 (80)
(80) Table 14-6
The following table presents cost and revenue information for a firm operating in a competitive industry.  -Refer to Table 14-6. What is the marginal revenue from selling the 3rd unit?
 (Multiple Choice)
4.9/5 (70)
(70) Which of the following statements best reflects a price-taking firm?
(Multiple Choice)
4.9/5 (71)
(71) Table 14-9
Suppose that a firm in a competitive market faces the following revenues and costs:  -Refer to Table 14-9. If the firm's marginal cost is $5, it should
 (Multiple Choice)
4.7/5 (71)
(71) A dairy farmer must be able to calculate sunk costs in order to determine how much revenue the farm receives for the typical gallon of milk.
(True/False)
5.0/5 (93)
(93) A corporation has been steadily losing money on one of its product lines, plastic flamingo lawn ornaments. The firm produces plastic flamingos in a factory that cost $20 million to build 10 years ago. The firm is now considering an offer to buy that factory for $15 million. Which of the following statements about the decision to sell or not to sell is correct?
(Multiple Choice)
4.8/5 (87)
(87) Table 14-15 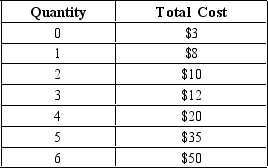 -Refer to Table 14-15. What is the lowest price at which this firm would operate in the short run?
 (Multiple Choice)
4.9/5 (86)
(86) In the long run, when price is greater than average total cost, some firms in a competitive market will choose to enter the market.
(True/False)
4.8/5 (89)
(89) A firm is currently producing 100 units of output per day. The manager reports to the owner that producing the 100th unit costs the firm $5. The firm can sell the 100th unit for $4.75. The firm should continue to produce 100 units in order to maximize its profits (or minimize its losses).
(True/False)
5.0/5 (85)
(85) Suppose a firm operates in the short run at a price above its average total cost of production. In the long run the firm should expect
(Multiple Choice)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)