



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics439 Questions
Exam 2: Thinking Like an Economist617 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand697 Questions
Exam 5: Elasticity and Its Application594 Questions
Exam 6: Supply, Demand, and Government Policies645 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets549 Questions
Exam 8: Application: the Costs of Taxation513 Questions
Exam 9: Application: International Trade492 Questions
Exam 10: Externalities524 Questions
Exam 11: Public Goods and Common Resources433 Questions
Exam 12: The Design of the Tax System549 Questions
Exam 13: The Costs of Production420 Questions
Exam 14: Firms in Competitive Markets543 Questions
Exam 15: Monopoly637 Questions
Exam 16: Monopolistic Competition580 Questions
Exam 17: Oligopoly488 Questions
Exam 18: The Markets for the Factors of Production564 Questions
Exam 19: Earnings and Discrimination490 Questions
Exam 20: Income Inequality and Poverty455 Questions
Exam 21: The Theory of Consumer Choice431 Questions
Exam 22: Frontiers of Microeconomics440 Questions
Exam 23: Measuring a Nations Income520 Questions
Exam 24: Measuring the Cost of Living529 Questions
Exam 25: Production and Growth505 Questions
Exam 26: Saving, Investment, and the Financial System564 Questions
Exam 27: The Basic Tools of Finance500 Questions
Exam 28: Unemployment678 Questions
Exam 29: The Monetary System515 Questions
Exam 30: Money Growth and Inflation481 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts522 Questions
Exam 32: A Macroeconomic Theory of the Open Economy475 Questions
Exam 33: Aggregate Demand and Aggregate Supply562 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand508 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment491 Questions
Exam 36: Six Debates Over Macroeconomic Policy372 Questions
Select questions type


In the long run, a profit-maximizing firm will choose to exit a market when
(Multiple Choice)
4.9/5  (82)
(82) A miniature golf course is a good example of where fixed costs become relevant to the decision of when to open and when to close for the season.
(True/False)
4.9/5 (74)
(74) Jose's restaurant operates in a perfectly competitive market. At the point where marginal cost equals marginal revenue, ATC = $20, AVC = $15, and the price per unit is $10. In this situation,
(Multiple Choice)
4.8/5 (75)
(75) Table 14-6
The following table presents cost and revenue information for a firm operating in a competitive industry.  -Refer to Table 14-6. What is the total revenue from selling 4 units?
 (Multiple Choice)
4.7/5 (97)
(97) Figure 14-13
Suppose a firm in a competitive industry has the following cost curves:  -Refer to Figure 14-13. If the price is $6 in the short run, what will happen in the long run?
 (Multiple Choice)
4.9/5 (77)
(77) Figure 14-11 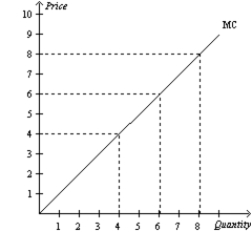 -Refer to Figure 14-11. The figure above is for a firm operating in a competitive industry. If there were eight identical firms in the industry, which of the following price-quantity combinations would be on the market supply curve?

-Refer to Figure 14-11. The figure above is for a firm operating in a competitive industry. If there were eight identical firms in the industry, which of the following price-quantity combinations would be on the market supply curve? (Multiple Choice)
4.9/5 (96)
(96) In the long-run equilibrium of a market with free entry and exit, marginal firms are operating
(Multiple Choice)
4.8/5 (61)
(61) Figure 14-5
Suppose a firm operating in a competitive market has the following cost curves:  -Refer to Figure 14-5. In the short run,if the market price is higher than P4 but less than P6, individual firms in a competitive industry will earn
 (Multiple Choice)
4.8/5 (85)
(85) Table 14-3
The table represents a demand curve faced by a firm in a competitive market.  -Refer to Table 14-3. For this firm, the marginal revenue is
(Multiple Choice)
4.9/5 (89)
(89) If a competitive firm is selling 500 units of its product at a price of $8 per unit and earning a positive profit, then
(Multiple Choice)
4.9/5 (75)
(75) Table 14-11
Suppose that a firm in a competitive market faces the following prices and costs:  -Refer to Table 14-11. The marginal revenue from producing the 3rd unit equals
 (Multiple Choice)
4.8/5 (80)
(80) The firm will make the most profits if it produces the quantity of output at which
(Multiple Choice)
4.8/5 (86)
(86) A long-run supply curve is flatter than a short-run supply curve because
(Multiple Choice)
4.9/5 (79)
(79) Mrs. Smith is operating a firm in a competitive market. The market price is $6.50. At her profit-maximizing level of output, her average total cost of production is $7.00, and her average variable cost of production is $6.00. Which of the following statements about Mrs. Smith's firm is correct?
(Multiple Choice)
4.7/5 (75)
(75) If some resources used in the production of a good are only available in limited quantities, then the long run market supply curve will be perfectly elastic.
(True/False)
4.9/5 (63)
(63) Table 14-12
Bill's Birdhouses  -Refer to Table 14-12. What is the marginal revenue from selling the 5th unit?
 (Multiple Choice)
4.9/5 (74)
(74) Land of Many Lakes (LML) sells butter to a broker in Albert Lea, Minnesota. Because the market for butter is generally considered to be competitive, LML does not choose the
(Multiple Choice)
4.8/5 (78)
(78) Figure 14-14  -Refer to Figure 14-14. If the market starts in equilibrium at point Z in panel (b), a decrease in demand will ultimately lead to
 (Multiple Choice)
4.8/5 (80)
(80) Which of the following represents the firm's short-run condition for shutting down?
(Multiple Choice)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)