



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics439 Questions
Exam 2: Thinking Like an Economist617 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand697 Questions
Exam 5: Elasticity and Its Application594 Questions
Exam 6: Supply, Demand, and Government Policies645 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets549 Questions
Exam 8: Application: the Costs of Taxation513 Questions
Exam 9: Application: International Trade492 Questions
Exam 10: Externalities524 Questions
Exam 11: Public Goods and Common Resources433 Questions
Exam 12: The Design of the Tax System549 Questions
Exam 13: The Costs of Production420 Questions
Exam 14: Firms in Competitive Markets543 Questions
Exam 15: Monopoly637 Questions
Exam 16: Monopolistic Competition580 Questions
Exam 17: Oligopoly488 Questions
Exam 18: The Markets for the Factors of Production564 Questions
Exam 19: Earnings and Discrimination490 Questions
Exam 20: Income Inequality and Poverty455 Questions
Exam 21: The Theory of Consumer Choice431 Questions
Exam 22: Frontiers of Microeconomics440 Questions
Exam 23: Measuring a Nations Income520 Questions
Exam 24: Measuring the Cost of Living529 Questions
Exam 25: Production and Growth505 Questions
Exam 26: Saving, Investment, and the Financial System564 Questions
Exam 27: The Basic Tools of Finance500 Questions
Exam 28: Unemployment678 Questions
Exam 29: The Monetary System515 Questions
Exam 30: Money Growth and Inflation481 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts522 Questions
Exam 32: A Macroeconomic Theory of the Open Economy475 Questions
Exam 33: Aggregate Demand and Aggregate Supply562 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand508 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment491 Questions
Exam 36: Six Debates Over Macroeconomic Policy372 Questions
Select questions type


Which of the following is not a characteristic of a perfectly competitive market?
(Multiple Choice)
5.0/5  (81)
(81) In the short run, a market consists of 100 identical firms. The market price is $6, and the total cost to each firm of producing various levels of output is given in the table below. What will total quantity supplied be in the market? 
(Multiple Choice)
4.8/5 (76)
(76) Figure 14-13
Suppose a firm in a competitive industry has the following cost curves:  -Refer to Figure 14-13. If the price is $2 in the short run, what will happen in the long run?
 (Multiple Choice)
4.9/5 (71)
(71) Table 14-8
Suppose that a firm in a competitive market faces the following revenues and costs:  -Refer to Table 14-8. In order to maximize profits, the firm will produce
 (Multiple Choice)
4.7/5 (73)
(73) In the short run, there are 500 identical firms in a competitive market. The firms do not use any resources that are available in limited quantities, and each of them has the following cost structure: 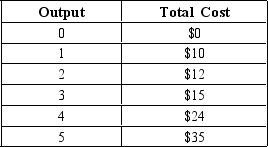 The long-run supply curve for this market is
 (Multiple Choice)
4.9/5 (78)
(78) Figure 14-7  -Refer to Figure 14-7. Let Q represent the quantity of output and suppose the price of the good is $125. Then marginal revenue is
 (Multiple Choice)
4.9/5 (78)
(78) A firm in a competitive market has the following cost structure: 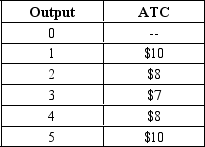 If the firm's fixed cost of production is $3, and the market price is $10, how many units should the firm produce to maximize profit?
 (Multiple Choice)
4.9/5 (76)
(76) A firm that has little ability to influence market prices operates in a
(Multiple Choice)
4.9/5 (77)
(77) One of the defining characteristics of a perfectly competitive market is
(Multiple Choice)
4.9/5 (81)
(81) In a competitive market, no single producer can influence the market price because
(Multiple Choice)
4.8/5 (86)
(86) A firm will shut down in the short run if revenue is not sufficient to cover all of its fixed costs of production.
(True/False)
4.8/5 (84)
(84) Table 14-12
Bill's Birdhouses  -Refer to Table 14-12. At what quantity does Bill maximize profits?
 (Multiple Choice)
4.7/5 (73)
(73) A profit-maximizing firm in a competitive market is able to sell its product for $7. At its current level of output, the firm's average total cost is $10. The firm's marginal cost curve crosses its marginal revenue curve at an output level of 9 units. The firm experiences a
(Multiple Choice)
4.8/5 (76)
(76) When a competitive firm doubles the quantity of output it sells, its
(Multiple Choice)
4.9/5 (85)
(85) A firm operating in a perfectly competitive industry will continue to operate if it earns zero economic profits because it is likely to be earning positive accounting profits.
(True/False)
4.9/5 (74)
(74) Suppose that a firm operating in perfectly competitive market sells 300 units of output at a price of $3 each. Which of the following statements is correct?
(Multiple Choice)
5.0/5 (73)
(73) Scenario 14-2
Assume a certain firm is producing Q = 1,000 units of output. At Q = 1,000, the firm's marginal cost equals $20 and its average total cost equals $25. The firm sells its output for $30 per unit.
-Refer to Scenario 14-2. At Q = 1,000, the firm's profits equal
(Multiple Choice)
4.8/5 (72)
(72) Table 14-12
Bill's Birdhouses
-Refer to Table 14-12. What is the average revenue when 4 units are sold?
-Refer to Table 14-12. What is the average revenue when 4 units are sold? (Multiple Choice)
4.8/5 (83)
(83) Table 14-10
Suppose that a firm in a competitive market faces the following revenues and costs:  -Refer to Table 14-10. The marginal cost of producing the 4th unit is
 (Multiple Choice)
5.0/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)