



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


Table 11-6
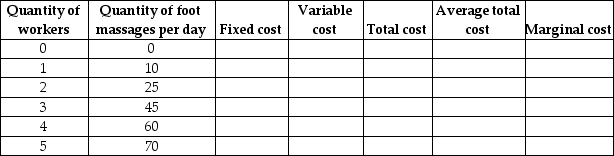 -Refer to Table 11-6. Alicia Gregory owns a foot massage business. She leases 4 computer-controlled massage booths, for which she pays $125 per day. She cannot increase the number machines she leases without giving the manufacturer 3 months' notice. She can hire as many workers as she wants at a cost of $75 per day per worker. These are the only two inputs she uses in her business. Use this information to fill in the columns in the above table.
 (Essay)
4.8/5  (84)
(84) If marginal cost is above the average variable cost, then average variable cost is decreasing.
(True/False)
5.0/5 (73)
(73) After Suzie, owner of Suzie's Sweet Shop, hires her 8th worker the average product of labor declines. Which of the following statements must be true?
(Multiple Choice)
4.9/5 (79)
(79) Suppose the total cost of producing 40,000 flash drives is $120,000, and the fixed cost is $30,000.
a. What is the variable cost?
b. When output is 40,000, what are the average variable cost and the average fixed cost?
c. Assuming the cost curves have the usual shape, is the dollar difference between the average total cost and the average variable cost greater when the output is 40,000 flash drives or when the output is 60,000 flash drives? Explain.
(Essay)
4.8/5 (79)
(79) Table 11-2
 Table 11-2 summarizes production at the Crunchy Apple Orchard for the month of April 2005.
-Refer to Table 11-2. What is the average product of labor when the orchard employs 5 workers?
Table 11-2 summarizes production at the Crunchy Apple Orchard for the month of April 2005.
-Refer to Table 11-2. What is the average product of labor when the orchard employs 5 workers? (Multiple Choice)
4.8/5 (70)
(70) The slope of an isocost line ________ and equals the negative of ________.
(Multiple Choice)
4.8/5 (95)
(95) Figure 11-2  -Refer to Figure 11-2. Diminishing returns to labor set in
 (Multiple Choice)
4.8/5 (84)
(84) Table 11-7
 Table 11-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-7. What is the average variable cost per unit of production when the firm produces 90 lanterns?
Table 11-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-7. What is the average variable cost per unit of production when the firm produces 90 lanterns? (Multiple Choice)
4.9/5 (83)
(83) The rate at which a firm is able to substitute one input for another while keeping the level of output constant is called the
(Multiple Choice)
5.0/5 (81)
(81) Economies of scale exist as a firm increases its size in the long run because of all of the following except
(Multiple Choice)
4.9/5 (91)
(91) An isoquant is a curve that shows all the combinations of two inputs that will produce the same level of output.
(True/False)
4.8/5 (66)
(66) The change in a firm's total cost from producing one more unit of a good or service is
(Multiple Choice)
4.9/5 (86)
(86) Table 11-8
 Elegant Settings manufactures stainless steel cutlery. Table 11-8 shows the company's cost data.
-Which of the following statements explains the difference between diminishing returns and diseconomies of scale?
Elegant Settings manufactures stainless steel cutlery. Table 11-8 shows the company's cost data.
-Which of the following statements explains the difference between diminishing returns and diseconomies of scale? (Multiple Choice)
4.8/5 (81)
(81) Figure 11-3  Fancy Footwear manufactures shoes. Figure 11-3 shows Fancy Footwear's marginal product of labor and average product of labor curves in the short run.
-Refer to Figure 11-3. For what quantity of labor does production display diminishing returns?
Fancy Footwear manufactures shoes. Figure 11-3 shows Fancy Footwear's marginal product of labor and average product of labor curves in the short run.
-Refer to Figure 11-3. For what quantity of labor does production display diminishing returns? (Multiple Choice)
4.9/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)