



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


Figure 11-3  Fancy Footwear manufactures shoes. Figure 11-3 shows Fancy Footwear's marginal product of labor and average product of labor curves in the short run.
-Refer to Figure 11-3. Which of the following statements correctly describes the curves in the figure?
Fancy Footwear manufactures shoes. Figure 11-3 shows Fancy Footwear's marginal product of labor and average product of labor curves in the short run.
-Refer to Figure 11-3. Which of the following statements correctly describes the curves in the figure? (Multiple Choice)
4.9/5  (81)
(81) The processes a firm uses to turn inputs into outputs of goods and services is called
(Multiple Choice)
4.8/5 (81)
(81) If the total cost of producing 20 units of output is $1,000 and the average variable cost is $35, what is the firm's average fixed cost at that level of output?
(Multiple Choice)
4.8/5 (83)
(83) If the firm is producing no output in the short run, then its total costs are zero.
(True/False)
4.9/5 (71)
(71) Is it possible for average total cost to be decreasing over a range of output where marginal cost is increasing? Briefly explain.
(Essay)
4.9/5 (63)
(63) The slope of an isocost line determines the marginal rate of substitution.
(True/False)
4.9/5 (85)
(85) If, after hiring the 6th worker, a firm's output falls, then the marginal product of the 6th worker is negative.
(True/False)
4.9/5 (81)
(81) Figure 11-8 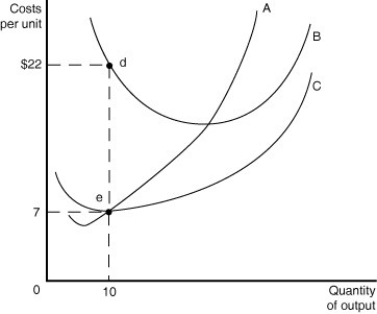 -Refer to Figure 11-8 above to answer the following questions.
a. Identify the curves in the diagram.
A ________________________________________
B ________________________________________
C ________________________________________
b. What is the numerical value of fixed cost when the quantity of output = 10?
c. What is the numerical value of variable cost when the quantity of output = 10?
d. What is the numerical value of total cost when the quantity of output = 10?
e. What is the numerical value of average fixed cost when the quantity of output = 10?
f. What is the numerical value of average total cost when the quantity of output = 10?
g. On the graph identify the area that represents the total variable cost of production when the quantity of output = 10.
h. On the graph identify the area that represents the fixed cost of production when the quantity of output = 10.
-Refer to Figure 11-8 above to answer the following questions.
a. Identify the curves in the diagram.
A ________________________________________
B ________________________________________
C ________________________________________
b. What is the numerical value of fixed cost when the quantity of output = 10?
c. What is the numerical value of variable cost when the quantity of output = 10?
d. What is the numerical value of total cost when the quantity of output = 10?
e. What is the numerical value of average fixed cost when the quantity of output = 10?
f. What is the numerical value of average total cost when the quantity of output = 10?
g. On the graph identify the area that represents the total variable cost of production when the quantity of output = 10.
h. On the graph identify the area that represents the fixed cost of production when the quantity of output = 10. (Essay)
4.8/5 (75)
(75) Figure 11-18 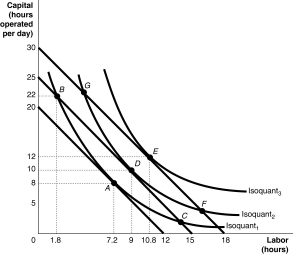 -Refer to Figure 11-18. A curve that connects points a, d and e is called
 (Multiple Choice)
4.7/5 (87)
(87) Article Summary
Due to falling sales and lower profit margins, clothing retailer Aeropostale announced it would be closing more stores than originally planned. In August, the company announced it would be closing between 30 and 40 locations in 2013, up from the previously announced 15 to 20. Compared to the previous year, net sales fell 6 percent and the company reported a loss of $33.7 million for the second quarter of 2013, and the trend was expected to continue into the third quarter. Explaining the downturn, Aeropostale chief executive Thomas P. Johnson stated "Our business was pressured by a challenging teen retail environment with weak traffic trends and high levels of promotional activity."
Source: Andrew Klips, "Aeropostale Losses Accelerate, Closing More Stores," equities.com, August 23, 2013.
-Refer to the Article Summary. Use a graph to illustrate average total cost curves for Aeropostale before and after closing the 30 to 40 stores. Assume that after closing the stores, Aeropostale will be producing at minimum average total cost.
(Essay)
4.8/5 (88)
(88) Table 11-1
 Table 11-1 shows the technology of production at the Matsuko's Mushroom Farm for the month of May.
-Refer to Table 11-1. What is the marginal product of the 4th worker?
Table 11-1 shows the technology of production at the Matsuko's Mushroom Farm for the month of May.
-Refer to Table 11-1. What is the marginal product of the 4th worker? (Multiple Choice)
4.8/5 (81)
(81) A firm's cost of production is determined by all of the following except
(Multiple Choice)
4.8/5 (71)
(71) A downward-sloping marginal product of labor curve demonstrates the law of diminishing marginal returns.
(True/False)
4.8/5 (75)
(75) Describe how Wal-Mart has used positive technological change to manage its inventory.
(Essay)
4.9/5 (73)
(73) Which of the following are implicit costs for a typical firm?
(Multiple Choice)
4.9/5 (85)
(85) Improvements in inventory control represent a positive technological change because they allow firms to produce the same output with fewer inputs. In recent years, many firms have adopted an inventory system in which firms accept shipments from suppliers as close as possible to the time they will be needed. Wal-Mart has been a pioneer in using inventory control systems to this in its stores. This type of inventory system is called a ________ inventory system.
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)