



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


Use the general relationship between marginal and average values to explain why a marginal cost curve must intersect an average total cost curve and an average variable cost curve at their minimum points.
(Essay)
4.9/5  (80)
(80) Table 11-8
 Elegant Settings manufactures stainless steel cutlery. Table 11-8 shows the company's cost data.
-Refer to Table 11-8. Elegant Settings experiences
Elegant Settings manufactures stainless steel cutlery. Table 11-8 shows the company's cost data.
-Refer to Table 11-8. Elegant Settings experiences (Multiple Choice)
4.7/5 (75)
(75) Which of the following statements best describes the economic short run?
(Multiple Choice)
4.9/5 (77)
(77) If, when a firm doubles all its inputs, its average cost of production increases, then production displays
(Multiple Choice)
4.9/5 (73)
(73) Which of the following would be categorized as an opportunity cost? a. not being able to spend your $10,000 savings if you sink the money in your business
B. the cost of purchasing supplies for your house-cleaning business
C. the cost of purchasing auto insurance for your dry-cleaning delivery business
(Multiple Choice)
4.9/5 (78)
(78) Figure 11-13  -Refer to Figure 11-13. The lines shown in the diagram are isocost lines. Which of the following shows a decrease in the price of capital while the price of labor remains unchanged?
 (Multiple Choice)
4.9/5 (80)
(80) Figure 11-2  -Refer to Figure 11-2. Short-run output is maximized at
 (Multiple Choice)
4.8/5 (89)
(89) The change in a firm's total cost from producing one more unit of a good or service is the firm's
(Multiple Choice)
4.9/5 (73)
(73) If production displays diseconomies of scale, the long-run average cost curve is
(Multiple Choice)
4.9/5 (87)
(87) In the short run, if average product is at its maximum, then average variable cost is at its minimum.
(True/False)
4.7/5 (84)
(84) Figure 11-7  Figure 11-7 shows the cost structure for a firm.
-Refer to Figure 11-7. When output level is 100, what is the total cost of production?
Figure 11-7 shows the cost structure for a firm.
-Refer to Figure 11-7. When output level is 100, what is the total cost of production? (Multiple Choice)
4.8/5 (73)
(73) If a firm experiences positive technological change, it is able to produce more output using the same inputs.
(True/False)
4.7/5 (77)
(77) Figure 11-11  Figure 11-11 illustrates the long-run average cost curve for a firm that produces picture frames. The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 11-11. Constant returns to scale
Figure 11-11 illustrates the long-run average cost curve for a firm that produces picture frames. The graph also includes short-run average cost curves for three firm sizes: ATCa, ATCb and ATCc.
-Refer to Figure 11-11. Constant returns to scale (Multiple Choice)
4.9/5 (63)
(63) If, when a firm doubles all its inputs, its average cost of production decreases, then production displays
(Multiple Choice)
4.9/5 (71)
(71) If the long-run average total cost curve is downward sloping, then the firm is experiencing decreasing returns to scale.
(True/False)
4.9/5 (81)
(81) The process a firm uses to turn inputs into outputs of goods and services is called technology.
(True/False)
4.8/5 (77)
(77) Figure 11-6 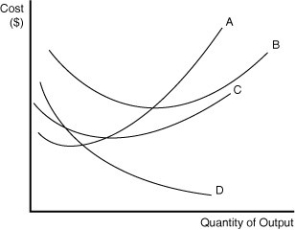 Figure 11-6 contains information about the short-run cost structure of a firm.
-Refer to Figure 11-6. In the figure above, which letter represents the average total cost curve?
Figure 11-6 contains information about the short-run cost structure of a firm.
-Refer to Figure 11-6. In the figure above, which letter represents the average total cost curve? (Multiple Choice)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)