



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models444 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System498 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply475 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes419 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods266 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply295 Questions
Exam 7: The Economics of Health Care334 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance278 Questions
Exam 9: Comparative Advantage and the Gains From International Trade379 Questions
Exam 10: Consumer Choice and Behavioral Economics302 Questions
Exam 11: Technology, Production, and Costs330 Questions
Exam 12: Firms in Perfectly Competitive Markets298 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting276 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets262 Questions
Exam 15: Monopoly and Antitrust Policy271 Questions
Exam 16: Pricing Strategy263 Questions
Exam 17: The Markets for Labor and Other Factors of Production286 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: GDP: Measuring Total Production and Income266 Questions
Exam 20: Unemployment and Inflation292 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles257 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies268 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run306 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis284 Questions
Exam 25: Money, Banks, and the Federal Reserve System280 Questions
Exam 26: Monetary Policy277 Questions
Exam 27: Fiscal Policy303 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System262 Questions
Select questions type


Are the costs of utilities always fixed, always variable, or can they be both? Briefly explain.
(Essay)
4.7/5  (84)
(84) Figure 11-7  Figure 11-7 shows the cost structure for a firm.
-Refer to Figure 11-7. When the output level is 100 units, average fixed cost is
Figure 11-7 shows the cost structure for a firm.
-Refer to Figure 11-7. When the output level is 100 units, average fixed cost is (Multiple Choice)
5.0/5 (76)
(76) Table 11-3
 -Refer to Table 11-3. The table above refers to the relationship between the quantity of workers employed and the number of cardboard boxes produced per day by Manny's House of Boxes. The capital used to produce the boxes is fixed. The highest value of the average product is labor is ________ when Manny hires ________ workers.
 (Multiple Choice)
4.8/5 (75)
(75) Jennifer Borts moves her office from the premises she rents at a local mall to her home. As a result of this move
(Multiple Choice)
4.8/5 (76)
(76) Which of the following can a firm do in the long run but not in the short run?
(Multiple Choice)
4.8/5 (73)
(73) The president of Toyota's Georgetown plant was quoted as saying, "Demand for high volumes saps your energy. Over a period of time, it eroded our focus [and] thinned out the expertise and knowledge we painstakingly built up over the years." This quote suggests that
(Multiple Choice)
4.9/5 (95)
(95) Which of the following costs will not change as output changes?
(Multiple Choice)
4.9/5 (70)
(70) Figure 11-13  -Refer to Figure 11-13. The lines shown in the diagram are isocost lines. Which of the following shows an increase in the firm's total cost while the price of labor and capital remain unchanged?
 (Multiple Choice)
4.9/5 (71)
(71) As output increases, the distance between average total cost and average variable cost increases.
(True/False)
4.8/5 (61)
(61) Joan Jillson owns a coffee shop. Assume that the marginal product of the labor Joan employs (MPL) equals 500 cups per week and the marginal product of her shop's capital (MPK) equals 1,000. Assume also that the wage (w) Joan pays her workers equals $250 per week and the rental price (r) of her capital - her coffee machines - equals $500 per week. Which of the following correctly analyzes whether Joan is minimizing her costs?
(Multiple Choice)
4.9/5 (88)
(88) Table 11-7
 Table 11-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-7. What is the marginal cost per unit of production when the firm produces 100 lanterns?
Table 11-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-7. What is the marginal cost per unit of production when the firm produces 100 lanterns? (Multiple Choice)
4.7/5 (83)
(83) Figure 11-10 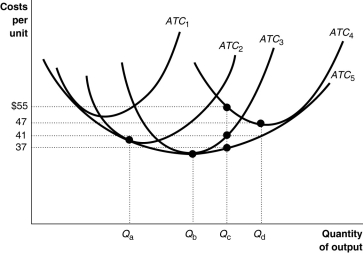 -Refer to Figure 11-10. Suppose for the past 8 years the firm has been producing Qd units per period using plant size ATC4. Now, following a permanent change in demand, it plans to cut production to Qc units. What will happen to its average cost of production?
 (Multiple Choice)
4.8/5 (89)
(89) Table 11-7
Table 11-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-7. What is the average total cost of production when the firm produces 120 lanterns?
Table 11-7 shows cost data for Lotus Lanterns, a producer of whimsical night lights.
-Refer to Table 11-7. What is the average total cost of production when the firm produces 120 lanterns? (Multiple Choice)
5.0/5 (75)
(75) Over the past twenty years, the number of small family farms has fallen significantly and in their place there are fewer, but larger, farms owned by corporations. Which of the following best explains this trend?
(Multiple Choice)
4.8/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)