



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Straight debt issued in an S corporation year will not be treated as a second class of stock and will not disqualify an S election.
(True/False)
5.0/5  (74)
(74) Explain how family members are treated for purposes of the number of shareholders requirement concerning S corporation status.
(Essay)
4.8/5 (77)
(77) Which item does not appear in an S corporation's nonseparately computed income?
(Multiple Choice)
4.7/5 (81)
(81) Depletion in excess of basis in property causes a(n) ____________________ adjustment to an S shareholder's basis.
or
(Short Answer)
4.7/5 (74)
(74) Separately stated items are listed on Schedule _________________________ of the Form 1120S.
(Short Answer)
4.8/5 (79)
(79) Post-termination distributions by a former S corporation that are charged against ____________________ do not get tax-free treatment.
(Short Answer)
5.0/5 (86)
(86) During 2011, Oxen Corporation incurs the following transactions.  Oxen maintains a valid S election and does not distribute any assets (cash or property) to its sole shareholder, Megan. As a result, Megan must recognize:
 (Multiple Choice)
4.9/5 (77)
(77) Compensation for services rendered to an S corporation is subject to FICA taxes.
(True/False)
5.0/5 (89)
(89) You are given the following facts about a one-shareholder S corporation, and you are asked to prepare the shareholder's ending stock basis. 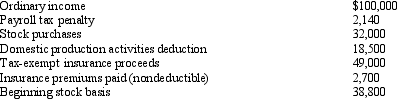
(Multiple Choice)
4.9/5 (73)
(73) All tax preference items flow through the S corporation, to be included in the shareholders' AMT calculations.
(True/False)
4.8/5 (84)
(84) Distributions of which assets during an S corporation's post-termination period receive favorable income tax treatment?
(Multiple Choice)
4.8/5 (84)
(84) An item that appears in the "Other Adjustments Account" affects stock basis, but not AAA, such as tax-exempt life insurance proceeds.
(True/False)
4.8/5 (93)
(93) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)