



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


A(n) ____________________ alien cannot own stock in an S corporation.
(Short Answer)
4.7/5  (84)
(84) An S corporation can take advantage of the dividends received deduction.
(True/False)
4.9/5 (82)
(82) Pepper, Inc., an S corporation in Norfolk, Virginia, has revenues of $400,000, taxable interest of $380,000, operating expenses of $250,000, and deductions attributable to the interest income of $140,000. What is Pepper's passive income penalty tax payable, if any?
(Multiple Choice)
4.7/5 (87)
(87) A cash basis calendar year C corporation in Athens, Georgia, has $100,000 of accounts receivable on the date of its conversion to an S corporation on February 14. By the end of the year, $70,000 of these receivables are collected. Calculate any built-in gains tax, assuming that there is sufficient taxable income.
(Multiple Choice)
4.7/5 (73)
(73) Yates Corporation elects S status, effective for calendar year 2011. Yates' only asset has a basis of $50,200 and a fair market value of $110,400 as of January 1, 2011. The asset is sold at the end of 2011 for $130,800. What amount must Mark Farris, a 60% owner and subject to a 15% income tax rate, pay, if any?
(Multiple Choice)
4.9/5 (82)
(82) Any excess of S corporation losses or deductions over the shareholder's combined stock and debt basis is suspended until there is a subsequent stock or debt basis.
(True/False)
4.9/5 (71)
(71) An S corporation is limited to ____________________ (how many?) shareholders.
(Short Answer)
5.0/5 (74)
(74) Match the term with the proper response. There may be more than one responses for each term.
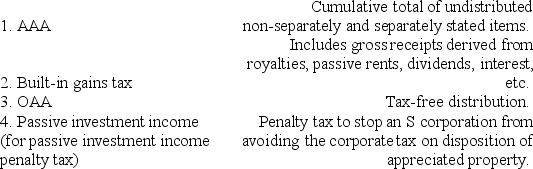
(Essay)
4.8/5 (77)
(77) Which could constitute a second class of stock under the S corporation rules?
(Multiple Choice)
5.0/5 (88)
(88) Beginning in 2011, the AAA of Ewing, Inc., an S corporation, has a balance of $725,000. During the year, the following items occur. 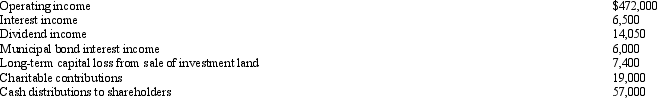 Ewing's ending AAA balance is:
 (Multiple Choice)
4.9/5 (82)
(82) An S corporation may have ____________________ class(es) of stock.
(Short Answer)
4.9/5 (79)
(79) Explain how the domestic production activities deduction is used for an S corporation.
(Essay)
4.9/5 (77)
(77) An S corporation must own ____________________% of a subsidiary's stock in order to elect to treat the subsidiary as a QSSS.
(Short Answer)
4.9/5 (86)
(86) An S corporation in Lawrence, Kansas has a recognized built-in gain of $110,000 and taxable income of $98,000. The company has an $8,000 NOL carryforward from a C corporation year, and a $7,000 business credit carryforward from a C corporation year. The built-in gains tax liability is:
(Multiple Choice)
4.8/5 (76)
(76) S corporation status avoids the ____________________ taxation and ____________________ limitations inherent in the regular corporate form.
or
(Short Answer)
4.8/5 (97)
(97) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)