



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


The LIFO recapture tax is a variation of the passive investment income penalty tax.
(True/False)
4.7/5  (64)
(64) Which, if any, of the following is not an eligible shareholder of an S corporation?
(Multiple Choice)
4.8/5 (85)
(85) Which transaction affects the Other Adjustments Account on an S corporation's Schedule M-2?
(Multiple Choice)
4.8/5 (88)
(88) Ryan is the sole shareholder of Sweetwater Apartments, an S corporation in Sour Lake, Texas. At a time when his stock basis is $10,000, the corporation distributes appreciated property worth $100,000 (basis of $10,000). There is no built-in gain. Ryan's taxable gain is:
(Multiple Choice)
5.0/5 (79)
(79) An S shareholder's basis is increased by stock purchases and capital contributions.
(True/False)
4.9/5 (83)
(83) A voluntary revocation of an S election requires only a consent of shareholders owning a majority of shares on the day that the revocation is made.
(True/False)
4.8/5 (86)
(86) The § 1374 tax is a corporate-level tax on any built-in gain recognized in 2011 when an S corporation disposes of an asset in a taxable disposition within 7 tax years after the date on which the S election took effect.
(True/False)
4.8/5 (85)
(85) How large must total assets on Schedule L be at the end of the year for an S corporation to be required to file Schedule M-3?
(Multiple Choice)
4.9/5 (68)
(68) Individuals Adam and Bonnie form an S corporation, with Adam contributing cash of $100,000 for a 50% interest and Bonnie contributing appreciated ordinary income property with an adjusted basis of $20,000 and a fair market value of $100,000.
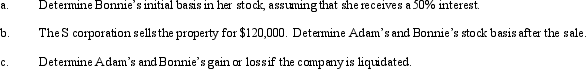
(Essay)
4.9/5 (73)
(73) Which, if any, of the following items has no effect on the stock basis of an S corporation shareholder?
(Multiple Choice)
4.8/5 (68)
(68) An S election allows shareholders to realize tax benefits from losses immediately.
(True/False)
5.0/5 (80)
(80) A widower and his spouse's estate are treated as one shareholder.
(True/False)
4.7/5 (86)
(86) When loss assets are distributed by an S corporation, a shareholder's basis is equal to the asset's fair market value.
(True/False)
4.9/5 (70)
(70) To make a valid S election, the entity must file a properly completed Form ____________________.
(Short Answer)
4.9/5 (95)
(95) A qualifying S election requires the consent of ____________________ of the corporate shareholders.
or
(Short Answer)
4.8/5 (74)
(74) Claude Bergeron sold 1,000 shares of Ditta, Inc., an S corporation located in Concord, North Carolina, for $12,000. He had owned the stock for three years and had a stock basis of $111,000 in the shares. Claude is single, and he is the original owner of the § 1244 stock shares. Calculate the appropriate tax treatment of any gain or loss.
(Multiple Choice)
4.9/5 (78)
(78) On January 2, 2010, David loans his S corporation $10,000, and by the end of 2010 David's stock basis is zero and the basis in his note has been reduced to $8,000. During 2011, the company's operating income is $10,000. The company also makes distributions to David of $11,000. Which statement is correct?
(Multiple Choice)
4.8/5 (79)
(79) A capital loss allocated to a shareholder always reduces the other adjustments account.
(True/False)
4.9/5 (73)
(73) An S corporation that has total assets of at least $5 million on Schedule L at the end of the tax year must file a Schedule M-3.
(True/False)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)