



 Chat with AI
Exam 12: S: Corporations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Depreciation recapture income is a ____________________ computed amount.
(Short Answer)
4.9/5  (79)
(79) An S corporation with substantial AEP has operating revenues of $410,000, taxable interest income of $390,000, operating expenses of $260,000, and deductions attributable to the interest of $150,000. The passive income penalty tax payable, if any, is:
(Multiple Choice)
4.8/5 (82)
(82) Which could constitute a second class of stock under the S corporation rules?
(Multiple Choice)
4.9/5 (78)
(78) Stock basis first is increased by income items, then ____________________ by distributions, and finally decreased by ____________________.
(Short Answer)
4.7/5 (71)
(71) If an S corporation shareholder's basis in a loan to the entity has been reduced, the shareholder recognizes gross income when the S corporation ____________________ the shareholder.
(Short Answer)
4.9/5 (86)
(86) An S shareholder's basis in his or her stock can be reduced below zero.
(True/False)
4.9/5 (78)
(78) Simmen, Inc., a calendar year S corporation, incurred the following items in 2011.
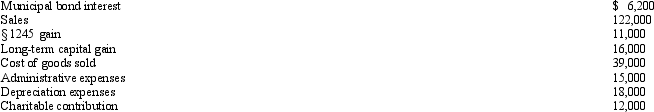 Calculate Simmen's nonseparately computed income.
 (Essay)
4.8/5 (92)
(92) Any distribution of cash or property by a corporation that does not exceed the balance of AAA with respect to the stock during a post-termination transition period of approximately one year is applied against and reduces the adjusted basis of the stock.
(True/False)
4.8/5 (88)
(88) There is no limit on the amount of passive investment income that an S corporation can receive during the year.
(True/False)
4.9/5 (77)
(77) An S corporation must possess the following characteristic(s):
(Multiple Choice)
4.8/5 (76)
(76) You are given the following facts about a 40% owner of an S corporation, and you are asked to prepare her ending stock basis. 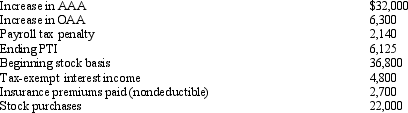
(Multiple Choice)
4.8/5 (79)
(79) Rents always are considered to be passive investment income in S status.
(True/False)
4.8/5 (64)
(64) Which, if any, of the following can be an eligible shareholder of an S corporation?
(Multiple Choice)
4.7/5 (79)
(79) An S corporation recognizes a gain on any distribution of ____________________ property.
(Short Answer)
4.8/5 (82)
(82) The Schedule M-3 is the same for a C corporation and an S corporation.
(True/False)
4.8/5 (84)
(84) S corporation income is taxed at the ____________________ level and not at the ____________________ level.
or
(Short Answer)
4.8/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)