



 Chat with AI
Exam 3: Supply and Demand

Exam 1: Thinking Like an Economist142 Questions
Exam 2: Comparative Advantage163 Questions
Exam 3: Supply and Demand181 Questions
Exam 4: Elasticity154 Questions
Exam 5: Demand144 Questions
Exam 6: Perfectly Competitive Supply159 Questions
Exam 7: Efficiency, Exchange, and the Invisible Hand in Action159 Questions
Exam 8: Monopoly, Oligopoly, and Monopolistic Competition147 Questions
Exam 9: Games and Strategic Behavior150 Questions
Exam 10: An Introduction to Behavioral Economics111 Questions
Exam 11: Externalities, Property Rights, and the Environment184 Questions
Exam 12: The Economics of Information127 Questions
Exam 13: Labor Markets, Poverty, and Income Distribution138 Questions
Exam 14: Public Goods and Tax Policy142 Questions
Exam 15: International Trade and Trade Policy164 Questions
Exam 16: Macroeconomics: The Birds Eye View of the Economy154 Questions
Exam 17: Measuring Economic Activity: GDP and Unemployment210 Questions
Exam 18: Measuring the Price Level and Inflation160 Questions
Exam 19: Economic Growth, Productivity, and Living Standards158 Questions
Exam 20: The Labor Market: Workers, Wages, and Unemployment121 Questions
Exam 21: Saving and Capital Formation144 Questions
Exam 22: Money Prices and the Federal Reserve107 Questions
Exam 23: Financial Markets and International Capital Flows104 Questions
Exam 24: Short-Term Economic Fluctuations: An Introduction124 Questions
Exam 25: Spending and Output in the Short Run146 Questions
Exam 26: Stabilizing the Economy: The Role of the Fed162 Questions
Exam 27: Aggregate Demand, Aggregate Supply, and Inflation159 Questions
Exam 28: Exchange Rates and the Open Economy157 Questions
Select questions type


Assume consumers eat either rice or pasta for dinner every night. If the price of rice increases, then one would expect to see:
(Multiple Choice)
4.9/5  (79)
(79) Assume both the demand for bagels and the supply of bagels increase. Which of the following outcomes is certain to occur?
(Multiple Choice)
4.9/5 (72)
(72) The Equilibrium Principle asserts that in a market equilibrium:
(Multiple Choice)
4.9/5 (87)
(87) Refer to the given table. The equilibrium price in this market is: Price Per Unit Columu A Units Per Year Colum B Units Per Year \ 20 100 40 \ 30 95 50 \ 40 80 60 \ 50 65 70 \ 60 50
(Multiple Choice)
4.8/5 (78)
(78) Refer to the accompanying figure. An increase in demand is represented by a shift from: 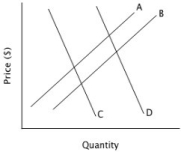
(Multiple Choice)
4.9/5 (83)
(83) If supply and demand both increase, the new equilibrium price will be ________ and the new equilibrium quantity will be ________.
(Multiple Choice)
4.7/5 (98)
(98) Refer to the accompanying figure, which shows the market for cups of coffee. Consider the original supply and the original demand curve. If the government imposes a price ceiling of $1.00 on a cup of coffee, then there would be: 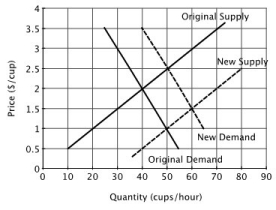
(Multiple Choice)
4.7/5 (61)
(61) Assume that Joe is willing to produce a hamburger for $1, and Mary is willing to pay $3 for a hamburger. Which of the following is true?
(Multiple Choice)
4.9/5 (72)
(72) Which of the following factors will lead to a decrease in the current supply of a good?
(Multiple Choice)
4.9/5 (82)
(82) Suppose we observe an increase in both the equilibrium price and quantity of bread. This is best explained by:
(Multiple Choice)
4.9/5 (71)
(71) In a free market, if the price of a good is below the equilibrium price, then;
(Multiple Choice)
4.9/5 (82)
(82) Refer to the given table. Suppose the columns in this table reflect demand and supply. At a price of $50: Price Per Unit Columu A Units Per Year Colum B Units Per Year \ 20 100 40 \ 30 95 50 \ 40 80 60 \ 50 65 70 \ 60 50
(Multiple Choice)
5.0/5 (69)
(69) Office workers and word processing programs are complements if:
(Multiple Choice)
4.8/5 (87)
(87) Jessica's marginal cost for producing a pitcher of lemonade is $0.25. Therefore, $0.25 is her:
(Multiple Choice)
4.7/5 (93)
(93) Suppose that Tom bought a bike from Helen for $195. If Helen's reservation price was $185, and Tom's reservation price was $215, the total economic surplus from this transaction was:
(Multiple Choice)
4.9/5 (61)
(61) If the supply curve and the demand curve both shift to the left, then the new equilibrium:
(Multiple Choice)
4.9/5 (82)
(82) The tendency of markets to automatically gravitate toward equilibrium is an application of the:
(Multiple Choice)
4.8/5 (74)
(74) Suppose that the equilibrium price of T-shirts increases and the equilibrium quantity of T-shirts decreases. This is best explained by:
(Multiple Choice)
4.9/5 (77)
(77) "As the price of personal computers continues to fall, demand increases." This headline is inaccurate because:
(Multiple Choice)
4.7/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)