



 Chat with AI
Exam 3: Market Demand and Supply

Exam 1: Introducing the Economic Way of Thinking85 Questions
Exam 2: Production Possibilities Opportunity Cost and Economic Growth107 Questions
Exam 3: Market Demand and Supply176 Questions
Exam 4: Markets in Action137 Questions
Exam 5: Price Elasticity of Demand and Supply151 Questions
Exam 6: Consumer Choice Theory96 Questions
Exam 7: Production Costs131 Questions
Exam 8: Perfect Competition126 Questions
Exam 9: Monopoly81 Questions
Exam 10: Monopolistic Competition and Oligopoly97 Questions
Exam 11: Labor Markets105 Questions
Exam 12: Income Distribution Poverty and Discrimination57 Questions
Exam 13: Antitrust and Regulation96 Questions
Exam 14: Environmental Economics47 Questions
Exam 15: Gross Domestic Product109 Questions
Exam 16: Business Cycles and Unemployment94 Questions
Exam 17: Inflation56 Questions
Exam 18: The Keynesian Model111 Questions
Exam 19: The Keynesian Model in Action105 Questions
Exam 20: Aggregate Demand and Supply94 Questions
Exam 21: Fiscal Policy108 Questions
Exam 22: The Public Sector55 Questions
Exam 23: Federal Deficits Surpluses and the National Debt42 Questions
Exam 24: Money and the Federal Reserve System75 Questions
Exam 25: Money Creation117 Questions
Exam 26: Monetary Policy106 Questions
Exam 27: The Phillips Curve and Expectations Theory59 Questions
Exam 28: International Trade and Finance127 Questions
Exam 29: Economies in Transition46 Questions
Exam 30: Growth and the Less Developed Countries55 Questions
Exam 31: Understanding Direct and Inverse Relationships between Variables172 Questions
Select questions type


Farmers can produce wheat and/or rice. What will happen in the wheat market if there is an increase in the price of rice?
(Multiple Choice)
5.0/5  (71)
(71) Exhibit 3-5 Supply for Tucker's Cola Data
Quantity supplied per week
(millions of gallons)
Price per
gallon
6
$3.00
5
2.50
4
2.00
3
1.50
2
1.00
1
.50
-Exhibit 3-5 shows the supply schedule for Tucker's Cola. Suppose there are four additional suppliers of cola in the market. When the price per gallon of cola is $1.50, the first supplier is willing to sell 10 million gallons, the second supplier is willing to sell 2 million gallons, the third supplier is willing to sell 5 million gallons, and the fourth supplier is willing to sell 0 gallons. The market quantity supplied of cola when the price is $1.50 is
| Quantity supplied per week | Price per |
| 6 | $3.00 |
| 5 | 2.50 |
| 4 | 2.00 |
| 3 | 1.50 |
| 2 | 1.00 |
| 1 | .50 |
(Multiple Choice)
5.0/5 (75)
(75) When firms advertise their products, they are attempting to:
(Multiple Choice)
5.0/5 (80)
(80) Assume that oranges and peaches can both be grown on the same type of land, a decrease in the price of peaches, other things being equal, will cause a(n):
(Multiple Choice)
4.9/5 (68)
(68) 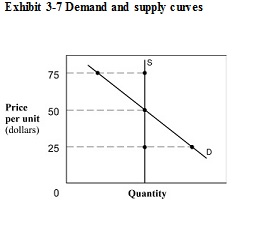
-In Exhibit 3-7, if price happened to currently be $75 in this market, a _______ would result, causing a __________ in price.
-In Exhibit 3-7, if price happened to currently be $75 in this market, a _______ would result, causing a __________ in price. (Multiple Choice)
4.9/5 (84)
(84) How will an increase in lumber prices influence the home construction market?
(Multiple Choice)
4.9/5 (83)
(83) Seller A has an upward-sloping supply curve and is willing to supply 400 units of a commodity at a price of $5 per unit. Seller A is now willing to supply 500 units at a price of $5 per unit. Evidently, seller A has experienced a(n):
(Multiple Choice)
5.0/5 (70)
(70) Interpret what an increase in demand and an increase in supply mean. Discuss the causes of an increase in demand and an increase in supply. How are increases in demand and supply expressed graphically?
(Essay)
4.8/5 (76)
(76) Which of the following must be true if good X is a normal good and income increases?
(Multiple Choice)
4.7/5 (88)
(88) Tasha decides that when homes in her neighborhood are selling for $150,000 she will not sell her home. When average prices rise to $175,000, she decides that she will put her home on the market. This is an example of:
(Multiple Choice)
4.9/5 (81)
(81) If there is a surplus in the oil market, then the price of oil will:
(Multiple Choice)
4.8/5 (73)
(73) When economists say the quantity demanded of a product has increased, they mean the:
(Multiple Choice)
4.8/5 (79)
(79) If the current price of a good is the same as that found at the intersection of the market demand and supply curves, then:
(Multiple Choice)
4.9/5 (103)
(103) The most important characteristic of the equilibrium price is that it:
(Multiple Choice)
5.0/5 (83)
(83) The "other things being equal" clause in the law of demand does allow which of the following factors to change?
(Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)