



 Chat with AI
Exam 2: Production Possibilities, Opportunity Cost, and Economic Growth

Exam 1: Introducing the Economic Way of Thinking176 Questions
Exam 2: Production Possibilities, Opportunity Cost, and Economic Growth200 Questions
Exam 3: Market Demand and Supply348 Questions
Exam 4: Markets in Action261 Questions
Exam 5: Gross Domestic Product223 Questions
Exam 6: Business Cycles and Unemployment194 Questions
Exam 7: Inflation126 Questions
Exam 8: The Keynesian Model235 Questions
Exam 9: The Keynesian Model in Action202 Questions
Exam 10: Aggregate Demand and Supply187 Questions
Exam 11: Fiscal Policy223 Questions
Exam 12: The Public Sector127 Questions
Exam 13: Federal Deficits, Surpluses, and the National Debt99 Questions
Exam 14: Money and the Federal Reserve System154 Questions
Exam 15: Money Creation243 Questions
Exam 16: Monetary Policy213 Questions
Exam 17: The Phillips Curve and Expectations Theory120 Questions
Exam 18: International Trade and Finance248 Questions
Exam 19: Economies in Transition104 Questions
Exam 20: Growth and the Less-Developed Countries117 Questions
Exam 21: Applying Graphs to Economics68 Questions
Exam 22: Consumer Surplus, Producer Surplus, and Market Efficiency68 Questions
Exam 23: the Self-Correcting Aggregate Demand and Supply Model83 Questions
Exam 24: Policy Disputes Using the Self-Correcting Aggregate Demand and Supply Model36 Questions
Select questions type


Which of the following is not true about a production possibilities curve? The curve:

Free
(Multiple Choice)
4.8/5  (99)
(99) Correct Answer: Verified
E
Exhibit 2-9 Production possibilities curve 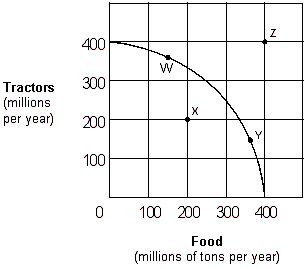 If the economy represented in Exhibit 2-9 is operating at Point W:
Free
(Multiple Choice)
4.9/5 (91)
(91) Correct Answer:Verified
VerifiedC
The opportunity cost of producing a good or service is the good or service that is foregone by choosing to produce another good with the same resources in a given period of time.
Free
(True/False)
4.8/5 (69)
(69) Correct Answer:Verified
VerifiedTrue
The ability of an economy to produce greater levels of output in the same period of time is called:
(Multiple Choice)
4.8/5 (80)
(80) In the context of the production possibilities curve, opportunity cost is measured in:
(Multiple Choice)
4.9/5 (79)
(79) Ralph wants to buy some milk and a box of cereal. If Ralph buys 2 quarts of milk at $1 per quart, the box of cereal costs 75 cents. If he buys 3 quarts of milk at $1 per quart, the box of cereal is free. For Ralph, the marginal cost of the third quart of milk is:
(Multiple Choice)
4.8/5 (79)
(79) If more of one good can be produced without producing less of another output, the economy must have been operating efficiently.
(True/False)
4.9/5 (81)
(81) Exhibit 2-10 Production possibilities curve data 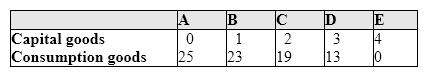 Suppose an economy is faced with the production possibilities table shown in Exhibit 2-10. The second unit of capital goods production will cost ____ units of consumption goods, and the third unit of capital goods production will cost ____ units of consumption goods.
 (Multiple Choice)
4.9/5 (84)
(84) Which of the following sayings best reflects the concept of opportunity cost?
(Multiple Choice)
4.7/5 (70)
(70) Exhibit 2-18 Production possibilities curves 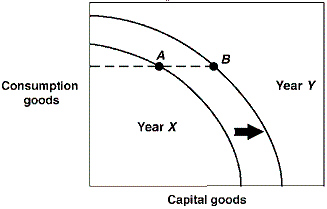 In Exhibit 2-18, a country is located at point A on its Year X production possibilities curve. In Year Y this same country is located at point B on its Year Y production possibilities curve. Which of the following could have brought about this outward shift in production possibilities curves?
 (Multiple Choice)
4.8/5 (81)
(81) Just before class, Jim tells Stuart, "Stuart, you shouldn't skip class today because you have paid tuition to enroll in the class." Stuart ignores Jim's advice, and instead makes the decision of whether to attend based on the importance to his grade that he feels he'd be missing that day in class relative to his value of the extra time he could have to finish the video game he is playing. To an economist, Stuart is:
(Multiple Choice)
5.0/5 (82)
(82) Exhibit 2-18 Production possibilities curves 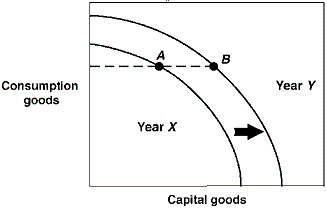 In Exhibit 2-18, the production possibilities curves for a country are shown for the years Year X and Year Y. Suppose this country was located at point A in Year X and point B in Year Y. This economy:
 (Multiple Choice)
4.9/5 (71)
(71) What to produce, how to produce, and for who to produce are the three fundamental economic questions.
(True/False)
4.8/5 (83)
(83) Using a production possibilities curve, a technological advance that increases the amount of output for the same amount of inputs would be illustrated as a(n):
(Multiple Choice)
4.8/5 (72)
(72) What shape is the production possibilities curve usually expected to exhibit?
(Multiple Choice)
4.9/5 (68)
(68) Exhibit 2-8 Production possibilities curve data 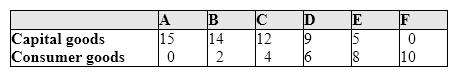 As shown in Exhibit 2-8, the concept of increasing opportunity costs is reflected in the fact that:
 (Multiple Choice)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)