



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


When firms in a competitive market have different costs, it is likely that
(Multiple Choice)
4.9/5  (88)
(88) In the short run, there are 500 identical firms in a competitive market. The firms do not use any resources that are available in limited quantities, and each of them has the following cost structure: 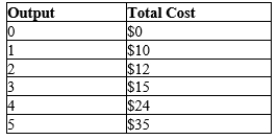 Which of the following is a point on the long-run supply curve?
 (Multiple Choice)
4.8/5 (79)
(79) In the short run for a particular market, there are 300 firms. Each firm has a marginal cost of $30 when it produces 200 units of output. $30 is above every firm's average variable cost. One point on the market supply curve is
(Multiple Choice)
4.8/5 (96)
(96) The production decisions of perfectly competitive firms follow one of the Ten Principles of Economics, which states that rational people
(Multiple Choice)
4.9/5 (81)
(81) If a firm observes that the price of its product is above average variable cost, it would choose to continue to produce the good in the short run, even if that firm experiences economic losses.
(True/False)
4.7/5 (73)
(73) A competitive firm currently produces and sells 7,500 units of output at a price of $2.50 per unit. The firm's average fixed cost is $0.75 and its average total cost is $2.80. In the short run, should the firm continue to operate?
(Essay)
4.8/5 (78)
(78) Which of the following industries is least likely to exhibit the characteristic of free entry?
(Multiple Choice)
4.9/5 (60)
(60) Figure 14-7 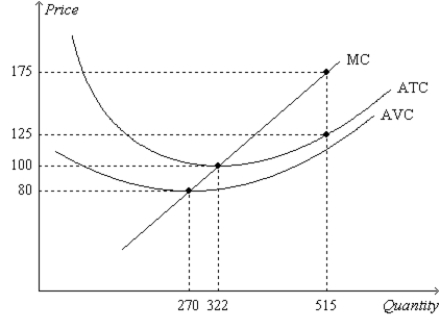 -Refer to Figure 14-7. Suppose the price of the good is $175. If the firm produces and sells 515 units of output, its total revenue is
 (Multiple Choice)
4.8/5 (69)
(69) In the long run, a competitive market with 1,000 identical firms will experience an equilibrium price equal to the minimum of each firm's average total cost.
(True/False)
4.9/5 (76)
(76) Which of these types of costs can be ignored when an individual or a firm is making decisions?
(Multiple Choice)
4.9/5 (86)
(86) Which of the following industries is most likely to exhibit the characteristic of free entry?
(Multiple Choice)
4.8/5 (83)
(83) A competitive firm currently produces and sells 500 units of output. Its total revenue is $6,000; the marginal cost of producing the 500th unit of output is $14.50; and the average total cost of producing the 500th unit of output is $9.50. Is the firm maximizing its profit, or should it increase or decrease output in order to increase its profit?
(Essay)
4.9/5 (80)
(80) In a competitive market the current price is $5. The typical firm in the market has ATC = $5.00 and AVC = $4.50.
(Multiple Choice)
4.9/5 (96)
(96) Table 14-14
The following table presents cost and revenue information for Bob's bakery production and sales. 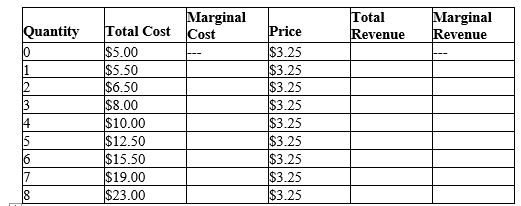 -Refer to Table 14-14. Suppose that due to a decrease in the market demand for bread the market price of bread drops to $2.75. At this new price, if Bob produces and sells the profit-maximizing quantity, how much profit will he earn?
 (Multiple Choice)
4.9/5 (83)
(83) A competitive market begins in a situation of long-run equilibrium. Then, there is a decrease in demand. Describe the process that eventually leads to a new long-run equilibrium.
(Essay)
4.7/5 (82)
(82) Robin owns a horse stables and riding academy and gives riding lessons for children at "pony camp." Her business operates in a competitive industry. Robin gives riding lessons to 20 children per month. Her monthly total revenue is $4,000. The marginal cost of pony camp is $250 per child. In order to maximize profits, Robin should
(Multiple Choice)
4.8/5 (67)
(67) "The water that comes out of your faucets at home is not supplied by a competitive firm." Explain why this statement is correct.
(Essay)
4.8/5 (79)
(79) For a firm in a perfectly competitive market, the price of the good is always
(Multiple Choice)
4.8/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)