



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


Table 14-13 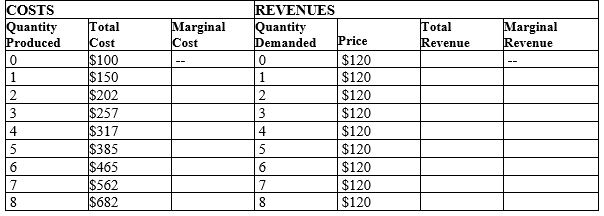 -Refer to Table 14-13. What is the marginal cost of the 1st unit?
 (Multiple Choice)
4.7/5  (80)
(80) Figure 14-9
In the figure below, panel (a) depicts the linear marginal cost of a firm in a competitive market, and panel (b) depicts the linear market supply curve for a market with a fixed number of identical firms. 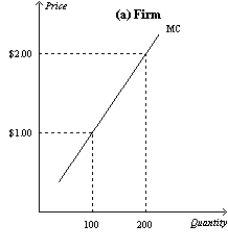
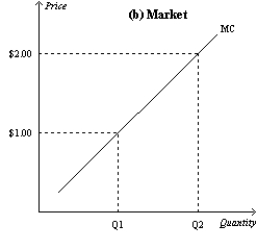 -Refer to Figure 14-9. If there are 400 identical firms in this market, what level of output will be supplied to the market when price is $2.00?
 (Multiple Choice)
4.7/5 (81)
(81) When a restaurant stays open for lunch service even though few customers patronize the restaurant for lunch, which of the following principles is (are) best demonstrated?
(i)Fixed costs are sunk in the short run.
(ii)In the short run, only fixed costs are important to the decision to stay open for lunch.
(iii)If revenue exceeds variable cost, the restaurant owner is making a smart decision to remain open for lunch.
(Multiple Choice)
4.9/5 (77)
(77) Table 14-12 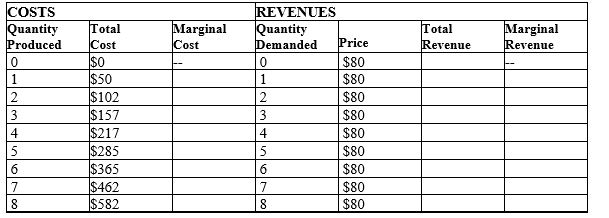 -Refer to Table 14-12. What is the marginal revenue from selling the 5th unit?
 (Multiple Choice)
4.8/5 (81)
(81) A competitive firm is producing 1,000 units of output with average total cost equal to $35 and marginal cost equal to $40. Can the market in which this firm operates be in a long-run equilibrium? Briefly explain.
(Essay)
4.8/5 (86)
(86) Which of the following expressions is correct for a competitive firm?
(Multiple Choice)
4.8/5 (68)
(68) If occupational safety laws were changed so that firms no longer had to take expensive steps to meet regulatory requirements, we would expect that
(Multiple Choice)
4.9/5 (78)
(78) In the long-run equilibrium of a market with free entry and exit, if all firms have the same cost structure, then
(Multiple Choice)
4.8/5 (69)
(69) In the long-run equilibrium of a competitive market, the number of firms in the market adjusts until the market demand is satisfied at a price equal to the minimum of
(Multiple Choice)
4.7/5 (78)
(78) A firm will shut down in the short run if the total revenue that it would get from producing and selling its output is less than its
(Multiple Choice)
4.8/5 (85)
(85) Scenario 14-4
Victor is the recipient of $1 million from a lawsuit. Victor decides to use the money to purchase a small business in Florida. His business operates in a perfectly competitive industry. If Victor would have invested the $1 million in a risk-free bond fund, he could have earned $100,000 each year. After he bought the small business, Victor quit his job as a market analyst with Research, Inc., where he used to earn $75,000 per year.
-Refer to Scenario 14-4. At the end of the first year of operating his new business, Victor's accountant reported an accounting profit of $150,000. What was Victor's economic profit?
(Multiple Choice)
4.8/5 (83)
(83) A competitive market is in long-run equilibrium. If demand decreases, we can be certain that price will
(Multiple Choice)
4.8/5 (78)
(78) Cold Duck Airlines flies between Tacoma and Portland. The company leases planes on a year-long contract at a cost that averages $600 per flight. Other costs (fuel, flight attendants, etc.) amount to $550 per flight. Currently, Cold Duck's revenues are $1,000 per flight. All prices and costs are expected to continue at their present levels. If it wants to maximize profit, Cold Duck Airlines should
(Multiple Choice)
4.8/5 (68)
(68) Explain the difference between the short run and the long run in terms of the number of firms in a competitive market.
(Essay)
5.0/5 (76)
(76) Figure 14-7 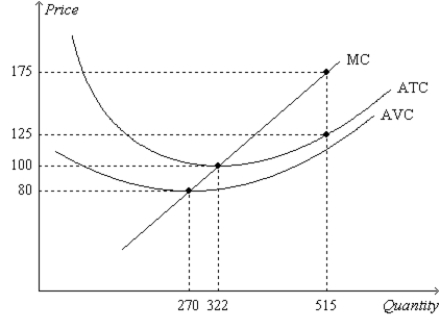 -Refer to Figure 14-7. When the price of the good is $175, the firm's maximum profit is
 (Multiple Choice)
4.9/5 (76)
(76) Which of the following is a characteristic of a competitive market?
(Multiple Choice)
4.9/5 (84)
(84) A profit-maximizing firm in a competitive market will always make marginal adjustments to production as long as
(Multiple Choice)
4.9/5 (66)
(66) When an individual firm in a competitive market decreases its production, it is likely that the market price will rise.
(True/False)
4.8/5 (84)
(84) Mr. Rogers sells colored pencils. The colored-pencil industry is competitive. Mr. Rogers hires a business consultant to analyze his company's financial records. The consultant recommends that Mr. Rogers increase his production. The consultant must have concluded that Mr. Roger's
(Multiple Choice)
4.8/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)