



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist643 Questions
Exam 3: Interdependence and the Gains From Trade547 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application626 Questions
Exam 6: Supply, Demand, and Government Policies668 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Applications: the Costs of Taxation509 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources452 Questions
Exam 12: The Design of the Tax System664 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets604 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice570 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Exam 23: Measuring a Nation S Income547 Questions
Exam 24: Measuring the Cost of Living565 Questions
Exam 25: Production and Growth527 Questions
Exam 26: Saving, Investment, and the Financial System637 Questions
Exam 27: Tools of Finance534 Questions
Exam 28: Unemployment and Its Natural Rate701 Questions
Exam 29: The Monetary System540 Questions
Exam 30: Money Growth and Inflation504 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts540 Questions
Exam 32: A Macroeconomic Theory of the Open Economy511 Questions
Exam 33: Aggregate Demand and Aggregate Supply572 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand523 Questions
Exam 35: The Short-Run Tradeoff Between Inflation and Unemployment536 Questions
Exam 36: Six Debates Over Macroeconomic Policy354 Questions
Select questions type


When profit-maximizing firms in competitive markets are earning profits,
(Multiple Choice)
4.9/5  (75)
(75) Scenario 14-1
Assume a certain firm in a competitive market is producing Q = 1,000 units of output. At Q = 1,000, the firm's marginal cost equals $15 and its average total cost equals $11. The firm sells its output for $12 per unit.
-Refer to Scenario 14-1. At Q = 1,000, the firm's profits equal
(Multiple Choice)
4.8/5 (75)
(75) Because there are many buyers and sellers in a perfectly competitive market, no one seller can influence the market price.
(True/False)
4.9/5 (84)
(84) A corporation has been steadily losing money on one of its product lines, plastic flamingo lawn ornaments. The firm produces plastic flamingos in a factory that cost $20 million to build 10 years ago. The firm is now considering an offer to buy that factory for $15 million. Which of the following statements about the decision to sell or not to sell is correct?
(Multiple Choice)
4.9/5 (79)
(79) Figure 14-3
Suppose a firm operating in a competitive market has the following cost curves: 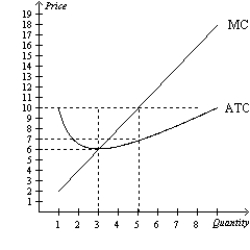 -Refer to Figure 14-3. The firm will earn positive economic profit if the market price is
 (Multiple Choice)
4.9/5 (78)
(78) Figure 14-9
Suppose a firm operating in a competitive market has the following cost curves: 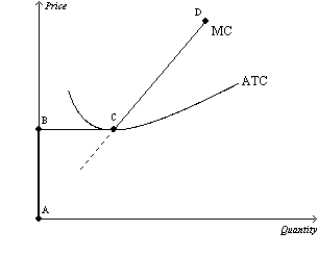 -Refer to Figure 14-9. The firm will exit the market for any price on the line segment
 (Multiple Choice)
4.9/5 (80)
(80) Suppose the long-run supply curve for a good is upward-sloping. The upward slope could be explained by
(Multiple Choice)
4.8/5 (83)
(83) When firms have an incentive to exit a competitive market, their exit will
(Multiple Choice)
4.7/5 (80)
(80) A profit-maximizing firm in a competitive market will decrease production when marginal cost exceeds average revenue.
(True/False)
4.9/5 (79)
(79) Figure 14-1
Suppose that a firm in a competitive market has the following cost curves: 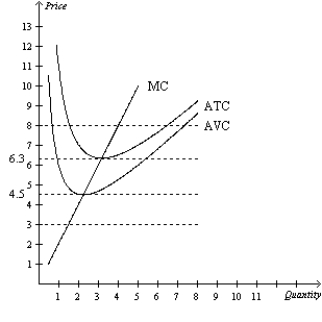 -Refer to Figure 14-1. If the market price is $4.00, the firm will earn
 (Multiple Choice)
4.9/5 (76)
(76) The short-run supply curve in a competitive market must be more elastic than the long-run supply curve.
(True/False)
4.9/5 (88)
(88) Which of the following industries is least likely to exhibit the characteristic of free entry?
(Multiple Choice)
4.8/5 (75)
(75) Figure 14-1
Suppose that a firm in a competitive market has the following cost curves:
-Refer to Figure 14-1. The firm should shut down if the market price is
-Refer to Figure 14-1. The firm should shut down if the market price is (Multiple Choice)
4.9/5 (85)
(85) Phil sells duck calls in a perfectly competitive market. If duck calls sell for $10 each and average total cost per unit is $11 at the profit-maximizing output level, then in the long run
(Multiple Choice)
4.7/5 (86)
(86) In the long run, a firm should exit the industry if its total costs exceed its total revenues.
(True/False)
4.8/5 (76)
(76) Which of the following industries is least likely to exhibit the characteristic of free entry?
(Multiple Choice)
4.8/5 (100)
(100) Figure 14-7 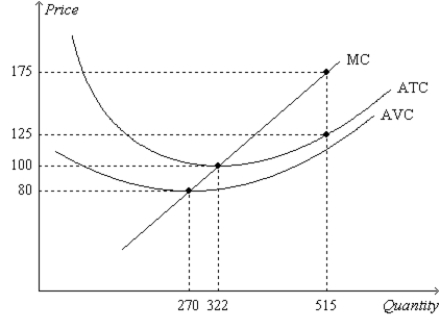 -Refer to Figure 14-7. The firm will shut down in the short run if the price of the good is
 (Multiple Choice)
4.8/5 (81)
(81) When price is below average variable cost, a firm in a competitive market will
(Multiple Choice)
5.0/5 (79)
(79) Table 14-11
Suppose that a firm in a competitive market faces the following prices and costs: 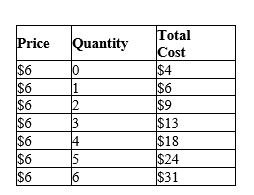 -Refer to Table 14-11. In order to maximize profits, the firm should stop producing after it makes the
 (Multiple Choice)
4.8/5 (78)
(78) In a perfectly competitive market, the process of entry and exit will end when firms face
(Multiple Choice)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)