



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist645 Questions
Exam 3: Interdependence and the Gains From Trade550 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application625 Questions
Exam 6: Supply, Demand, and Government Policies671 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Application: The Costs of Taxation507 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources453 Questions
Exam 12: The Design of the Tax System563 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets608 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice568 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Select questions type


Consumer surplus measures the benefit to buyers of participating in a market.
(True/False)
4.9/5  (74)
(74) The willingness to pay is the maximum amount that a buyer will pay for a good and measures how much the buyer values the good.
(True/False)
4.8/5 (88)
(88) Table 7-12
The numbers reveal the opportunity costs of providing 10 piano lessons of equal quality. 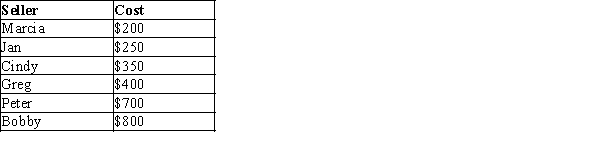 -Refer to Table 7-12. You wish to purchase 10 piano lessons, so you take bids from each of the sellers. You will not accept a bid below a seller's cost because you are concerned that the seller will not provide all 10 lessons. What bid will you accept?
 (Multiple Choice)
4.8/5 (93)
(93) Efficiency refers to whether a market outcome is fair, while equality refers to whether the maximum amount of output was produced from a given number of inputs.
(True/False)
4.8/5 (85)
(85) Figure 7-4 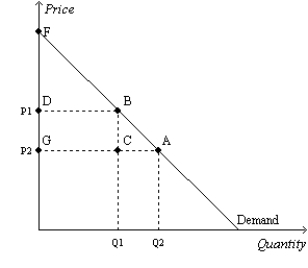 -Refer to Figure 7-4. Which area represents consumer surplus at a price of P2?
 (Multiple Choice)
4.8/5 (94)
(94) Scenario 7-2
Suppose market demand and market supply are given by the equations:  -Refer to Scenario 7-2. Suppose a reduction in input prices shifts the market supply curve to
 How much total consumer surplus goes to new consumers who enter the market after the supply curve shifts?
-Refer to Scenario 7-2. Suppose a reduction in input prices shifts the market supply curve to How much total consumer surplus goes to new consumers who enter the market after the supply curve shifts? (Essay)
4.8/5 (68)
(68) Table 7-9
The only four consumers in a market have the following willingness to pay for a good: 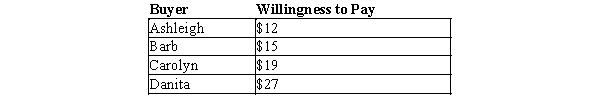 -Refer to Table 7-9. If there is only one unit of the good available for purchase, and if the buyers bid against each other for the right to purchase it, then the consumer surplus will be
 (Multiple Choice)
4.7/5 (78)
(78) Bill created a new software program he is willing to sell for $300. He sells his first copy and enjoys a producer surplus of $250. What is the price paid for the software?
(Multiple Choice)
4.7/5 (73)
(73) The study of how the allocation of resources affects economic well-being is called
(Multiple Choice)
4.9/5 (99)
(99) Figure 7-22 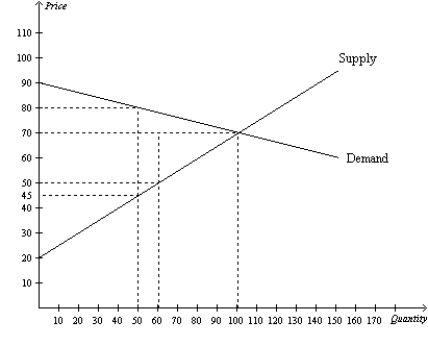 -Refer to Figure 7-22. If 110 units of the good are bought and sold, then
 (Multiple Choice)
4.8/5 (90)
(90) George produces cupcakes. His production cost is $10 per dozen. He sells the cupcakes for $16 per dozen. His producer surplus per dozen cupcakes is
(Multiple Choice)
4.7/5 (76)
(76) Figure 7-14 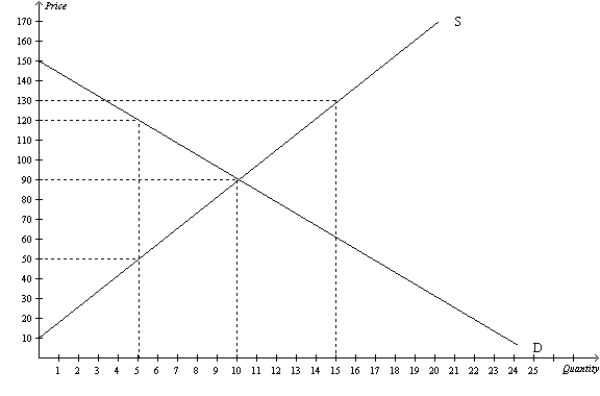 -Refer to Figure 7-14. If the market price increases to $130 due to an increase in demand, then producer surplus is
 (Multiple Choice)
4.8/5 (74)
(74) Dallas buys strawberries, and he would be willing to pay more than he now pays. Suppose that Dallas has a change in his tastes such that he values strawberries more than before. If the market price is the same as before, then
(Multiple Choice)
5.0/5 (85)
(85) Figure 7-15 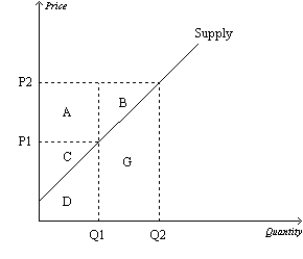 -Refer to Figure 7-15. When the price falls from P2 to P1, producer surplus
 (Multiple Choice)
4.9/5 (76)
(76) Table 7-16 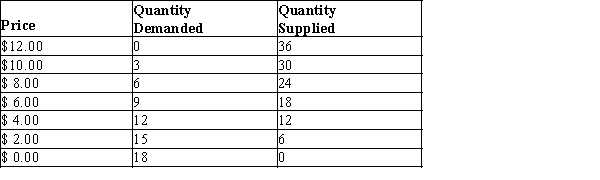 -Refer to Table 7-16. Both the demand curve and the supply curve are straight lines. If the price is $4 but only 6 units are bought and sold, producer surplus will be
 (Multiple Choice)
4.8/5 (72)
(72) Figure 7-3 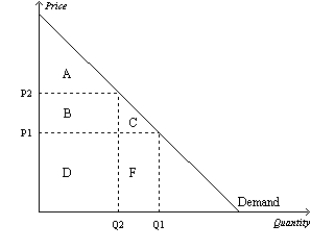 -Refer to Figure 7-3. When the price rises from P1 to P2, which of the following statements is not true?
 (Multiple Choice)
4.7/5 (72)
(72) If a market is allowed to move freely to its equilibrium price and quantity, then an increase in supply will
(Multiple Choice)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)