



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist645 Questions
Exam 3: Interdependence and the Gains From Trade550 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application625 Questions
Exam 6: Supply, Demand, and Government Policies671 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Application: The Costs of Taxation507 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources453 Questions
Exam 12: The Design of the Tax System563 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets608 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice568 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Select questions type


When markets fail, public policy can potentially remedy the problem and increase economic efficiency.
(True/False)
4.8/5  (71)
(71) If John's willingness to pay for a good is $20 and the price of the good is $15, how much is John's consumer surplus from purchasing the good?
(Short Answer)
4.8/5 (83)
(83) Table 7-17
The following table shows the willingness to pay for a good for the only four consumers in a market. 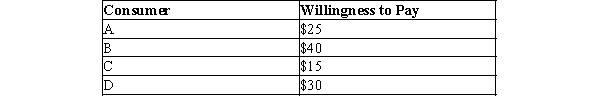 -Refer to Table 7-17. If the price of the good is $20, how many units will be demanded?
 (Short Answer)
4.8/5 (76)
(76) Figure 7-23 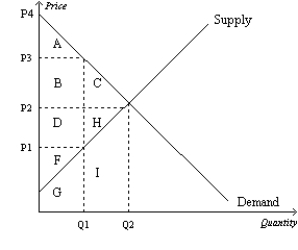 -Refer to Figure 7-23. At equilibrium, total surplus is represented by the area
 (Multiple Choice)
4.8/5 (86)
(86) Figure 7-30 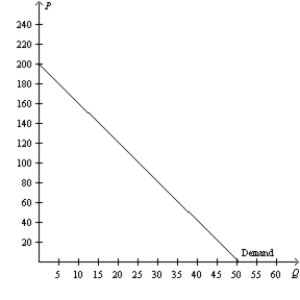 -Refer to Figure 7-30. If the market equilibrium price is $120, how much is total consumer surplus?
 (Short Answer)
4.8/5 (85)
(85) Figure 7-26 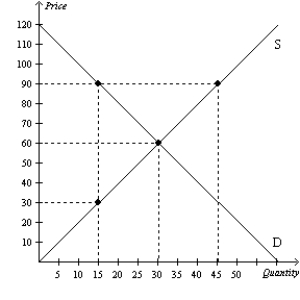 -Refer to Figure 7-26. At the equilibrium price, total surplus is
 (Multiple Choice)
4.8/5 (99)
(99) Table 7-14 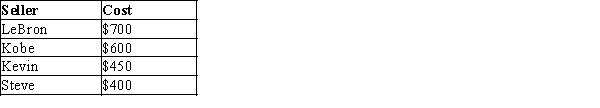 -Refer to Table 7-14. You want to hire a professional photographer to take pictures of your family. The table shows the costs of the four potential sellers in the local photography market. You hire Kevin for a price of $500. What is his producer surplus?
 (Multiple Choice)
4.9/5 (74)
(74) Table 7-10
The following table represents the costs of five possible sellers. 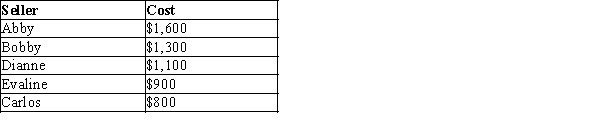 -Refer to Table 7-10. If the price is $1,l50, who would be willing to supply the product?
 (Multiple Choice)
4.8/5 (77)
(77) Denise values a stainless steel dishwasher for her new house at $500. The actual price of the dishwasher is $650. Denise
(Multiple Choice)
4.9/5 (66)
(66) Kelly is willing to pay $5.20 for a gallon of gasoline. The price of gasoline at her local gas station is $3.80. If she purchases ten gallons of gasoline, then Kelly's consumer surplus is
(Multiple Choice)
4.9/5 (80)
(80) If a market is allowed to adjust freely to its equilibrium price and quantity, then an increase in demand will
(Multiple Choice)
4.9/5 (71)
(71) Table 7-2
This table refers to five possible buyers' willingness to pay for a case of Vanilla Coke. 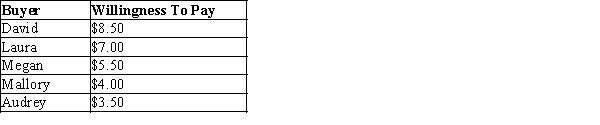 -Refer to Table 7-2. Which of the following is not true?
 (Multiple Choice)
4.9/5 (64)
(64) Figure 7-19 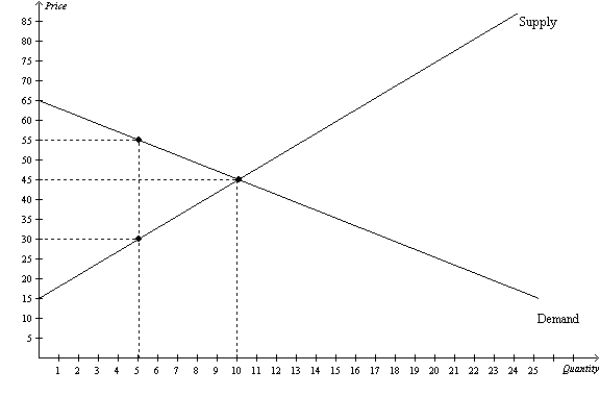 -Refer to Figure 7-19. If the government imposes a price floor of $55 in this market, then total surplus will be
 (Multiple Choice)
4.8/5 (96)
(96) Tom tunes pianos in his spare time for extra income. Buyers of his service are willing to pay $155 per tuning. One particular week, Tom is willing to tune the first piano for $120, the second piano for $125, the third piano for $140, and the fourth piano for $160. Assume Tom is rational in deciding how many pianos to tune. His producer surplus is
(Multiple Choice)
4.8/5 (78)
(78) A supply curve can be used to measure producer surplus because it reflects
(Multiple Choice)
4.9/5 (77)
(77) Table 7-5
For each of three potential buyers of oranges, the table displays the willingness to pay for the first three oranges of the day. Assume Allison, Bob, and Charisse are the only three buyers of oranges, and only three oranges can be supplied per day. 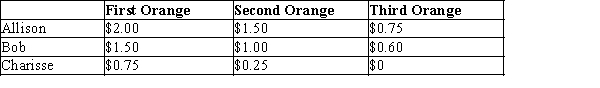 -Refer to Table 7-5. If the market price of an orange is $0.65, then consumer surplus amounts to
 (Multiple Choice)
4.7/5 (71)
(71) When the demand for a good increases and the supply of the good remains unchanged, consumer surplus
(Multiple Choice)
4.9/5 (77)
(77) If a consumer places a value of $15 on a particular good and if the price of the good is $17, then the
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)