



 Chat with AI
Exam 7: Consumers, Producers, and the Efficiency of Markets

Exam 1: Ten Principles of Economics455 Questions
Exam 2: Thinking Like an Economist645 Questions
Exam 3: Interdependence and the Gains From Trade550 Questions
Exam 4: The Market Forces of Supply and Demand693 Questions
Exam 5: Elasticity and Its Application625 Questions
Exam 6: Supply, Demand, and Government Policies671 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets547 Questions
Exam 8: Application: The Costs of Taxation507 Questions
Exam 9: Application: International Trade521 Questions
Exam 10: Externalities543 Questions
Exam 11: Public Goods and Common Resources453 Questions
Exam 12: The Design of the Tax System563 Questions
Exam 13: The Costs of Production649 Questions
Exam 14: Firms in Competitive Markets608 Questions
Exam 15: Monopoly662 Questions
Exam 16: Monopolistic Competition649 Questions
Exam 17: Oligopoly522 Questions
Exam 18: The Markets for the Factors of Production592 Questions
Exam 19: Earnings and Discrimination511 Questions
Exam 20: Income Inequality and Poverty478 Questions
Exam 21: The Theory of Consumer Choice568 Questions
Exam 22: Frontiers in Microeconomics461 Questions
Select questions type


Each seller of a product is willing to sell as long as the price he or she can receive is greater than the opportunity cost of producing the product.
(True/False)
4.9/5  (68)
(68) Scenario 7-2
Suppose market demand and market supply are given by the equations:  -Refer to Scenario 7-2. How much is total producer surplus at the equilibrium price in this market?
 (Essay)
4.9/5 (94)
(94) If the United States changed its laws to allow for the legal sale of a kidney, which of the following is likely to occur?
(Multiple Choice)
4.8/5 (81)
(81) All else equal, what happens to consumer surplus if the price of a good increases?
(Multiple Choice)
5.0/5 (78)
(78) Laissez-faire is a French expression which literally means
(Multiple Choice)
4.8/5 (68)
(68) Steak and chicken are substitutes. A sharp reduction in the supply of steak would
(Multiple Choice)
4.8/5 (95)
(95) Figure 7-15 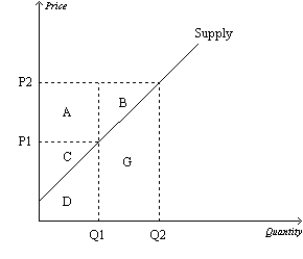 -Refer to Figure 7-15. When the price is P2, producer surplus is
 (Multiple Choice)
5.0/5 (77)
(77) Scenario 7-2
Suppose market demand and market supply are given by the equations:
-Refer to Scenario 7-2. Suppose a reduction in input prices shifts the market supply curve to  By how much does total consumer surplus increase as a result of this supply shift?
-Refer to Scenario 7-2. Suppose a reduction in input prices shifts the market supply curve to By how much does total consumer surplus increase as a result of this supply shift? (Essay)
4.9/5 (69)
(69) Josh is willing to pay $500 for a set of tire, but he is able to pay $300 at the local tire store. His consumer surplus is
(Multiple Choice)
4.8/5 (79)
(79) Which of the Ten Principles of Economics does welfare economics explain more fully?
(Multiple Choice)
4.8/5 (82)
(82) When policymakers are considering a particular action, they can use consumer surplus as a(n)
(Multiple Choice)
4.8/5 (79)
(79) Ticket scalping can increase total surplus in the market for tickets to sporting events.
(True/False)
4.9/5 (79)
(79) Figure 7-19 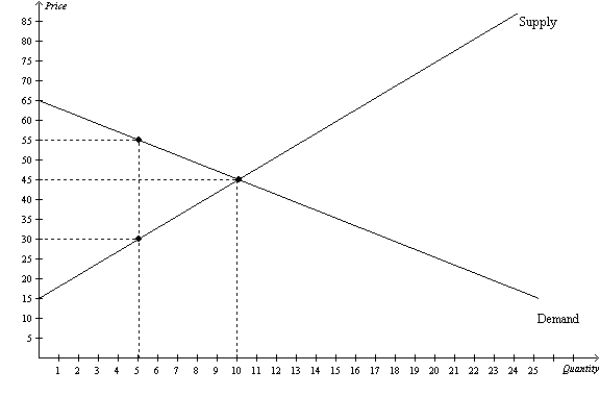 -Refer to Figure 7-19. If the government imposes a price ceiling of $55 in this market, then total surplus will be
 (Multiple Choice)
4.9/5 (74)
(74) Table 7-18
The following table shows the cost of producing a good for the only four producers in a market. 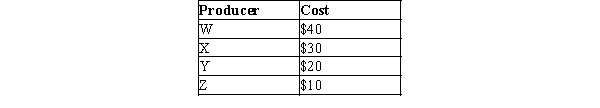 -Refer to Table 7-18. If the market equilibrium price is $28, what is total producer surplus in the market?
 (Short Answer)
4.9/5 (83)
(83) Figure 7-11 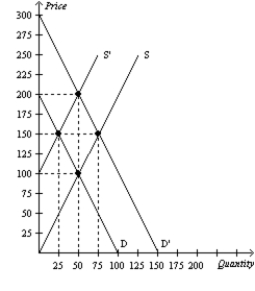 -Refer to Figure 7-11. If the supply curve is S, the demand curve is D, and the equilibrium price is $100, what is the producer surplus?
 (Multiple Choice)
4.8/5 (76)
(76) All else equal, a decrease in demand will cause an increase in producer surplus.
(True/False)
4.8/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)