



 Chat with AI
Exam 14: Oligopoly: Firms in Less Competitive Markets

Exam 1: Economics: Foundations and Models459 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes420 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care337 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance512 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs326 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets256 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income260 Questions
Exam 20: Unemployment and Inflation290 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles251 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies261 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run305 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money, Banks, and the Federal Reserve System278 Questions
Exam 26: Monetary Policy280 Questions
Exam 27: Fiscal Policy313 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy277 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Table 14-6 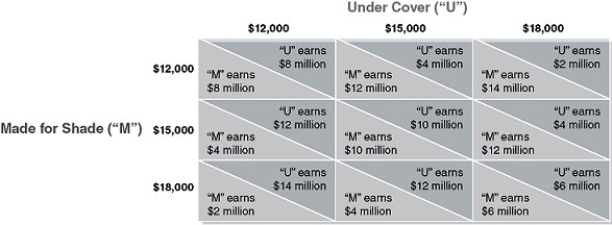 There are two custom carport manufacturers in Louisiana, Under Cover (U) and Made for Shade (M). Under Cover has been in the market for a long time and must now compete with newcomer, Made for Shade. Suppose that Under Cover believes that Made for Shade will match any price it sets. Use Table 14-6 to answer the following question and assume throughout that Under Cover believes that Made for Shade will match any price it sets.
-Refer to Table 14-6. What price will Under Cover charge and what profit does Under Cover expect to make?
There are two custom carport manufacturers in Louisiana, Under Cover (U) and Made for Shade (M). Under Cover has been in the market for a long time and must now compete with newcomer, Made for Shade. Suppose that Under Cover believes that Made for Shade will match any price it sets. Use Table 14-6 to answer the following question and assume throughout that Under Cover believes that Made for Shade will match any price it sets.
-Refer to Table 14-6. What price will Under Cover charge and what profit does Under Cover expect to make? (Multiple Choice)
4.8/5  (86)
(86) An oligopoly firm is similar to a monopolistically competitive firm in that
(Multiple Choice)
4.8/5 (66)
(66) Figure 14-2  The government of a developing country plans to award two firms, Gigacom and Xenophone, the exclusive rights to share the market for high speed internet service. Gigacom and Xenophone can both provide the service either via television cable lines or via direct subscriber line (DSL). Suppose the government is considering a proposal to delay one firm's entry into the market on the grounds that it wants to prevent "harmful" competition. Figure 14-2 shows the decision tree for this game.
-Refer to Figure 14-2. If the government delays Gigacom's entry and Xenophone moves first, what is the likely outcome in the market?
The government of a developing country plans to award two firms, Gigacom and Xenophone, the exclusive rights to share the market for high speed internet service. Gigacom and Xenophone can both provide the service either via television cable lines or via direct subscriber line (DSL). Suppose the government is considering a proposal to delay one firm's entry into the market on the grounds that it wants to prevent "harmful" competition. Figure 14-2 shows the decision tree for this game.
-Refer to Figure 14-2. If the government delays Gigacom's entry and Xenophone moves first, what is the likely outcome in the market? (Multiple Choice)
4.8/5 (72)
(72) A game in which pursuing dominant strategies results in noncooperation that leaves all parties worse off is a
(Multiple Choice)
4.8/5 (72)
(72) A set of actions that a firm takes to achieve a goal is the definition of a
(Multiple Choice)
4.8/5 (78)
(78) Game theory was developed in the 1940s by John von Neuman, a mathematician, and an economist named
(Multiple Choice)
4.8/5 (80)
(80) Which of the following is not a shortcoming of the concentration ratio as a measure of the extent of competition in an industry?
(Multiple Choice)
4.8/5 (79)
(79) Consider a U-shaped long-run average cost curve that has a minimum efficient scale at 6,000 units of output. In this case, this industry would be
(Multiple Choice)
4.9/5 (80)
(80) Producing a homogeneous product occurs in which of the following industries?
(Multiple Choice)
4.8/5 (82)
(82) All of the following are examples of oligopolistic markets except
(Multiple Choice)
4.8/5 (75)
(75) Explain why selling output at a price below that at which marginal revenue equals marginal cost (MR = MC) might serve to deter entry of a potential competitor.
(Essay)
4.9/5 (85)
(85) Decision trees are commonly used to illustrate how firms make business decisions that depend on the actions of rival firms. A decision tree has boxes that contain points that represent when firms must make the decisions contained in the boxes. What are these points called?
(Multiple Choice)
4.9/5 (90)
(90) Figure 14-5  Netflix (N) was one of the first companies to offer streaming video services and is still considered a leader in the industry. Spotify (S) offers a music streaming service and in 2015 considered entering the video streaming business. At that point, Netflix had to decide whether or not to lower its subscription price in order to deter Spotify's entry into the market. Figure 14-5 shows a hypothetical decision tree for the Netflix-Spotify entry game.
-Refer to Figure 14-5. If Netflix lowers its price, will this deter Spotify from setting up a streaming video service?
Netflix (N) was one of the first companies to offer streaming video services and is still considered a leader in the industry. Spotify (S) offers a music streaming service and in 2015 considered entering the video streaming business. At that point, Netflix had to decide whether or not to lower its subscription price in order to deter Spotify's entry into the market. Figure 14-5 shows a hypothetical decision tree for the Netflix-Spotify entry game.
-Refer to Figure 14-5. If Netflix lowers its price, will this deter Spotify from setting up a streaming video service? (Multiple Choice)
4.8/5 (85)
(85) Table 14-5  Martin and Lewis each run one of the two bingo parlors in Schenectady. Both consider offering free rides to and from the parlors. Table 14-5 shows the payoff matrix containing the expected weekly profits for each bingo parlor.
-Refer to Table 14-5. Does Martin have a dominant strategy? If yes, what is it?
Martin and Lewis each run one of the two bingo parlors in Schenectady. Both consider offering free rides to and from the parlors. Table 14-5 shows the payoff matrix containing the expected weekly profits for each bingo parlor.
-Refer to Table 14-5. Does Martin have a dominant strategy? If yes, what is it? (Multiple Choice)
4.9/5 (89)
(89) Monopolistic competition differs from oligopoly in that in monopolistic competition firms act independently while in oligopoly firms act interdependently.
(True/False)
4.9/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)