



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models447 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes420 Questions
Exam 5: Externalities, environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply294 Questions
Exam 7: The Economics of Health Care338 Questions
Exam 8: Firms,the Stock Market,and Corporate Governance522 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology,production,and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets258 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income261 Questions
Exam 20: Unemployment and Inflation291 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles253 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies262 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run301 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money,banks,and the Federal Reserve System281 Questions
Exam 26: Monetary Policy275 Questions
Exam 27: Fiscal Policy306 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Quantity Total Cost (dollars) Variable Cost (dollars) 0 \ 1,000 \ 0 100 1,360 360 200 1,560 560 300 1,960 960 400 2,760 1,760 500 4,000 3,000 600 5,800 4,800 Table 12-1 shows the short-run cost data of a perfectly competitive firm that produces plastic camera cases.Assume that output can only be increased in batches of 100 units.
-Refer to Table 12-1.Suppose the fixed cost of production rises by $500 and the price per unit is still $8.What happens to the firm's profit-maximizing output level?
(Multiple Choice)
5.0/5  (70)
(70) In long-run perfectly competitive equilibrium,which of the following is false?
(Multiple Choice)
4.8/5 (68)
(68) At the profit-maximizing level of output for a perfectly competitive firm,price equals marginal cost.Which of the following is also true?
(Multiple Choice)
4.9/5 (82)
(82) The demand curve for an individual seller's product in perfect competition is
(Multiple Choice)
4.7/5 (77)
(77) Figure 12-12 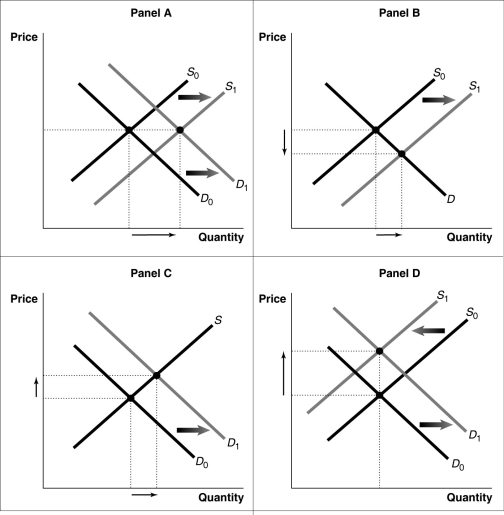 -Refer to Figure 12-12.Consider a typical firm in a perfectly competitive industry that makes short-run profits.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.8/5 (84)
(84) A perfectly competitive firm in a constant-cost industry produces 1,000 units of a good at a total cost of $50,000.If the prevailing market price is $48,the number of firms and the industry's output will decrease in the long run.
(True/False)
4.8/5 (85)
(85) If,as a perfectly competitive industry expands,it can supply larger quantities at the same long-run market price,it is
(Multiple Choice)
4.8/5 (67)
(67) Figure 12-15 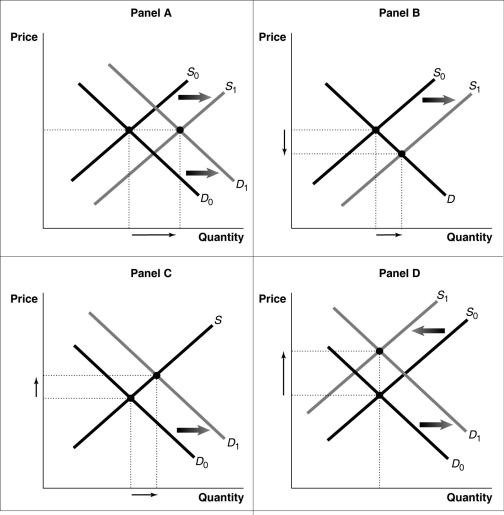 -Refer to Figure 12-15.Suppose a typical firm in a perfectly competitive market is earning economic profits in the short run.Which of the diagrams in the figure depicts what happens in the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.8/5 (79)
(79) Assume that the personal computer industry is perfectly competitive.The fact that the price of personal computers over the last decade has fallen despite increases in demand signifies that the industry is a decreasing-cost industry.
(True/False)
4.8/5 (78)
(78) In a graph with output on the horizontal axis and total revenue on the vertical axis,what is the shape of the total revenue curve for a perfectly competitive seller?
(Multiple Choice)
4.8/5 (78)
(78) Figure 12-3 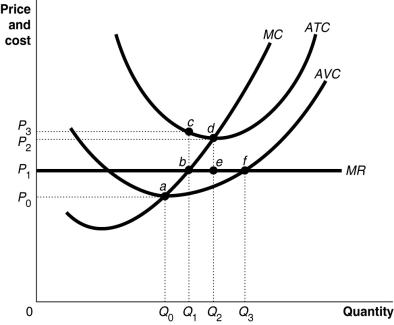 -Refer to Figure 12-3.Suppose the prevailing price is P1 and the firm is currently producing its loss-minimizing quantity.Identify the area that represents the loss.
 (Multiple Choice)
4.9/5 (84)
(84)  Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30,should the firm represented in the diagram continue to stay in business?
Figure 12-4 shows the cost and demand curves for a profit-maximizing firm in a perfectly competitive market.
-Refer to Figure 12-4.If the market price is $30,should the firm represented in the diagram continue to stay in business? (Multiple Choice)
4.9/5 (73)
(73) Which of the following is not true for a firm in perfect competition?
(Multiple Choice)
4.9/5 (67)
(67) Why are individual buyers and sellers in perfect competition called price takers?
(Essay)
4.9/5 (83)
(83) What assumptions are necessary for a market to be perfectly competitive? Explain why each of these assumptions is important.
(Essay)
5.0/5 (72)
(72) Perfectly competitive firms produce up to the point where the price of the good equals the marginal cost of producing the last unit.This condition is referred to as
(Multiple Choice)
4.9/5 (86)
(86) In the short run,a firm that is operating at a loss has two options.These options are
(Multiple Choice)
4.8/5 (71)
(71)  Figure 12-9 shows cost and demand curves facing a profit-maximizing,perfectly competitive firm.
-Refer to Figure 12-9.At price P3,the firm would produce
Figure 12-9 shows cost and demand curves facing a profit-maximizing,perfectly competitive firm.
-Refer to Figure 12-9.At price P3,the firm would produce (Multiple Choice)
4.7/5 (78)
(78) When plasma television sets were first introduced prices were high and few firms were in the market.Later,economic profits attracted new firms and the price of plasma televisions fell.This example illustrates
(Multiple Choice)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)