



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models447 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes420 Questions
Exam 5: Externalities, environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply294 Questions
Exam 7: The Economics of Health Care338 Questions
Exam 8: Firms,the Stock Market,and Corporate Governance522 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology,production,and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets258 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income261 Questions
Exam 20: Unemployment and Inflation291 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles253 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies262 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run301 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money,banks,and the Federal Reserve System281 Questions
Exam 26: Monetary Policy275 Questions
Exam 27: Fiscal Policy306 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Figure 12-8  -Refer to Figure 12-8.Suppose the firm produces 4,000 units.What does the shaded area labeled B represent?
 (Multiple Choice)
4.8/5  (75)
(75) Quantity Average Fixed Cost Average Variable Cost Marginal Cost 20 \ 40 \ 18 \ 18 40 20 14 10 60 13.1 16 20 80 10 22 40 100 8 30 62 120 6.61 40 90 Table 12-4 shows the short-run cost data of a perfectly competitive firm.Assume that output can only be increased in batches of 20 units.
-Refer to Table 12-4.If the market price is $45,the firm
(Multiple Choice)
4.8/5 (73)
(73) Figure 12-16  -Refer to Figure 12-16.Which panel best represents the perfectly competitive organic produce market in which firms are breaking even,economically,organic produce is considered a normal good,and the average income level of consumers is rising?
 (Multiple Choice)
4.7/5 (75)
(75) If in the long run a firm makes zero profit,it should exit the industry.
(True/False)
4.8/5 (70)
(70) When a perfectly competitive firm finds that its market price is below its minimum average variable cost,it will sell
(Multiple Choice)
4.9/5 (75)
(75) Which of the following describes the difference between the market demand curve for a perfectly competitive industry and the demand curve for a firm in this industry?
(Multiple Choice)
4.8/5 (79)
(79) Figure 12-16
-Refer to Figure 12-16.Which panel best represents the perfectly competitive organic produce market in which some firms are earning short-run economic profits,and the Surgeon General announces that switching from non-organic produce to organic produce will add 5 years to the average life span of consumers?
-Refer to Figure 12-16.Which panel best represents the perfectly competitive organic produce market in which some firms are earning short-run economic profits,and the Surgeon General announces that switching from non-organic produce to organic produce will add 5 years to the average life span of consumers? (Multiple Choice)
4.8/5 (63)
(63) In an increasing-cost industry the long-run supply curve is upward sloping.
(True/False)
4.8/5 (70)
(70) Maximizing average profit is equivalent to maximizing total profit.
(True/False)
4.7/5 (81)
(81) A teenaged babysitter is similar to a firm in a perfectly competitive industry in that,for both
(Multiple Choice)
4.8/5 (80)
(80) What is always true at the quantity where a firm's average total cost equals average revenue?
(Multiple Choice)
4.8/5 (78)
(78) Figure 12-14 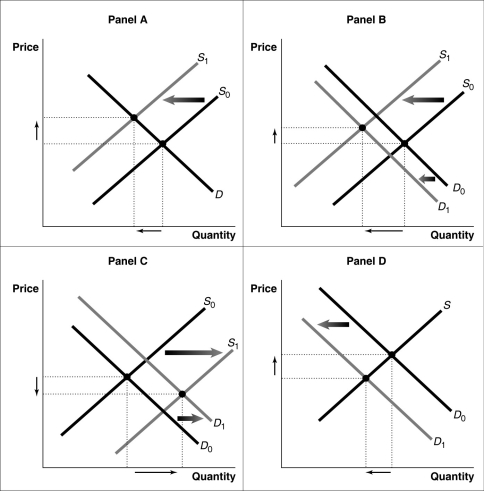 -Refer to Figure 12-14.Consider a typical firm in a perfectly competitive industry which is incurring short-run losses.Which of the diagrams in the figure shows the effect on the industry as it transitions to a long-run equilibrium?
 (Multiple Choice)
4.8/5 (84)
(84)  Figure 12-9 shows cost and demand curves facing a profit-maximizing,perfectly competitive firm.
-Refer to Figure 12-9.At price P1,the firm would
Figure 12-9 shows cost and demand curves facing a profit-maximizing,perfectly competitive firm.
-Refer to Figure 12-9.At price P1,the firm would (Multiple Choice)
4.8/5 (73)
(73) If the market price is $25 in a perfectly competitive market,the marginal revenue from selling the fifth unit is
(Multiple Choice)
4.9/5 (83)
(83) Assume that the LCD and plasma television sets industry is perfectly competitive.Suppose a producer develops a successful innovation that enables it to lower its cost of production.What happens in the short run and in the long run?
(Multiple Choice)
4.7/5 (80)
(80)  Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost,perfectly competitive industry.
-Refer to Figure 12-5.If the market price is $20,what is the average profit at the profit-maximizing quantity?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost,perfectly competitive industry.
-Refer to Figure 12-5.If the market price is $20,what is the average profit at the profit-maximizing quantity? (Multiple Choice)
4.9/5 (80)
(80) A perfectly competitive firm produces 3,000 units of a good at a total cost of $36,000.The fixed cost of production is $20,000.The price of each good is $10.Should the firm continue to produce in the short run?
(Multiple Choice)
4.9/5 (70)
(70) Table 12-5
Quantity (cases) Variable Cost Total Cost Marginal Cost Average Variable Cost Average Total Cost 0 \ 0 \ 76 1 30 106 2 50 3 134 4 140 5 160 6 114 7 150 8 190 9 316 Use the table to answer the following questions.
a.Complete Table 12-5 by filling in the blank cells.
b.Werner is selling in a perfectly competitive market at a price of $40.What is the profit maximizing or loss-minimizing output?
c.Calculate the firm's profit or loss.
d.Should the firm continue to produce in the short run? Explain.
e.If the firm's fixed costs were $30 higher what would be the profit-maximizing output level in the short run? Indicate whether the output level will increase,decrease,or remain unchanged compared to your answer in b.
f.Suppose fixed cost remains at $76.If the price of three-ring binders falls to $20 what is the profit-maximizing or loss-minimizing output?
g.Calculate the profit or loss.Should the firm continue to produce in the short run? Explain your answer.
h.Suppose the fixed cost remains at $76.What price corresponds to the shut-down point?
i.Suppose the fixed cost remains at $76.What price corresponds to the break-even point?
Answer:
a.
Quantity (cases) Variable Cost Total Cost Marginal Cost Average Variable Cost Average Total Cost 0 \ 0 \ 76 -- -- \ 76 1 30 106 \ 30 \ 30 106 2 50 126 20 25 63 3 58 134 8 19.33 44.67 4 64 140 6 16 35 5 84 160 20 16.8 32 6 114 190 30 19 31.67 7 150 226 36 21.43 32.29 8 190 266 40 23.75 33.25 9 240 316 50 26.67 35.11 b.Quantity = 8 units.
c.Profit = $54.
d.Yes,it is earning an economic profit.
e.The profit-maximizing output will not change since marginal cost is not affected by changes in fixed cost.
f.Quantity = 5 units.
g.Loss = $60.Yes,it is loss-minimizing.
h.The shut-down point corresponds to a price of $16 and an output of 4 units.
i.The break-even point occurs at a price $31.67 and an output of 6 units.
Diff: 3 Page Ref: 421-422
Topic: Profit-Maximizing Level of Output
*: Recurring
Learning Outcome: Micro-13: Explain the relationship between production and profits under perfect competition
AACSB: Analytical thinking
-Use a graph to show the demand,AVC,ATC,MC,and MR curves of a firm that should temporarily shut down in the short run.Identify the shutdown point on the graph.
(Essay)
4.7/5 (80)
(80) Figure 12-11  -Refer to Figure 12-11.Suppose the prevailing price is $20 and the firm is currently producing 1,350 units.In the long-run equilibrium
 (Multiple Choice)
4.9/5 (77)
(77) If,as a perfectly competitive industry expands,it can supply larger quantities only at a higher long-run equilibrium price,it is
(Multiple Choice)
4.7/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)