



 Chat with AI
Exam 12: Firms in Perfectly Competitive Markets

Exam 1: Economics: Foundations and Models447 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes420 Questions
Exam 5: Externalities, environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply294 Questions
Exam 7: The Economics of Health Care338 Questions
Exam 8: Firms,the Stock Market,and Corporate Governance522 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology,production,and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets258 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income261 Questions
Exam 20: Unemployment and Inflation291 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles253 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies262 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run301 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money,banks,and the Federal Reserve System281 Questions
Exam 26: Monetary Policy275 Questions
Exam 27: Fiscal Policy306 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Assume that the tuna fishing industry is perfectly competitive.Which of the following best characterizes the industry if,as demand for tuna increases,fishing boats have to go farther into the ocean to harvest tuna?
(Multiple Choice)
4.8/5  (73)
(73) The price of a seller's product in perfect competition is determined by
(Multiple Choice)
4.9/5 (76)
(76) Figure 12-10  -Refer to Figure 12-10.The total cost at the profit-maximizing output level equals
 (Multiple Choice)
5.0/5 (63)
(63) Article Summary
According to the Department of Agriculture,net farm income will fall from $91.1 billion in 2014 to $58.3 billion in 2015,a 36 percent drop and the largest percentage decline since 1983.Falling prices on corn and soybeans are responsible for a portion of the decline in income,as are lower prices for dairy products,hogs,and chickens.The USDA is,however,predicting lower production costs due to falling prices for energy,seed,fertilizer,and pesticides.
-Refer to the Article Summary.Assume that after the record decline in U.S.farm income in 2015,farmers are expected to break even in 2016.This means that at the quantity being produced in 2016
(Multiple Choice)
5.0/5 (82)
(82)  Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost,perfectly competitive industry.
-Refer to Figure 12-5.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens in the diagram above?
Figure 12-5 shows cost and demand curves facing a typical firm in a constant-cost,perfectly competitive industry.
-Refer to Figure 12-5.If the firm's fixed cost increases by $1,000 due to a new environmental regulation,what happens in the diagram above? (Multiple Choice)
4.9/5 (83)
(83) A perfectly competitive wheat farmer in a constant-cost industry produces 3,000 bushels of wheat at a total cost of $36,000.The prevailing market price is $15.What will happen to the market price of wheat in the long run?
(Multiple Choice)
4.9/5 (79)
(79) Of the following industries,which are perfectly competitive? For those that are not perfectly competitive,explain why.
a.Restaurants
b.Corn
c.College education
d.Local radio and television
(Essay)
4.8/5 (74)
(74) A wheat farmer and a firm in a perfectly competitive market are similar in that
(Multiple Choice)
4.8/5 (71)
(71) Mark Frost grows apples in a perfectly competitive market.If we drew a line in a graph that illustrates Mark's total revenue from selling apples,it would be
(Multiple Choice)
4.9/5 (84)
(84) For a perfectly competitive firm,average revenue is equal to
(Multiple Choice)
5.0/5 (89)
(89) For a given quantity,the total profit of a perfectly competitive firm is equal to the vertical distance between the firm's total revenue curve and its total cost curve.
(True/False)
4.9/5 (84)
(84) Perfectly competitive industries tend to produce low-priced,low-technology products.
(True/False)
4.9/5 (90)
(90) A constant-cost,perfectly competitive market is in long-run equilibrium.At present,there are 1,000 firms each producing 400 units of output.The price of the good is $60.Now suppose there is a sudden increase in demand for the industry's product which causes the price of the good to rise to $64.In the new long-run equilibrium,how will the average total cost of producing the good compare to what it was before the price of the good rose?
(Multiple Choice)
4.8/5 (80)
(80) Figure 12-13 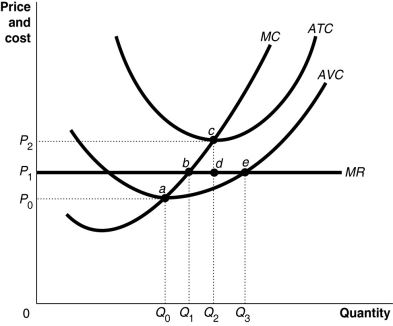 -Refer to Figure 12-13.Suppose the prevailing price is P1 and the firm is currently producing its loss-minimizing quantity.If the firm represented in the diagram continues to stay in business,in the long-run equilibrium
 (Multiple Choice)
4.8/5 (73)
(73) Apple introduced its iPhone 3G in July 2008 and within a month sales had topped 3 million units.By April 2009,more than 25,000 apps for the iPhone 3G were available in the iTunes store,an indication that in a competitive market
(Multiple Choice)
4.9/5 (81)
(81) A perfectly competitive firm will maximize its profit at the rate of output where the vertical distance between its total revenue curve and total cost curve is the largest.This is the same rate of output where
(Multiple Choice)
4.7/5 (74)
(74) Producing where marginal revenue equals marginal cost is equivalent to producing where
(Multiple Choice)
4.7/5 (69)
(69) Letters are used to represent the terms used to answer this question: price (P),quantity of output (Q),total cost (TC)and average total cost (ATC).Which of the following equations is equal to a firm's average profit?
(Multiple Choice)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)