



 Chat with AI
Exam 15: Monopoly and Antitrust Policy

Exam 1: Economics: Foundations and Models447 Questions
Exam 2: Trade-Offs, comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, government Price Setting, and Taxes420 Questions
Exam 5: Externalities, environmental Policy, and Public Goods263 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply294 Questions
Exam 7: The Economics of Health Care338 Questions
Exam 8: Firms,the Stock Market,and Corporate Governance522 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics300 Questions
Exam 11: Technology,production,and Costs327 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets258 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy261 Questions
Exam 17: The Markets for Labor and Other Factors of Production281 Questions
Exam 18: Public Choice, taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income261 Questions
Exam 20: Unemployment and Inflation291 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles253 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies262 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run301 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money,banks,and the Federal Reserve System281 Questions
Exam 26: Monetary Policy275 Questions
Exam 27: Fiscal Policy306 Questions
Exam 28: Inflation, unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy278 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Figure 15-5 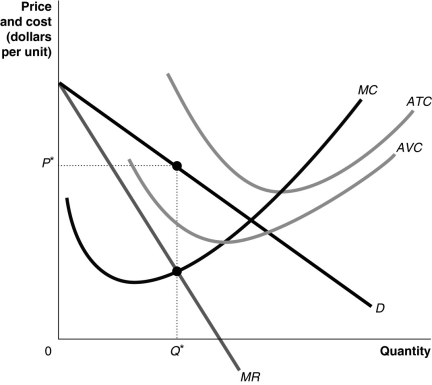 -Refer to Figure 15-5.If the monopolist charges price P* for output Q*,in order to maximize profit or minimize loss in the short run,it should
 (Multiple Choice)
4.9/5  (77)
(77) Arnold Harberger was the first economist to estimate the loss of economic efficiency due to market power.Harberger found that
(Multiple Choice)
4.8/5 (71)
(71)  Figure 15-4 shows the demand and cost curves for a monopolist.
-Refer to Figure 15-4.What is the price charged for the profit-maximizing output level?
Figure 15-4 shows the demand and cost curves for a monopolist.
-Refer to Figure 15-4.What is the price charged for the profit-maximizing output level? (Multiple Choice)
4.9/5 (84)
(84)  Figure 15-12 shows the cost and demand curves for a monopolist.
-Refer to Figure 15-12.Assume the firm maximizes its profits.What is the amount of consumer surplus?
Figure 15-12 shows the cost and demand curves for a monopolist.
-Refer to Figure 15-12.Assume the firm maximizes its profits.What is the amount of consumer surplus? (Multiple Choice)
5.0/5 (86)
(86) Figure 15-14 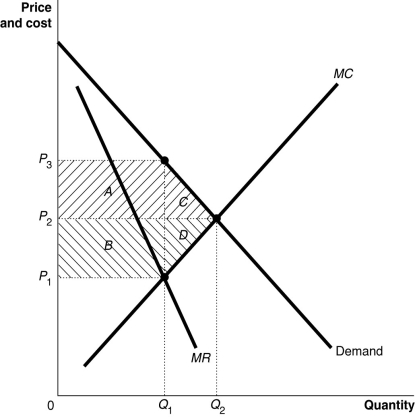 -Refer to Figure 15-14.From the monopoly graph above,identify the following:
a.The profit maximizing price
b.The profit maximizing quantity
c.The area representing deadweight loss
d.The area representing the transfer of consumer surplus to the monopoly
-Refer to Figure 15-14.From the monopoly graph above,identify the following:
a.The profit maximizing price
b.The profit maximizing quantity
c.The area representing deadweight loss
d.The area representing the transfer of consumer surplus to the monopoly (Essay)
4.8/5 (84)
(84)
Price Quantity Total Revenue Marginal Revenue Total Cost Marginal Cost \ 17 3 \ 51 ---- \ 56 ---- 16 4 64 \ 13 63 \ 7 15 5 75 11 71 8 14 6 84 9 80 9 13 7 91 7 90 10 12 8 96 5 101 11 Assume Table 15-3 gives the monthly demand and costs for subscriptions to basic cable for Comcast,a cable television monopoly in Philadelphia.
-Refer to Table 15-3.If Comcast wants to maximize its profits,what price (P)should it charge and how many cable subscriptions per month (Q)should it sell?
(Multiple Choice)
5.0/5 (86)
(86) Economic efficiency requires that a natural monopoly's price be
(Multiple Choice)
4.8/5 (80)
(80) Figure 15-17  Your college decides to offer a psychology course as a MOOC that can be taken by students anywhere in the world,whether they are actually enrolled in your college or not.The demand and cost situation for the MOOC is shown in the figure.
-Refer to Figure 15-17.An economics professor argues: "I think the course should be priced so as to achieve economic efficiency." Which price should this faculty member favor?
Your college decides to offer a psychology course as a MOOC that can be taken by students anywhere in the world,whether they are actually enrolled in your college or not.The demand and cost situation for the MOOC is shown in the figure.
-Refer to Figure 15-17.An economics professor argues: "I think the course should be priced so as to achieve economic efficiency." Which price should this faculty member favor? (Multiple Choice)
4.7/5 (81)
(81)  Figure 15-16 shows the market demand and cost curves facing a natural monopoly.
-Refer to Figure 15-16.Suppose the government regulates this industry in order to remove the inefficiency implied by the behavior of the profit-maximizing owners.If regulators require that the firm produces the economically efficient output level,what is this level and what price will be charged?
Figure 15-16 shows the market demand and cost curves facing a natural monopoly.
-Refer to Figure 15-16.Suppose the government regulates this industry in order to remove the inefficiency implied by the behavior of the profit-maximizing owners.If regulators require that the firm produces the economically efficient output level,what is this level and what price will be charged? (Multiple Choice)
4.8/5 (65)
(65) a.What is the difference between a horizontal merger and a vertical merger?
b.Give an example of each type of merger.
c.Could a horizontal merger be welfare improving?
(Essay)
4.8/5 (92)
(92) Which of the following statements is consistent with the views of Joseph Schumpeter?
(Multiple Choice)
4.8/5 (72)
(72) Economists played a key role in the development of merger guidelines by the Department of Justice and the Federal Trade Commission in 1982.These guidelines have three main parts.What are these parts?
(Multiple Choice)
4.8/5 (78)
(78) Figure 15-12 shows the cost and demand curves for a monopolist.
-Refer to Figure 15-12.If this industry was organized as a perfectly competitive industry,the market output and market price would be
Figure 15-12 shows the cost and demand curves for a monopolist.
-Refer to Figure 15-12.If this industry was organized as a perfectly competitive industry,the market output and market price would be (Multiple Choice)
4.9/5 (68)
(68) Merger guidelines developed by the Antitrust Division of the U.S.Department of Justice use four-firm concentration ratios as measures of concentration.
(True/False)
4.9/5 (87)
(87) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)