



 Chat with AI
Exam 12: Competition and the Invisible Hand

Exam 1: The Big Ideas253 Questions
Exam 2: The Power of Trade and Comparative239 Questions
Exam 3: Supply and Demand249 Questions
Exam 4: Equilibrium256 Questions
Exam 5: Elasticity and Its Applications271 Questions
Exam 6: Taxes and Subsidies225 Questions
Exam 7: The Price System275 Questions
Exam 8: Price Ceilings and Floors327 Questions
Exam 9: International Trade195 Questions
Exam 10: Externalities- When the Price Is Not Right273 Questions
Exam 11: Costs and Profit Maximization Under Competition217 Questions
Exam 12: Competition and the Invisible Hand144 Questions
Exam 13: Monopoly233 Questions
Exam 14: Price Discrimination262 Questions
Exam 15: Oligopoly and Game Theory218 Questions
Exam 16: Competing for Monopoly160 Questions
Exam 17: Monopolistic Competition and Advertising113 Questions
Exam 18: Labor Markets262 Questions
Exam 19: Public Goods and the Tragedy of the Commons244 Questions
Exam 20: Political Economy and Public Choice306 Questions
Exam 21: Economics, Ethics, and Public Policy241 Questions
Exam 22: Managing Incentives263 Questions
Exam 23: Stock Markets and Personal Finance271 Questions
Exam 24: Price Discrimination151 Questions
Exam 25: Consumer Choice145 Questions
Select questions type


Use the following to answer questions:
Figure: Light Bulbs 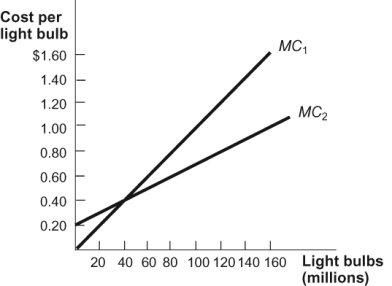 -(Figure: Light Bulbs) What price of light bulbs would induce the firms in this diagram to minimize total production costs while maintaining the same total output?
 (Multiple Choice)
4.9/5  (93)
(93) Consider two farms. Farm 1 produces the first bushel for $5 each, but the marginal cost rises gradually as the quantity increases. Farm 2 produces the first bushel for $7, but marginal cost also rises gradually as the quantity increases. With a market price of $10 a bushel, how should production be allocated between these two farms?
(Multiple Choice)
4.9/5 (75)
(75) Suppose there are two firms in an industry (Farm 1 and Farm 2). For every level of output, Farm 1 has higher marginal cost of production than Farm 2. Would it ever make sense for Farm 1 to produce in this industry? Explain.
(Essay)
4.8/5 (94)
(94) Which of these equations describes the Invisible Hand Property 1 regarding the minimization of total industry costs?
(Multiple Choice)
4.8/5 (82)
(82) If a firm has revenues of $100, explicit costs of $50, and implicit costs of $50, its economic profit is:
(Multiple Choice)
4.7/5 (77)
(77) "[I]n capitalist reality as distinguished from its textbook picture, it is not that kind of competition which counts but the competition from the new commodity, the new technology, the new source of supply, the new type of organization...competition which commands a decisive cost or quality advantage and which strikes not at the margins of the profits and the outputs of the existing firms but at their foundations and their very lives." This process is called:
(Multiple Choice)
4.8/5 (82)
(82) Consider two farms. Farm 1 produces unlimited bushels for a cost of $5 each. Farm 2 produces unlimited bushels for a cost of $7 each. How should production be allocated between these two farms?
(Multiple Choice)
4.9/5 (91)
(91) If the marginal cost of production at Firm 1 is less than the marginal cost of production at Firm 2 but the overall costs of production are lower on average at Firm 2, then:
(Multiple Choice)
4.8/5 (81)
(81) If firms do not coordinate with each other, it is hard for free markets to equalize marginal costs of production across firms.
(True/False)
5.0/5 (85)
(85) Which of the following best illustrates the elimination principle?
(Multiple Choice)
4.8/5 (83)
(83) In markets for public goods, the invisible hand concept does not work in society's best interest.
(True/False)
5.0/5 (98)
(98) Explain the term creative destruction. In particular, explain what is being "created" and what is being "destroyed."
(Essay)
4.9/5 (77)
(77) If the presence of externalities clouds the signals that prices give in respect to costs and benefits,:
(Multiple Choice)
4.7/5 (87)
(87) Stating that marginal revenue equals price is equivalent to saying that marginal cost equals price for the profit maximizing quantity.
(True/False)
4.9/5 (80)
(80) A small island nation produces only boxes of macaroni and cheese, most of which it sells in the export market. The world price per box is $10, regardless of the quantity exported. The nation has three macaroni and cheese factories, each of which varies in efficiency and each has rising marginal costs. To profit the most as a country, what would this nation do?
(Multiple Choice)
4.9/5 (84)
(84) According to the elimination principle, firms enter a market when ______ and exit a market when ______.
(Multiple Choice)
4.9/5 (101)
(101) Suppose that Sandy owns a farm in North Carolina and Pat owns a farm in Iowa, and Sandy's farm is generally more productive than Pat's. If both Sandy and Pat sell their corn in the same market, Sandy should produce the output at the marginal cost that is:
(Multiple Choice)
4.7/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)