



 Chat with AI
Exam 12: Competition and the Invisible Hand

Exam 1: The Big Ideas253 Questions
Exam 2: The Power of Trade and Comparative239 Questions
Exam 3: Supply and Demand249 Questions
Exam 4: Equilibrium256 Questions
Exam 5: Elasticity and Its Applications271 Questions
Exam 6: Taxes and Subsidies225 Questions
Exam 7: The Price System275 Questions
Exam 8: Price Ceilings and Floors327 Questions
Exam 9: International Trade195 Questions
Exam 10: Externalities- When the Price Is Not Right273 Questions
Exam 11: Costs and Profit Maximization Under Competition217 Questions
Exam 12: Competition and the Invisible Hand144 Questions
Exam 13: Monopoly233 Questions
Exam 14: Price Discrimination262 Questions
Exam 15: Oligopoly and Game Theory218 Questions
Exam 16: Competing for Monopoly160 Questions
Exam 17: Monopolistic Competition and Advertising113 Questions
Exam 18: Labor Markets262 Questions
Exam 19: Public Goods and the Tragedy of the Commons244 Questions
Exam 20: Political Economy and Public Choice306 Questions
Exam 21: Economics, Ethics, and Public Policy241 Questions
Exam 22: Managing Incentives263 Questions
Exam 23: Stock Markets and Personal Finance271 Questions
Exam 24: Price Discrimination151 Questions
Exam 25: Consumer Choice145 Questions
Select questions type


Normal profits in a competitive industry refer to positive long-run profits.
(True/False)
4.9/5  (95)
(95) There is a tendency for economic profit in all competitive industries to go to zero.
(True/False)
4.9/5 (73)
(73) The elimination principle, a general feature of competitive markets, tells us that:
(Multiple Choice)
4.9/5 (80)
(80) Use the following to answer questions:
Figure: Marginal Costs 1 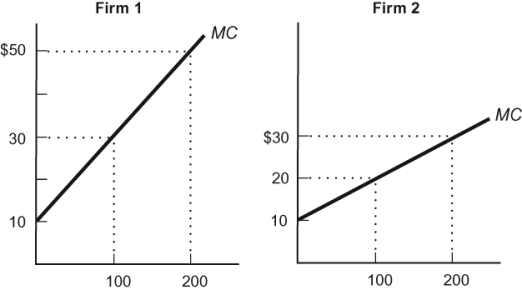 -Figure: Marginal Costs 2
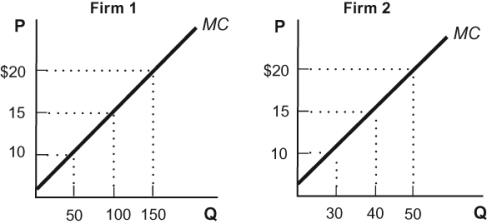 This figure shows the production costs of two firms that produce bird feeders. If these two firms represent total production in the industry, how should they allocate the production of 200 bird feeders to minimize costs?
-Figure: Marginal Costs 2 This figure shows the production costs of two firms that produce bird feeders. If these two firms represent total production in the industry, how should they allocate the production of 200 bird feeders to minimize costs? (Multiple Choice)
4.7/5 (74)
(74) If a firm has revenues of $125, explicit costs of $25, and implicit costs of $50, then its economic profit is:
(Multiple Choice)
4.7/5 (78)
(78) Which of the following best help entrepreneurs identify low-value industries versus high-value industries?
(Multiple Choice)
4.9/5 (66)
(66) When resources move from a low-profit industry into a high-profit industry,:
(Multiple Choice)
4.7/5 (66)
(66) Perfectly price discriminating monopolists earn ______ profits.
(Multiple Choice)
4.8/5 (72)
(72) In a competitive market, the amount of a good produced is such that social surplus is:
(Multiple Choice)
5.0/5 (65)
(65) Which of the following factors cause markets to be dynamic?
I. changes in tastes
II. changes in technology
III. new idea development
(Multiple Choice)
4.8/5 (83)
(83) For a competitive firm, which of the following conditions describes the profit maximization condition?
I. P = MC
II. MR = MC
III. TR = TC
(Multiple Choice)
4.8/5 (80)
(80) Since a competitive firm sets MR = P to determine all quantities in the short run, we can conclude that:
(Multiple Choice)
4.7/5 (71)
(71) The following are marginal cost curves for selling chicken in a Mom & Pop (MCM) store and in a Big-Box retailer (MCB).
MCM = 2 + 2QM
MCB = 4 + QB
If there are 6 total chickens being sold, how many chickens does each firm sell?
(Multiple Choice)
4.9/5 (78)
(78) If a firm has revenues of $100, explicit costs of $50, and implicit costs of $50, then its accounting profit is:
(Multiple Choice)
4.9/5 (88)
(88) In markets lacking competition, the invisible hand concept works in society's best interest.
(True/False)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)