



 Chat with AI
Exam 12: Competition and the Invisible Hand

Exam 1: The Big Ideas253 Questions
Exam 2: The Power of Trade and Comparative239 Questions
Exam 3: Supply and Demand249 Questions
Exam 4: Equilibrium256 Questions
Exam 5: Elasticity and Its Applications271 Questions
Exam 6: Taxes and Subsidies225 Questions
Exam 7: The Price System275 Questions
Exam 8: Price Ceilings and Floors327 Questions
Exam 9: International Trade195 Questions
Exam 10: Externalities- When the Price Is Not Right273 Questions
Exam 11: Costs and Profit Maximization Under Competition217 Questions
Exam 12: Competition and the Invisible Hand144 Questions
Exam 13: Monopoly233 Questions
Exam 14: Price Discrimination262 Questions
Exam 15: Oligopoly and Game Theory218 Questions
Exam 16: Competing for Monopoly160 Questions
Exam 17: Monopolistic Competition and Advertising113 Questions
Exam 18: Labor Markets262 Questions
Exam 19: Public Goods and the Tragedy of the Commons244 Questions
Exam 20: Political Economy and Public Choice306 Questions
Exam 21: Economics, Ethics, and Public Policy241 Questions
Exam 22: Managing Incentives263 Questions
Exam 23: Stock Markets and Personal Finance271 Questions
Exam 24: Price Discrimination151 Questions
Exam 25: Consumer Choice145 Questions
Select questions type


The marginal cost of producing the first three bushels of corn on Farm 1 is $1.00, $1.25, and $1.33, respectively. For Farm 2, the marginal cost of producing the first three bushels of corn is $0.90, $1.15, and $1.30. Three bushels should be produced if the market price is $1.15 per bushel.
(True/False)
4.7/5  (76)
(76) The long-run level of profit is the same in each perfectly competitive industry.
(True/False)
4.9/5 (74)
(74) A free market can naturally allocate production across firms in an industry to minimize total costs due to:
(Multiple Choice)
4.9/5 (77)
(77) What happens in a competitive industry when more firms enter?
(Multiple Choice)
4.8/5 (69)
(69) Use the following to answer questions:
Figure: Light Bulbs 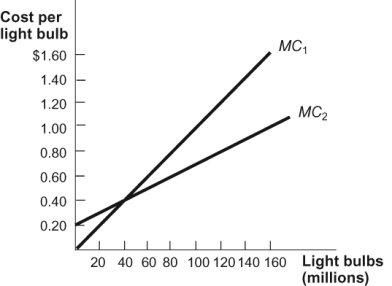 -(Figure: Light Bulbs) In this diagram, Firm 1 (MC1) and Firm 2 (MC2) are each making 100 million light bulbs. How many light bulbs should each firm make to minimize total production costs while maintaining the same total output?
 (Multiple Choice)
4.9/5 (73)
(73) If P > AC in competitive markets, firms enter the market until P = AC.
(True/False)
4.9/5 (91)
(91) In a competitive industry, if the marginal cost of Factory 1 is higher than that of Factory 2, in the short run:
(Multiple Choice)
4.8/5 (82)
(82) A small island nation produces only boxes of macaroni and cheese, most of which it sells in the export market. The world price per box is $10, regardless of the quantity exported. The nation has three macaroni and cheese factories, each of which varies in efficiency, but it's impossible for the government to determine each factory's marginal cost. To profit the most as a country, what should this nation's government do?
(Multiple Choice)
4.8/5 (83)
(83) Explain how market entry affects the profit level of a competitive firm.
(Essay)
4.7/5 (88)
(88) Which of the following statements is TRUE regarding profit maximization in competitive markets?
I. When all firms pursue profits, none of them achieve profits.
II. When all firms pursue profits, only the most innovative will achieve profits.
III. Production is divided in such a way that total costs of production are minimized.
(Multiple Choice)
4.8/5 (90)
(90) Figure: Two Farms 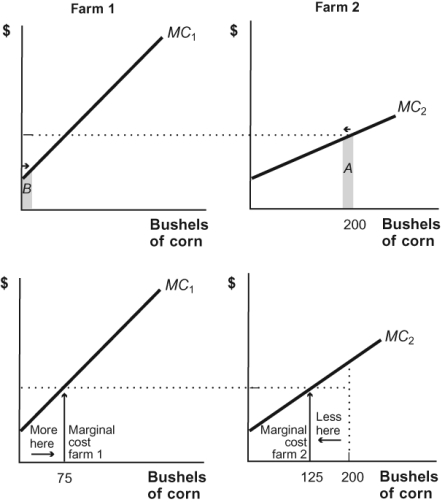 Refer to the figure. If a farmer owns two farms, Farm 1 and Farm 2, and is under contract to produce 400 bushels of corn for a food processor, should the farmer produce 200 bushels of corn from each farm as shown in this diagram?
 (Multiple Choice)
4.8/5 (65)
(65) If an industry is highly profitable, it is an indication that:
(Multiple Choice)
5.0/5 (76)
(76) If a firm has revenues of $200, explicit costs of $100, and implicit costs of $100, then its economic profit is:
(Multiple Choice)
4.8/5 (76)
(76) A central planner can never allocate output across firms in such a way as to minimize the total costs of production.
(True/False)
5.0/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)