



 Chat with AI
Exam 15: Exempt Entities

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Is there a materiality exception associated with the unrelated business income tax?
(Essay)
4.8/5  (84)
(84) What is the purpose of the "broadly supported" exception for an exempt organization being classified as a private foundation?
(Essay)
4.9/5 (74)
(74) All exempt organizations which are subject to the unrelated business income tax must file Form 990-T (Exempt Organization Business Income Tax Return).
(True/False)
4.9/5 (75)
(75) Define average acquisition indebtedness with respect to debt-financed property.
(Essay)
4.9/5 (83)
(83) A § 501(c)(3) organization exchanges its membership lists with another exempt organization. What are the Federal income tax consequences?
(Essay)
4.9/5 (79)
(79) Qualified state tuition programs are exempt from Federal income tax under § 501(c)(3).
(True/False)
4.9/5 (78)
(78) All bona-fide churches generally are exempt from Federal income tax.
(True/False)
5.0/5 (75)
(75) An exempt organization owns a building for which its adjusted basis is $100,000 at the beginning of the year and $90,000 at the end of the year. One-half of the ground floor is leased to a commercial venture for $10,000 per year. The remainder of the first floor and all of the second floor are used by the exempt organization in carrying out its mission. When the exempt organization constructed the building 20 years ago, it incurred a mortgage of $150,000. The final payment of this mortgage was made in December of the current year. The average acquisition indebtedness for the current year is $30,000. Determine to what extent the building is debt-financed property, the amount of debt-financed income, and the portion of debt-financed income that is treated as unrelated business income.
The building is not classified as debt-financed property if substantially all (at least 85%) of the use is for the achievement of the exempt purpose of the exempt organization. Since only 75% of the building's usage satisfies this requirement, 25% of the building is classified as debt-financed property.
(Essay)
4.9/5 (75)
(75) City, Inc., an exempt organization, has included among other amounts the following in calculating net unrelated business income of $500,000.
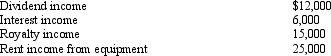
(Essay)
4.8/5 (82)
(82) A profit-related activity of an exempt organization avoids the unrelated business income tax if greater than 75% of the merchandise sold had been received as a contribution.
(True/False)
5.0/5 (88)
(88) What are the excise taxes imposed on private foundations, and why are they imposed?
(Essay)
4.9/5 (80)
(80) 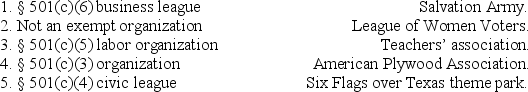
While the major objective of the Federal income tax law is to raise revenue, social considerations and economic objectives also affect the tax law.
(True/False)
4.7/5 (78)
(78) Hope, Inc., an exempt organization, owns a factory building that it leases to a taxable corporation for $150,000 per year. Related expenses for Hope are $40,000. Hope's average acquisition indebtedness on the building is $500,000 and the average adjusted basis is $750,000. Calculate Hope's unrelated debt-financed income and expenses. Then indicate the effect of these items on unrelated business taxable income.
(Essay)
4.8/5 (63)
(63) What are intermediate sanctions and to what types of exempt organizations do they apply?
(Essay)
4.8/5 (83)
(83) The unrelated business income tax (UBIT) is designed to treat the entity as if it were subject to the corporate income tax on its unrelated business taxable income, with the highest corporate tax rate (35%) applying.
(True/False)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)