



 Chat with AI
Exam 15: Exempt Entities

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


Spirit, Inc., a § 501(c)(3) organization, is classified as a private foundation. It has investment income of $100,000. Calculate Spirit's tax on its investment income.
(Essay)
4.8/5  (82)
(82) An exempt organization that otherwise would be classified as an unrelated trade or businesses will not be subject to the unrelated business income tax if the individuals performing substantially all the work of the trade or business do so without compensation.
(True/False)
4.8/5 (73)
(73) Nice, Inc., a § 501(c)(3) organization, inherited 100% of the stock of Aggressive, Inc., a for-profit entity, at the beginning of the year. Although Nice plans on selling the stock of Aggressive, a buyer has not yet been located. Aggressive's taxable income for the year is $900,000. Aggressive distributed a dividend of $525,000 to Nice at the beginning of December. Determine the tax consequences for the taxable income and the dividend payment:
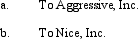
(Essay)
5.0/5 (77)
(77) What income and activities are not subject to the feeder organization rules?
(Essay)
4.8/5 (82)
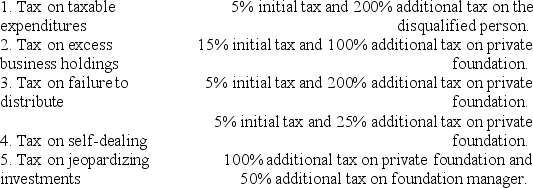
(82) For each of the following taxes which are imposed on private foundations, match the appropriate initial tax or additional tax.
(Essay)
4.9/5 (85)
(85) If an exempt organization is required to file an annual information return, on what form is it filed?
(Essay)
4.9/5 (75)
(75) The activity of exchanging with or renting to other exempt organizations the exempt organization's donor or membership list is not an unrelated trade or business.
(True/False)
4.8/5 (74)
(74) How can an exempt organization, otherwise classified as a private foundation, avoid private foundation status?
(Essay)
4.7/5 (89)
(89) Health, Inc., a § 501(c)(3) exempt organization, engages in an excess benefit transaction. The amount of the excess benefit is $300,000. For the organization management, the participation in the excess benefit transaction was not willful and was due to reasonable cause. Calculate the amount of the excise tax (first-level tax) imposed under the intermediate sanctions provision.
(Essay)
4.8/5 (77)
(77) Well, Inc., a private foundation, makes a speculative investment of $750,000 that puts the foundation assets at risk. Calculate the tax on jeopardizing investments. Assume that corrective action is taken so that the additional tax does not apply.
(Essay)
4.9/5 (84)
(84) Revenue generated by an exempt organization from the distribution of low-cost items is not income from an unrelated trade or business.
(True/False)
4.8/5 (94)
(94) The due date for both Form 990 (Return of Organization Exempt from Income Tax) and Form 990-PF (Return of Private Foundation) is the fifteenth day of the fifth month after the end of the taxable year.
(True/False)
4.7/5 (76)
(76) An organization that is a for-profit entity can partially qualify for exempt status.
(True/False)
4.9/5 (74)
(74) The tax consequences to a donor of making a charitable contribution to an exempt organization classified as a private foundation may be less favorable than the tax consequences to a donor of making a charitable contribution to an exempt organization that is not classified as a private foundation.
(True/False)
4.9/5 (78)
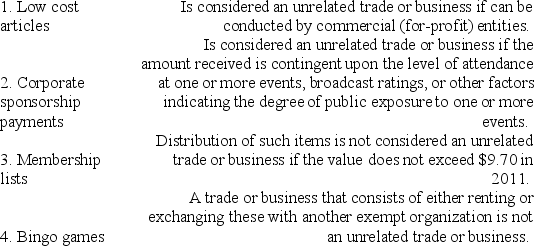
(78) 
Links, Inc., an exempt organization whose mission is to aid marriages threatened by golf, contributes $100,000 to Couples, Inc., an exempt organization which provides counseling to dysfunctional marriages. Links, Inc., has net UBTI (excluding any modifications associated with charitable contributions) of $800,000. Assuming that the $100,000 contribution has been deducted in calculating net UBTI, determine the amount of any further adjustment in calculating UBTI.
(Essay)
4.8/5 (66)
(66) Robin, Inc., an exempt organization, acquired a building for $400,000 which it will lease to XYZ, Inc., for $40,000 annually. To finance the acquisition of the building, Robin secures a mortgage on it of $250,000. Advise Robin as to whether it has any unrelated debt-financed income or deductions.
(Essay)
4.9/5 (86)
(86) Are all exempt organizations eligible to be recipients of contributions for which the donor qualifies for a charitable contribution deduction?
(Essay)
4.9/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)