



 Chat with AI
Exam 15: Exempt Entities

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


One of the requirements for an exempt organization being classified as an unrelated trade or business is the "not substantially related" requirement. That is, the trade or business is not substantially related to the exempt purpose of the organization. How can an exempt organization avoid satisfying this requirement?
(Essay)
4.9/5  (79)
(79) Which of the following requirements must be satisfied for a bingo game to be classified as not being an unrelated trade or business?
(Multiple Choice)
4.9/5 (91)
(91) The excise tax imposed on private foundations for excess business holdings is imposed on investments that enable the private foundation to control publicly-held rather than privately-held businesses.
(True/False)
4.9/5 (79)
(79) Warmth, Inc., a private foundation, makes an expenditure of $800,000 that should not be made by a private foundation. Calculate the tax on taxable expenditures. Assume that corrective action is taken so that the additional tax does not apply.
(Essay)
4.7/5 (66)
(66) If an exempt organization owns a feeder organization, the exempt organization is not taxed on the profits of the feeder organization under the unrelated business income tax (UBIT) rules.
(True/False)
5.0/5 (80)
(80) Which of the following are exempt organizations to which contributions made are eligible for the charitable contribution deduction?
(Multiple Choice)
4.8/5 (71)
(71) Which of the following are consequences of tax-exempt status?
(Multiple Choice)
4.9/5 (98)
(98) Rose, Inc., a qualifying § 501(c)(3) organization, incurs lobbying expenditures of $145,000 during the taxable year. Exempt purpose expenditures are $500,000. If Rose makes the election under § 501(h) to make lobbying expenditures on a limited basis, its tax liability resulting from the lobbying expenditures is:
(Multiple Choice)
4.9/5 (84)
(84) An intermediate sanction imposed by the IRS on an exempt organization is a lesser sanction than revocation of exempt status.
(True/False)
4.8/5 (74)
(74) A feeder organization is exempt from Federal income taxation because it carries on a trade or business for the benefit of an exempt organization and remits its profits to the exempt entity.
(True/False)
4.8/5 (69)
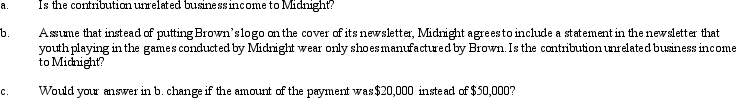
(69) Midnight Basketball, Inc., an exempt organization that organizes and conducts basketball games for youths ages 10-13, receives a $50,000 contribution from Brown Shoe Company. Midnight agrees to put Brown's logo on the cover of its monthly newsletter.
(Essay)
4.8/5 (84)
(84) A church is required to obtain IRS approval for its exempt status if its annual gross receipts exceed $25,000.
(True/False)
4.8/5 (71)
(71) The income from a bingo game conducted by an exempt organization may be unrelated business income.
(True/False)
5.0/5 (73)
(73) Which of the following is not an example of an exempt organization?
(Multiple Choice)
5.0/5 (78)
(78) If an exempt organization conducts a trade or business that is regularly carried on by the organization, it is subject to the unrelated business income tax (UBIT).
(True/False)
4.8/5 (86)
(86) Help, Inc., a tax-exempt organization, incurs lobbying expenses of $275,000 during the tax year. Help is eligible for and makes the § 501(h) lobbying expenditure election. During the year, Help spends $1,200,000 carrying out its exempt mission.
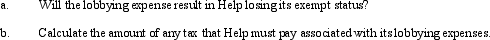
(Essay)
4.7/5 (83)
(83) Which of the following is one of the requirements that will enable mortgaged land acquired by an exempt organization for later exempt use to be excluded from debt-financed property, for purposes of the unrelated business income tax?
(Multiple Choice)
5.0/5 (84)
(84) Federal agencies exempt from Federal income tax under § 501(c)(1) are not subject to the unrelated business income tax (UBIT).
(True/False)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)