



 Chat with AI
Exam 7: Corporations: Reorganizations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


In a divisive "Type D" reorganization, the distributing corporation obtains control of the new target by exchanging some of its assets for at least 80% of the new target's outstanding stock.
(True/False)
4.9/5  (75)
(75) The distinguishing characteristic of a "Type D" reorganization is the acquiring corporation is the one transferring assets to the target corporation in exchange for a controlling interest in the target.
(True/False)
4.8/5 (77)
(77) Rabbit Corporation and Fox Corporation would like to merge into one company. Rabbit's only asset is a nontransferable chemical process that has a value of $300,000 and Rabbit has liabilities of $100,000. Fox has the manufacturing plant and experience in the production of Rabbit's chemical process. Its manufacturing plant has a value of $900,000 with a mortgage of $200,000. Which type of reorganization would be the most appropriate for Rabbit and Fox?
(Multiple Choice)
4.8/5 (67)
(67) On March 1, Cream Corporation transfers all of its assets to Coffee Corporation in exchange for 10% of its common voting stock. At the time of the reorganization, Cream has assets valued at $4 million (basis of $3 million) and its earnings and profits account shows a deficit of $650,000. Coffee's earnings and profits as of March 1 were $420,000. Due to the reorganization, Coffee has an NOL for the current year of $150,000. Coffee still declares its usual dividends of $100,000, paid on April 30, August 31, and December 31 ($300,000 of total dividends).
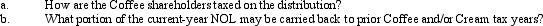
(Essay)
4.8/5 (77)
(77) Racket Corporation and Laocoon Corporation create Raccoon Corporation. Racket transfers $600,000 in assets for all of Raccoon's common stock. Racket distributes its remaining assets ($300,000) and the Raccoon common stock to its shareholder, Mia, for all of her stock in Racket (basis $950,000) and then liquidates. Laocoon receives all of the preferred stock for its $400,000 of assets. Laocoon distributes its remaining assets ($300,000) and the Raccoon preferred stock to its shareholder, Carlos, for all of his stock in Laocoon (basis $200,000) and then liquidates. How will this transaction be treated for tax purposes?
(Multiple Choice)
4.8/5 (79)
(79) The tax treatment of the parties involved in a tax-free reorganization almost exactly parallels the treatment under the ____________________ provisions. When boot is received, ____________________ may be recognized but ____________________ is not recognized.
(Short Answer)
4.9/5 (84)
(84) Pipe Corporation is very interested in acquiring all of Ore Corporation. It currently owns 30%, which it purchased 6 years ago for $250,000. Pipe is a manufacturer of plumbing pipes with assets valued at $3 million and liabilities of $1 million. Ore supplies Pipe with copper from its mines that are valued at $4 million with $3 million in mortgages. Pipe has negotiated a restructuring with Ore's management. Pipe is concerned about potential environmental issues from the strip mining used by Ore and feels it needs liability protection. Given these facts, what type of reorganization would you suggest for Pipe and Ore?
(Essay)
4.7/5 (81)
(81) A more than 50 percentage point ownership shift will evoke the § 382 limitation.
(True/False)
4.8/5 (87)
(87) The Federal income tax treatment of a corporate restructuring is an extension of allowing entities to form without taxation.
(True/False)
5.0/5 (82)
(82) Burl Corporation has assets with a value of $500,000 (basis of $300,000) and liabilities of $350,000. Wood Corporation is considering merging with Burl by exchanging 30% of its voting stock and $50,000 cash for Burl.
(Multiple Choice)
4.9/5 (81)
(81) An equity structure shift occurs when a(n) ____________________ causes an ownership change of ____________________ percentage-points for any common shareholders owning at least 5%. A sale or issuance of stock can cause a(n) ____________________ to take place.
(Short Answer)
4.9/5 (86)
(86) Since the ____________________ reorganization precludes the use of boot, gain is not recognized in this type of reorganization. In this reorganization, a ____________________ relationship between the acquiring and target corporations is created.
(Short Answer)
4.9/5 (83)
(83) GreenCo transfers $400,000 of its common voting stock and $50,000 cash to CurryCo in exchange for 80% of CurryCo's assets. CurryCo uses all of its remaining assets and the cash received from GreenCo to pay its liabilities. CurryCo then distributes the GreenCo stock to its shareholders in exchange for all of their shares of CurryCo. Lastly, CurryCo liquidates. This restructuring qualifies as a:
(Multiple Choice)
4.8/5 (84)
(84) The "Type C" reorganization requires that at least ____________________ percent of the value of the target's assets be acquired with ____________________ stock.
(Short Answer)
4.9/5 (83)
(83) For a capital restructuring to qualify as a "Type E," there must be at least a 50% change in the common stock ownership.
(True/False)
4.9/5 (79)
(79) The "Type F" corporate reorganization includes changes in name, location, and changing from a taxable entity to any flow-through entity.
(True/False)
4.9/5 (82)
(82) The treatment of corporate reorganizations is similar to like-kind exchanges.
(True/False)
4.9/5 (89)
(89) For the "Type G" reorganization, the continuity of interest test is more stringent than for other reorganizations, because the corporation is insolvent and the owners need to be protected.
(True/False)
4.9/5 (69)
(69) Red Corporation redeems all of its common and preferred stock. Red then exchanges this redeemed stock with Blue Corporation for 40% of Blue's voting common stock. The Blue stock is distributed to the Red shareholders. After the transaction, both Red and Blue corporations still exist. The former Red shareholders are now shareholders of Blue. This transaction qualifies as a(n):
(Multiple Choice)
5.0/5 (77)
(77) The year in which the ownership shift occurs for a corporation, the NOL carryforward is limited not only by the § 382 annual limitation, but also by the percentage of the year remaining.
(True/False)
4.9/5 (67)
(67) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)