



 Chat with AI
Exam 7: Corporations: Reorganizations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


The ____________________ provides a restriction on the amount of tax attributes that can be carried over from the target to the acquiring corporation after an ownership shift occurs.
(Short Answer)
4.9/5  (82)
(82) A shareholder bought 2,000 shares of Zee Corporation for $90,000 several years ago. When the stock is valued at $200,000, Zee redeems these shares in exchange for 6,000 shares of Yea Corporation stock. This transaction meets the requirements of § 368. Which of the following statements is true with regard to this transaction?
(Multiple Choice)
4.9/5 (93)
(93) ScottishCo is owned by Gordon Bryson and his four nieces and nephews. Gordon owns all the voting stock. He wants to relinquish control; accordingly, ScottishCo redeems all of Gordon's voting common stock and issues him preferred stock and $50,000 in bonds. The nonvoting preferred shares owned by the nieces and nephew are exchanged for voting common stock. Which of the following statements is correct?
(Multiple Choice)
4.8/5 (85)
(85) The ____________________ doctrine treats several transactions as if they were one transaction when they are all integrated. The ____________________ doctrine ensures that the restructuring has a purpose beyond tax avoidance or evasion.
(Short Answer)
5.0/5 (73)
(73) Which of the following is not a requirement for receiving tax-free treatment for a corporate reorganization?
(Multiple Choice)
4.8/5 (76)
(76) Without evidence to the contrary, the IRS views transactions occurring within one year of a reorganization as part of the restructuring.
(True/False)
4.9/5 (97)
(97) The "Type F" is the mere change in ____________________, ____________________, or _________________________.
or
(Essay)
4.8/5 (70)
(70) In a ____________________ divisive reorganization the original distributing corporation disappears. In a ____________________ divisive reorganization the shareholders do not give up any of their original corporation stock to receive stock in the new corporation, whereas in a ____________________ stock in the original is exchanged for stock in the new corporation.
(Short Answer)
4.9/5 (77)
(77) For corporate reorganizations, the tax laws should be considered while planning the structure of the reorganization.
(True/False)
4.9/5 (81)
(81) One of the tenets of U.S. tax policy is to encourage business development. Which of the following Code sections does not support this tenet?
(Multiple Choice)
4.9/5 (74)
(74) Discuss the influence of step transaction, sound business purpose, continuity of business enterprise, and continuity of interest doctrines on tax-free corporate reorganizations.
(Essay)
4.8/5 (74)
(74) Which of the following statements is false regarding the tax benefits from a loss corporation's carryovers that are taken in the current year?
(Multiple Choice)
4.7/5 (82)
(82) An exchange of common stock for preferred stock or bonds for preferred stock can qualify as a "Type E" reorganization.
(True/False)
4.7/5 (79)
(79) Present Value Tables needed for this question. Sauce Corporation is very interested in acquiring a controlling interest Pear Corporation, to obtain operating efficiencies. Sauce currently owns 30% of Pear, which it bought six years ago for $600,000. Sauce is a fruit processor with assets valued at $3 million and liabilities of $1 million. Pear supplies Sauce with fruit from its orchards that are valued at $4 million with $3 million in mortgages. Pear also has $60,000 in unused general business credits. Sauce has negotiated a restructuring with most of Pear's shareholders. It will exchange 1 share of its stock for 2 shares of Pear. Pear's founder, who own 10% of the outstanding common stock, is not willing to relinquish her stock and thus, Sauce cannot own 100% of Pear.
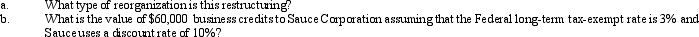
(Essay)
4.9/5 (71)
(71) Mars Corporation merges into Jupiter Corporation by exchanging all of its assets for 300,000 shares of Jupiter stock valued at $2 per share and $100,000 cash. Wanda, the sole shareholder of Mars, surrenders her Mars stock (basis $900,000) and receives all of the Jupiter stock transferred to Mars plus the $100,000. How does Wanda treat this transaction on her tax return?
(Multiple Choice)
4.9/5 (83)
(83) Compare an acquisitive "Type D" reorganization with the "Type C" reorganization.
(Essay)
4.8/5 (74)
(74) Compare the consideration that can be used in "Type A," "Type B," and "Type C" reorganizations.
(Essay)
4.7/5 (74)
(74) The continuity of interest requires that all target shareholders receive some acquiring stock.
(True/False)
4.9/5 (84)
(84) One of the tenets of the U.S. tax policy is to ____________________ business development. As an extension of this concept, corporate restructurings are given ____________________ treatment.
(Short Answer)
4.8/5 (76)
(76) To qualify as a tax-free reorganization, a corporate restructuring must meet not only the specific requirements of § 368 but also four general requirements. These four requirements are: ____________________, ____________________, ____________________, and _________________________. In addition, the ____________________ doctrine should not apply to the reorganization.
or
(Essay)
4.9/5 (74)
(74) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)