



 Chat with AI
Exam 7: Corporations: Reorganizations

Exam 1: Understanding and Working With the Federal Tax Law74 Questions
Exam 2: Corporations: Introduction and Operating Rules113 Questions
Exam 3: Corporations: Special Situations111 Questions
Exam 4: Corporations: Organization and Capital Structure93 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions89 Questions
Exam 6: Corporations: Redemptions and Liquidations112 Questions
Exam 7: Corporations: Reorganizations121 Questions
Exam 8: Consolidated Tax Returns145 Questions
Exam 9: Taxation of International Transactions159 Questions
Exam 10: Partnerships: Formation, Operation, and Basis100 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations97 Questions
Exam 12: S: Corporations157 Questions
Exam 13: Comparative Forms of Doing Business143 Questions
Exam 14: Taxes on the Financial Statements87 Questions
Exam 15: Exempt Entities151 Questions
Exam 16: Multistate Corporate Taxation160 Questions
Exam 17: Tax Practice and Ethics153 Questions
Exam 18: The Federal Gift and Estate Taxes173 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates156 Questions
Select questions type


In an acquisitive "Type D" reorganization, substantially all of the acquiring corporation's assets must be transferred to the target corporation for stock amounting to at least 50 percent of the total acquiring stock.
(True/False)
4.8/5  (73)
(73) In which type of divisive corporate reorganization do the shareholders receive stock in another corporation without relinquishing any of their stock in the original corporation?
(Multiple Choice)
4.9/5 (78)
(78) Manx Corporation transfers 40% of its stock and $50,000 in cash to Somali Corporation for $500,000 of assets and all $200,000 of its liabilities. Somali exchanges the Manx stock, cash, and its remaining $100,000 of assets with its shareholders for all of their stock in Somali. After the exchange, Somali liquidates. The exchange qualifies as what type of transaction?
(Multiple Choice)
4.8/5 (78)
(78) The gains shareholders recognize as a part of a corporate reorganization may be treated a dividend to the extent of the corporation's earnings and profits.
(True/False)
4.8/5 (69)
(69) Liabilities generally are not considered boot in corporate reorganizations, except in an acquisitive "Type D" when cash or other property is also used in the transaction.
(True/False)
4.8/5 (74)
(74) Present Value Tables needed for this question. Tony is the sole shareholder of Create Corporation. Tony is a chemical engineer and has been working hard to create a unique product but has been unsuccessful. Thus, Create has accumulated an NOL of $240,000. This year she finally finds the right combination for a new cleaning product. Predicting that Create will be very profitable next year, Create borrows $250,000 to pay Tony the salary she rightly deserves. Next year, Create does become profitable, earning $100,000 before application of carryovers. Mega Corporation, a huge ($50 million value, 35% tax bracket) competitor, offers to purchase the patent from Tony for $750,000. Knowing that the Create's NOL should be useful to Mega, Tony suggests a restructuring where she receives $500,000 in Mega stock, Mega assumes all of Create's liabilities ($250,000), plus $75,000 cash for the NOL. Mega counter offers with cash for the NOL (to be determined), and $750,000 of stock. It will not assume any liabilities. How much would be the maximum cash offered by Mega for the NOL, assuming that Mega uses an 11% discount factor and the Federal long-term tax-exempt rate is 4%? If Tony accepts Mega's offer, what type of reorganization, if any, is this restructuring?
Mega should not pay more than $54,033 for the NOL. Use a "Type C" reorganization.
(Essay)
5.0/5 (85)
(85) The "Type B" reorganization requires a continuity of business interest. Therefore, the acquiring corporation must obtain at least 40% of target corporation's stock through the reorganization.
(True/False)
4.8/5 (86)
(86) Ula purchased stock in Purple, Inc., 6 years ago for $150,000. Purple has assets with a value of $180,000 (basis of $75,000) and liabilities of $25,000. Purple transfers most of its assets and all of its liabilities to White Corporation in exchange for $140,000 of White common stock. Purple distributes the White stock and its remaining $15,000 cash to Ula in exchange for all of her Purple stock. Purple then liquidates. How will this transaction be treated for tax purposes?
(Multiple Choice)
4.7/5 (71)
(71) Explain how the tax treatment for parties involved in a tax-free reorganization almost exactly parallels the treatment under the like-kind exchange provisions of § 1031.
(Essay)
4.8/5 (79)
(79) Lyon has 100,000 shares outstanding that are worth $10 per share. It uses 32% of its stock plus $80,000 to acquire Zebra Corporation in a "Type A" reorganization. Zebra's assets are valued at $400,000 and its accumulated earnings and profits are $25,000 at the time of the reorganization. The Lyon shares and cash are distributed to the Zebra shareholders as follows. Jake (owning 62.5% of Zebra) receives 18,000 shares (value $180,000) and $70,000. Kara (owning 37.5% of Zebra) receives 14,000 shares (value $140,000) and $10,000. Jake and Kara each recognize gains to the extent of the cash they received. What is the character of Jake's and Kara's gains?
(Essay)
4.8/5 (82)
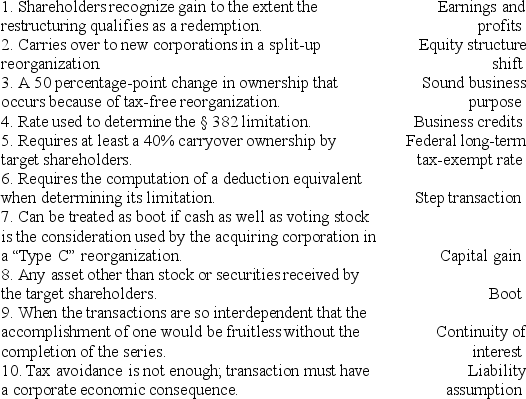
(82) Match the following items with the statements below. Terms may be used more than once.
(Short Answer)
4.9/5 (75)
(75) The Long Corporation has $500,000 of assets (basis of $350,000) and liabilities of $125,000. ShortCo acquires Long's assets and $100,000 of liabilities by exchanging $400,000 of its voting stock. Long distributes the ShortCo stock and remaining liabilities to its shareholder in exchange for her Long stock (basis of $275,000) and then it liquidates. Which, if any, of the following statements is correct?
(Multiple Choice)
4.8/5 (86)
(86) Discuss the treatment of accumulated earnings and profits (E & P) in a corporate reorganization when both corporations have positive E & P and when the target corporation has a negative E & P.
(Essay)
4.9/5 (69)
(69) If stockholders of the corporations involved in a tax-free reorganization receive ____________________ in addition to stock, they may recognize gain. The character of the gain is either ____________________ or ____________________.
or
or
or
(Essay)
4.7/5 (77)
(77) Weaver Corporation has net assets valued at $800,000 and an NOL of $250,000. On September 30 of the current year, Weaver is acquired by Loom Corporation, a calendar year taxpayer, in a restructuring qualifying as a tax-free reorganization. Weaver shareholders receive 30% of Loom's shares in exchange for all of their Weaver stock. Assuming that the Federal long-term tax-exempt rate is 8%, what is the maximum amount of Weaver's NOL available to Loom in the current year?
(Multiple Choice)
4.8/5 (82)
(82) A tax avoidance motive is essential in establishing a sound business purpose.
(True/False)
4.7/5 (75)
(75) Yoko purchased 10% of Toyger Corporation's stock six years ago for $70,000. In a transaction qualifying as a "Type C" reorganization, Yoko received $50,000 cash and 8% of Angora Corporation's stock (valued at $100,000) in exchange for her Toyger stock. Prior to the reorganization, Toyger had $200,000 accumulated earnings and profits and Angora had $300,000. How does Yoko treat the exchange for tax purposes?
(Multiple Choice)
4.7/5 (66)
(66) The "Type A" corporate reorganization can run afoul of the continuity of interest doctrine more easily than a "Type C," because with a "Type A" the Code does not require that the target shareholders receive common stock of the acquiring corporation in exchange for their ownership of the target.
(True/False)
4.8/5 (87)
(87) There are several different types of corporate reorganizations allowed by the Internal Revenue Code. Provide a brief description of each type.
(Essay)
4.8/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)