



 Chat with AI
Exam 14: Firms in Competitive Markets

Exam 1: Ten Principles of Economics439 Questions
Exam 2: Thinking Like an Economist617 Questions
Exam 3: Interdependence and the Gains From Trade527 Questions
Exam 4: The Market Forces of Supply and Demand698 Questions
Exam 5: Elasticity and Its Application595 Questions
Exam 6: Supply, Demand, and Government Policies644 Questions
Exam 7: Consumers, Producers, and the Efficiency of Markets549 Questions
Exam 8: Application: The Costs of Taxation511 Questions
Exam 9: Application: International Trade493 Questions
Exam 10: Externalities524 Questions
Exam 11: Public Goods and Common Resources433 Questions
Exam 12: The Design of the Tax System551 Questions
Exam 13: The Costs of Production420 Questions
Exam 14: Firms in Competitive Markets543 Questions
Exam 15: Monopoly637 Questions
Exam 16: Monopolistic Competition587 Questions
Exam 17: Oligopoly496 Questions
Exam 18: The Markets for the Factors of Production564 Questions
Exam 19: Earnings and Discrimination490 Questions
Exam 20: Income Inequality and Poverty457 Questions
Exam 21: The Theory of Consumer Choice440 Questions
Exam 22: Frontiers of Microeconomics441 Questions
Select questions type


Table 14-1
 -Refer to Table 14-1. If the firm doubles its output from 3 to 6 units, total revenue will
 (Multiple Choice)
4.9/5  (80)
(80) The firm will make the most profits if it produces the quantity of output at which
(Multiple Choice)
4.9/5 (90)
(90) Changes in the output of a perfectly competitive firm, without any change in the price of the product, will change the firm's
(Multiple Choice)
4.9/5 (71)
(71) Table 14-10
Suppose that a firm in a competitive market faces the following revenues and costs:
 -Refer to Table 14-10. At which level of production will the firm maximize profit?
 (Multiple Choice)
4.8/5 (72)
(72) Suppose a firm operates in the short run at a price above its average total cost of production. In the long run the firm should expect
(Multiple Choice)
4.9/5 (73)
(73) The marginal firm in a competitive market will earn zero economic profit in the long run.
(True/False)
4.8/5 (78)
(78) Table 14-6
The following table presents cost and revenue information for a firm operating in a competitive industry.
 -Refer to Table 14-6. What is the average revenue when 4 units are sold?
 (Multiple Choice)
4.8/5 (92)
(92) Figure 14-11 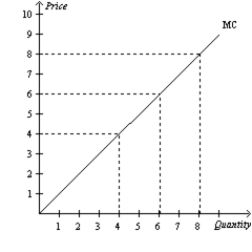 -Refer to Figure 14-11. The figure above is for a firm operating in a competitive industry. If there were eight identical firms in the industry, which of the following price-quantity combinations would be on the market supply curve?
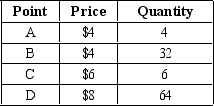
-Refer to Figure 14-11. The figure above is for a firm operating in a competitive industry. If there were eight identical firms in the industry, which of the following price-quantity combinations would be on the market supply curve? (Multiple Choice)
4.7/5 (86)
(86) Figure 14-1
Suppose that a firm in a competitive market has the following cost curves:  -Refer to Figure 14-1. If the market price is $4.00, the firm will earn
 (Multiple Choice)
4.8/5 (87)
(87) A competitive market is in long-run equilibrium. If demand decreases, we can be certain that price will
(Multiple Choice)
4.8/5 (71)
(71) When firms have an incentive to exit a competitive market, their exit will
(Multiple Choice)
4.7/5 (89)
(89) The production decisions of perfectly competitive firms follow one of the Ten Principles of Economics, which states that rational people
(Multiple Choice)
4.8/5 (79)
(79) Kate is a professional opera singer who gives voice lessons. The vocal-music industry is competitive. Kate hires a business consultant to analyze her financial records. The consultant recommends that Kate give fewer voice lessons. The consultant must have concluded that Kate's
(Multiple Choice)
4.7/5 (84)
(84) Suppose you bought a ticket to a football game for $30 and that you place a $35 value on seeing the game. If you lose the ticket, then what is the maximum price you should pay for another ticket? Assume that losing the ticket does not alter how you value it.
(Multiple Choice)
4.9/5 (78)
(78) Figure 14-10
In the figure below, panel (a) depicts the linear marginal cost of a firm in a competitive market, and panel (b) depicts the linear market supply curve for a market with a fixed number of identical firms.
 -Refer to Figure 14-10. If there are 700 identical firms in this market, what is the value of Q2?
 (Multiple Choice)
4.9/5 (90)
(90) You purchase a $30, nonrefundable ticket to a play at a local theater. Ten minutes into the show you realize that it is not a very good show and place only a $10 value on seeing the remainder of the show. Alternatively you could leave the theater and go home and watch TV or read a book. You place an $8 value on watching TV and a $12 value on reading a book.
(Multiple Choice)
4.7/5 (79)
(79) Which of the following statements best expresses a firm's profitmaximizing decision rule?
(Multiple Choice)
4.7/5 (76)
(76) Table 14-12
Bill's Birdhouses
 -Refer to Table 14-12. At what quantity does Bill maximize profits?
 (Multiple Choice)
4.9/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)