



 Chat with AI
Exam 16: Business Strategy

Exam 1: Ten Lessons From Economics149 Questions
Exam 2: Thinking Like an Economist147 Questions
Exam 3: Interdependence and the Gains From Trade153 Questions
Exam 4: The Market Forces of Supply and Demand222 Questions
Exam 5: Elasticity and Its Application181 Questions
Exam 6: Supply, Demand and Government Policies148 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets177 Questions
Exam 8: Application: The Costs of Taxation141 Questions
Exam 9: Application: International Trade161 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets200 Questions
Exam 15: Monopoly214 Questions
Exam 16: Business Strategy184 Questions
Exam 17: Competition Policy104 Questions
Exam 18: Monopolistic Competition214 Questions
Exam 19: The Markets for the Factors of Production215 Questions
Exam 20: Earnings, Unions and Discrimination206 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice161 Questions
Exam 23: Frontiers of Microeconomics120 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living52 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment59 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy64 Questions
Exam 33: Aggregate Demand and Aggregate Supply82 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment58 Questions
Exam 36: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


Table 16-4
Consider the following Duopoly game.
 -Refer to Table 16-4. If both firms follow a dominant strategy, firm A's profits (losses) will be:
 (Multiple Choice)
4.9/5  (65)
(65) Table 16-7
Consider two countries, Eudora and the Inhabit, that are engaged in an arms race. The question each country must face is whether to build new weapons or to disarm existing weapons. Each country prefers to have more arms than the other because a large arsenal gives it more influence in world affairs. But each country also prefers to live in a world safe from the other country's weapons. The table shows the possible outcomes for each decision combination.
 -Refer to Table 16-7. If Inhabit chooses to arm, the country of Eudora will:
 (Multiple Choice)
4.9/5 (87)
(87) When oligopolists cooperate, they end up producing a total quantity that is closer to the social optimum.
(True/False)
4.7/5 (83)
(83) The theory of oligopoly provides another reason that free-trade can benefit all countries for which of the following reasons? (i) as the number of firms within a given market increases, the price of the good falls
(ii) increased competition leads to lower deadweight losses
(iii) profit increases directly with competition for oligopoly firms
(Multiple Choice)
4.8/5 (86)
(86) The game that oligopolists play in trying to reach the monopoly outcome is similar to the game that the two prisoners play in the prisoners' dilemma.
(True/False)
4.7/5 (81)
(81) Table 16.6
Two firms share a common fishery. One strategy available to the firms is to fish sustainably. This maintains a healthy breeding population of fish, and keeps the price of fish relatively high. The other strategy is to overfish. This reduces the breeding population and fish prices tend to fall. The game is represented in the following table.
 -Refer to Table 16-6. If firm A uses its dominant strategy, its profit at the Nash Equilibrium will be:
 (Multiple Choice)
4.9/5 (69)
(69) Suppose a firm makes a product whose price decreases as the output increases. The firm is in a market with many other firms. It is most likely that the firm:
(Multiple Choice)
4.9/5 (79)
(79) Arming a country is a dominant strategy for each country is in an arms race.
(True/False)
4.9/5 (83)
(83) The only case where profit-maximising production decisions by firms will drive price to equal marginal cost are when:
(Multiple Choice)
4.9/5 (72)
(72) It is sometimes possible to achieve cooperation in repeated games by threatening to punish defectors.
(True/False)
4.8/5 (65)
(65) Self-interest usually dictates what kind of outcome for the players in a prisoners' dilemma game?
(Multiple Choice)
4.8/5 (77)
(77) Describe the source of tension between cooperation and self-interest in a market characterised by oligopoly. Use an example of an actual cartel arrangement to demonstrate why this tension creates instability in cartels.
(Essay)
4.9/5 (81)
(81) Oligopolies can end up looking like competitive firms if the number of firms is:
(Multiple Choice)
4.9/5 (72)
(72) As the number of firms in an oligopoly grows larger, what happens to the quantity produced? (i) it approaches the socially optimal level
(ii) it increases
(iii) it decreases
(Multiple Choice)
4.7/5 (79)
(79) During the 1990s, the members of OPEC operated independently from one another, causing the world market for crude oil to become close to a(n):
(Multiple Choice)
4.9/5 (79)
(79) Two fishing firms share a common fishery. One strategy available to the firms is to fish sustainably. This maintains a healthy breeding population of fish, and keeps the price of fish relatively high. The other strategy is to overfish. This reduces the breeding population and fish prices tend to fall. The game is represented in the following table:
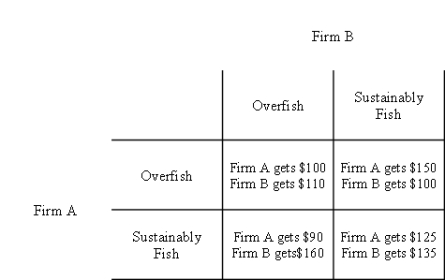 Explain what the Nash equilibrium for this game is and identify the profit each player gets at this solution. Is the Nash equilibrium the best social outcome for this problem?
 (Essay)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)