



 Chat with AI
Exam 16: Business Strategy

Exam 1: Ten Lessons From Economics149 Questions
Exam 2: Thinking Like an Economist147 Questions
Exam 3: Interdependence and the Gains From Trade153 Questions
Exam 4: The Market Forces of Supply and Demand222 Questions
Exam 5: Elasticity and Its Application181 Questions
Exam 6: Supply, Demand and Government Policies148 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets177 Questions
Exam 8: Application: The Costs of Taxation141 Questions
Exam 9: Application: International Trade161 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets200 Questions
Exam 15: Monopoly214 Questions
Exam 16: Business Strategy184 Questions
Exam 17: Competition Policy104 Questions
Exam 18: Monopolistic Competition214 Questions
Exam 19: The Markets for the Factors of Production215 Questions
Exam 20: Earnings, Unions and Discrimination206 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice161 Questions
Exam 23: Frontiers of Microeconomics120 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living52 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment59 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy64 Questions
Exam 33: Aggregate Demand and Aggregate Supply82 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment58 Questions
Exam 36: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


Perfect competition occurs when there are many firms in a market offering differentiated products.
(True/False)
4.8/5  (82)
(82) If identical products are sold by firms participating in a market, the market is which of the following? (i) perfectly competitive
(ii) an oligopoly
(iii) monopolistically competitive
(Multiple Choice)
4.8/5 (71)
(71) Describe the output and price effects that influence the profit-maximising decision faced by a firm in an oligopoly market. How does this differ from output and price effects in a monopoly market?
(Essay)
4.9/5 (76)
(76) Table 16-7
The demand for a product that is produced at zero marginal cost is reflected in the table.
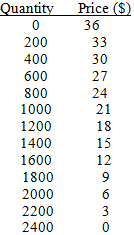 (a) What is the profit-maximising level of production for a group of oligopolistic firms that operate as a cartel?
(b) Assume that this market is characterised by a duopoly in which collusive agreements are illegal. What market price and quantity will be associated with a profit-maximising Nash equilibrium?
(c) Assume that this market is served by three identical firms that operate as independent oligopolists (no collusive agreements). What market price and quantity will be associated with a profit-maximising Nash equilibrium? How does your answer differ from that in part b above?
(a) What is the profit-maximising level of production for a group of oligopolistic firms that operate as a cartel?
(b) Assume that this market is characterised by a duopoly in which collusive agreements are illegal. What market price and quantity will be associated with a profit-maximising Nash equilibrium?
(c) Assume that this market is served by three identical firms that operate as independent oligopolists (no collusive agreements). What market price and quantity will be associated with a profit-maximising Nash equilibrium? How does your answer differ from that in part b above? (Essay)
4.9/5 (81)
(81) The logic of self-interest causes the duopoly's output level to be which of the following? (i) above the monopoly level
(ii) above the oligopoly level
(iii) below the competitive level
(Multiple Choice)
5.0/5 (90)
(90) The story of the prisoners' dilemma contains a general lesson that applies to any group trying to maintain cooperation among its members.
(True/False)
4.8/5 (92)
(92) If there are many firms participating in a market, the market is either:
(Multiple Choice)
4.9/5 (73)
(73) As the number of firms in an oligopoly market grows larger, the price will approach:
(Multiple Choice)
4.7/5 (94)
(94) *Each firm reasons that the monopoly price ($24) earns them $48 000 each (2000 tickets each). If one of them increases output by 1000, the price drops to $18 (midpoint). At 5000 tickets, the firm that drops its price earns 3000 x $18 000 = $54 000. The other firm earns
$36 000. The NE is for both firms to increase output to 3000.
-Refer to Table 16-1. Assume that there are two profit-maximising ecotourist companies operating in this market. Further assume that they are not able to collude on the price and quantity of tickets they sell. How much profit will each firm earn when this market reaches a Nash equilibrium?
(Multiple Choice)
4.8/5 (70)
(70) Consider two cigarette companies, PM Inc. and Brown Inc. If neither company advertises, the two companies split the market. If they both advertise, they again split the market, but profits are lower, since each company must bear the cost of advertising. Yet, if one company advertises while the other does not, the one that advertises attracts customers from the other.
-Refer to the information provided. What will these two companies do if they behave as individual profit maximisers?
(Multiple Choice)
4.9/5 (84)
(84) One economic example of prisoner's dilemma is overuse of a common resource like an oil-deposit.
(True/False)
4.8/5 (78)
(78) An oligopolist will increase production if the output effect is:
(Multiple Choice)
4.9/5 (83)
(83) The Nash equilibrium for a game can be a sub-optimal outcome for players when:
(Multiple Choice)
4.9/5 (68)
(68) Table 16.6
Two firms share a common fishery. One strategy available to the firms is to fish sustainably. This maintains a healthy breeding population of fish, and keeps the price of fish relatively high. The other strategy is to overfish. This reduces the breeding population and fish prices tend to fall. The game is represented in the following table.
 -Refer to Table 16-6. If firm B uses its dominant strategy, its profit at the Nash Equilibrium will be:
 (Multiple Choice)
4.9/5 (72)
(72) If an oligopolist is part of a cartel that is collectively producing at the monopoly level of output, then the oligopolist, being self-interested, will:
(Multiple Choice)
4.8/5 (76)
(76) In the absence of price-fixing, a monopoly will make more total profit than an oligopoly operating in an identical market.
(True/False)
4.7/5 (85)
(85) Table 16-3
Imagine a small town in which only two residents, Robert and John, own wells that produce water for safe drinking. Each Saturday, Robert and John work together to decide how many litres of water to pump, bring the water to town, and sell it at whatever price the market will bear. To keep things simple, suppose that Robert and John can pump as much water as they want without cost; therefore, the marginal cost of water equals zero.
The weekly town demand schedule and total revenue schedule for water are shown in the table.
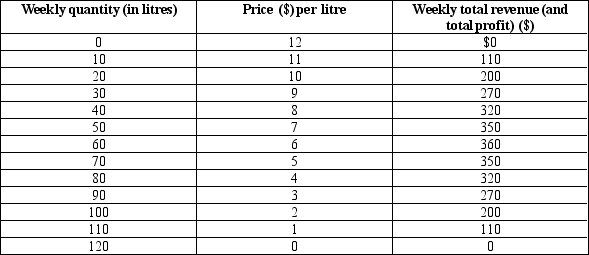 -Refer to Table 16-3. As long as Robert and John operate as a profit-maximising monopoly, what will their weekly revenue be?
 (Multiple Choice)
4.9/5 (71)
(71) The only market where firms need not to be concerned about balancing the price effect and the output effect when making production decisions is a:
(Multiple Choice)
4.9/5 (77)
(77) While on holiday in Berserkistan, you are arrested and accused of spying for Australia. You are, of course, innocent. Your captors inform you that if you confess, you will receive a sentence of two years while your co-conspirator (whom you have never heard of) will receive a sentence of 20 years. If you both confess, you will each receive a sentence of three years. You are also told that your co-conspirator is being offered the same option. You suspect that there is not enough evidence to convict you unless your alleged co-conspirator confesses. If you are risk-averse, what should you choose to do?
(Multiple Choice)
4.9/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)