



 Chat with AI
Exam 16: Business Strategy

Exam 1: Ten Lessons From Economics149 Questions
Exam 2: Thinking Like an Economist147 Questions
Exam 3: Interdependence and the Gains From Trade153 Questions
Exam 4: The Market Forces of Supply and Demand222 Questions
Exam 5: Elasticity and Its Application181 Questions
Exam 6: Supply, Demand and Government Policies148 Questions
Exam 7: Consumers, Producers and the Efficiency of Markets177 Questions
Exam 8: Application: The Costs of Taxation141 Questions
Exam 9: Application: International Trade161 Questions
Exam 10: Externalities199 Questions
Exam 11: Public Goods and Common Resources182 Questions
Exam 12: The Design of the Tax System154 Questions
Exam 13: The Costs of Production191 Questions
Exam 14: Firms in Competitive Markets200 Questions
Exam 15: Monopoly214 Questions
Exam 16: Business Strategy184 Questions
Exam 17: Competition Policy104 Questions
Exam 18: Monopolistic Competition214 Questions
Exam 19: The Markets for the Factors of Production215 Questions
Exam 20: Earnings, Unions and Discrimination206 Questions
Exam 21: Income Inequity and Poverty111 Questions
Exam 22: The Theory of Consumer Choice161 Questions
Exam 23: Frontiers of Microeconomics120 Questions
Exam 24: Measuring a Nations Income51 Questions
Exam 25: Measuring the Cost of Living52 Questions
Exam 26: Production and Growth62 Questions
Exam 27: Saving, Investment and the Financial System62 Questions
Exam 28: The Natural Rate of Unemployment59 Questions
Exam 29: The Monetary System66 Questions
Exam 30: Inflation: Its Causes and Costs74 Questions
Exam 31: Open-Economy Macroeconomics: Basic Concepts68 Questions
Exam 32: A Macroeconomic Theory of the Open Economy64 Questions
Exam 33: Aggregate Demand and Aggregate Supply82 Questions
Exam 34: The Influence of Monetary and Fiscal Policy on Aggregate Demand73 Questions
Exam 35: The Short-Run Trade-Off Between Inflation and Unemployment58 Questions
Exam 36: Five Debates Over Macroeconomic Policy38 Questions
Select questions type


Suppose a cartel collapses. The firms resume individual rather than collusive production. This outcome:
(Multiple Choice)
5.0/5  (72)
(72) Assume that the countries of Irun and Urun are the only two producers of crude oil. Further assume that both countries have entered into an agreement to maintain certain production levels in order to maximise profits. The world market for oil is represented by a downward-sloping demand curve.
-According to the information provided, as the production level deviates from the agreed-upon quantity, the total profit earned collectively by the two countries:
(Multiple Choice)
4.7/5 (69)
(69) Crude oil is supplied to the world market primarily by a few Middle Eastern countries. Such a market is an example of which of the following? (i) a monopoly market
(ii) an oligopoly market
(iii) an imperfectly competitive market
(Multiple Choice)
4.7/5 (77)
(77) Society will always be better off if the prisoners' dilemma game is repeated numerous times in an oligopoly market
(True/False)
4.9/5 (84)
(84) Table 16-7
Consider two countries, Eudora and the Inhabit, that are engaged in an arms race. The question each country must face is whether to build new weapons or to disarm existing weapons. Each country prefers to have more arms than the other because a large arsenal gives it more influence in world affairs. But each country also prefers to live in a world safe from the other country's weapons. The table shows the possible outcomes for each decision combination.
 -Refer to Table 16-7. In reality these two countries may have a hard time keeping arms levels at the social optimal level due to which of the following reasons? (i) both countries have incentives to cheat on the agreement
(ii) they may have trouble agreeing on the level of allowable arms
(iii) they both want to increase their world power
-Refer to Table 16-7. In reality these two countries may have a hard time keeping arms levels at the social optimal level due to which of the following reasons? (i) both countries have incentives to cheat on the agreement
(ii) they may have trouble agreeing on the level of allowable arms
(iii) they both want to increase their world power (Multiple Choice)
4.8/5 (93)
(93) Briefly contrast the difference between equilibrium market outcomes in a monopoly, oligopoly and perfect competition.
(Essay)
4.8/5 (78)
(78) Table 16-3
Imagine a small town in which only two residents, Robert and John, own wells that produce water for safe drinking. Each Saturday, Robert and John work together to decide how many litres of water to pump, bring the water to town, and sell it at whatever price the market will bear. To keep things simple, suppose that Robert and John can pump as much water as they want without cost; therefore, the marginal cost of water equals zero.
The weekly town demand schedule and total revenue schedule for water are shown in the table.
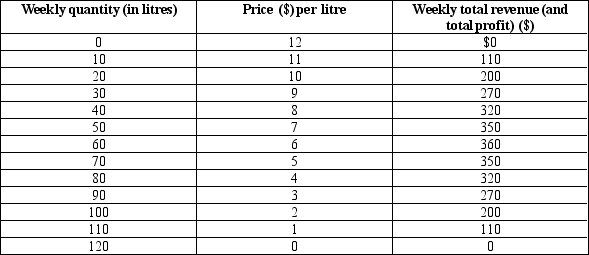 -Refer to Table 16-3. Suppose the town enacts new anti-trust laws that prohibit Robert and John from operating as a monopolist. What will the new price of water end up being once the Nash equilibrium is reached?
 (Multiple Choice)
4.8/5 (86)
(86) Table 16-3
Imagine a small town in which only two residents, Robert and John, own wells that produce water for safe drinking. Each Saturday, Robert and John work together to decide how many litres of water to pump, bring the water to town, and sell it at whatever price the market will bear. To keep things simple, suppose that Robert and John can pump as much water as they want without cost; therefore, the marginal cost of water equals zero.
The weekly town demand schedule and total revenue schedule for water are shown in the table.
-Refer to Table 16-3. Since Robert and John operate as a profit-maximising monopoly in the market for water, what price will they charge to sell 80 litres of water?
-Refer to Table 16-3. Since Robert and John operate as a profit-maximising monopoly in the market for water, what price will they charge to sell 80 litres of water? (Multiple Choice)
5.0/5 (89)
(89) As the number of firms in an oligopolistic market grows larger, the price approaches:
(Multiple Choice)
4.8/5 (74)
(74) In the case of oligopoly markets, self-interest prevents cooperation and leads to an inferior outcome for the parties involved.
(True/False)
4.8/5 (69)
(69) Table 16-4
Consider the following Duopoly game.
 -Refer to Table 16-4. When this game reaches a Nash equilibrium, profits for firm A and firm B will be:
 (Multiple Choice)
4.8/5 (94)
(94) Assume that the countries of Irun and Urun are the only two producers of crude oil. Further assume that both countries have entered into an agreement to maintain certain production levels in order to maximise profits. The world market for oil is represented by a downward-sloping demand curve.
-According to the information provided, if Irun fails to live up to the production agreement and overproduces, which of the following statements will be true of Urun's condition?
(Multiple Choice)
4.8/5 (65)
(65) An oligopoly is a market with a few sellers, each offering a similar or identical product.
(True/False)
4.8/5 (84)
(84) The tit-for-tat strategy in repeated prisoners' dilemma games:
(Multiple Choice)
4.8/5 (71)
(71) When firms are faced with making strategic choices in order to maximise profit, economists typically use:
(Multiple Choice)
4.9/5 (69)
(69) Table 16-7
Consider two countries, Eudora and the Inhabit, that are engaged in an arms race. The question each country must face is whether to build new weapons or to disarm existing weapons. Each country prefers to have more arms than the other because a large arsenal gives it more influence in world affairs. But each country also prefers to live in a world safe from the other country's weapons. The table shows the possible outcomes for each decision combination.
-Refer to Table 16-7. In which of the following situations is Eudora better off arming? (i) if Inhabit arms
(ii) if Inhabit disarms
(iii) if arming is their sub-dominant gaming strategy
-Refer to Table 16-7. In which of the following situations is Eudora better off arming? (i) if Inhabit arms
(ii) if Inhabit disarms
(iii) if arming is their sub-dominant gaming strategy (Multiple Choice)
4.9/5 (82)
(82) If the number of firms in an oligopoly grows smaller, an oligopolistic market looks less and less like:
(Multiple Choice)
4.8/5 (71)
(71) Suppose an opal-mining firm notices that the price of opals is above marginal cost. Selling one more unit of opals at the going price also increases profit. This concept is known as the:
(Multiple Choice)
4.8/5 (75)
(75) *Each firm reasons that the monopoly price ($24) earns them $48 000 each (2000 tickets each). If one of them increases output by 1000, the price drops to $18 (midpoint). At 5000 tickets, the firm that drops its price earns 3000 x $18 000 = $54 000. The other firm earns
$36 000. The NE is for both firms to increase output to 3000.
-Refer to Table 16-1. Assume that there are two profit-maximising ecotourist companies operating in this market. Further assume that they are not able to collude on the price and quantity of tickets they sell. What price will the tickets be sold at when this market reaches a Nash equilibrium?
(Multiple Choice)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)