



 Chat with AI
Exam 4: Economic Efficiency, Government Price Setting, and Taxes

Exam 1: Economics: Foundations and Models459 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes420 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care337 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance512 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs326 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets256 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income260 Questions
Exam 20: Unemployment and Inflation290 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles251 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies261 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run305 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money, Banks, and the Federal Reserve System278 Questions
Exam 26: Monetary Policy280 Questions
Exam 27: Fiscal Policy313 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy277 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Figure 4-3  Figure 4-3 shows Kendra's demand curve for ice cream cones.
-Refer to Figure 4-3. What is the total amount that Kendra is willing to pay for 1 ice cream cone?
Figure 4-3 shows Kendra's demand curve for ice cream cones.
-Refer to Figure 4-3. What is the total amount that Kendra is willing to pay for 1 ice cream cone? (Multiple Choice)
4.8/5  (76)
(76) Figure 4-5  -Refer to Figure 4-5. The figure above represents the market for pecans. Assume that this is a competitive market. If 4,000 pounds of pecans are sold
 (Multiple Choice)
4.8/5 (76)
(76) Table 4-4
 -Refer to Table 4-4. The table above lists the highest prices three consumers, Curly, Moe, and Larry, are willing to pay for a bottle of champagne. If the price of one of the bottles is $27 dollars, total consumer surplus will be
 (Multiple Choice)
4.7/5 (78)
(78) If buyers were required to pay the federal excise tax on gasoline directly to the government, the demand curve for gasoline would shift up.
(True/False)
4.9/5 (74)
(74) Figure 4-7  -Refer to Figure 4-7. The figure above represents the market for iced tea. Assume that this is a competitive market. If the price of iced tea is $3, what changes in the market would result in an economically efficient output?
 (Multiple Choice)
4.9/5 (76)
(76) You are given the following market data for Venus automobiles in Saturnia.
Demand is represented by: P = 200 - 0.25Q
Supply is represented by: P = 130 + 0.10Q
where P = Price and Q = Quantity.
a. Calculate the equilibrium price and quantity.
b. Calculate the consumer surplus in this market.
c. Calculate the producer surplus in this market.
(Essay)
4.9/5 (78)
(78) Marginal benefit is the total benefit to a consumer from consuming one more unit of a good or service.
(True/False)
4.8/5 (79)
(79) Table 4-14
 -Refer to Table 4-14. The equations above describe the demand and supply for Pauline's Pickled Pomegranates. What are the equilibrium price and quantity (in thousands) for Pauline's Pickled Pomegranates?
 (Multiple Choice)
4.7/5 (79)
(79) Table 4-1
 -Refer to Table 4-1. The table above lists the highest prices three consumers, Tom, Dick, and Harriet, are willing to pay for a short-sleeved polo shirt. If the price of one of the shirts is $28 dollars,
 (Multiple Choice)
4.7/5 (64)
(64) Economic efficiency is achieved when there is a market outcome in which the marginal benefit to consumers of the last unit produced is equal to its marginal cost of production and
(Multiple Choice)
4.9/5 (80)
(80) Table 4-3
 -Refer to Table 4-3. The table above lists the marginal cost of cowboy hats by The Waco Kid, a firm that specializes in producing western wear. If the price of cowboy hats increases from $38 to $46,
 (Multiple Choice)
4.8/5 (93)
(93) Figure 4-7
-Refer to Figure 4-7. The figure above represents the market for iced tea. Assume that this is a competitive market. If 10,000 units of iced tea are sold
-Refer to Figure 4-7. The figure above represents the market for iced tea. Assume that this is a competitive market. If 10,000 units of iced tea are sold (Multiple Choice)
4.8/5 (85)
(85) Figure 4-20 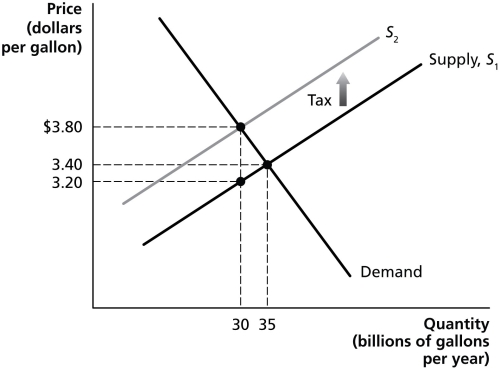 -Refer to Figure 4-20. The figure above represents demand and supply in the market for gasoline. Use the diagram to answer the following questions.
a. How much is the government tax on each gallon of gasoline?
b. What portion of the per-unit tax is paid by consumers?
c. What portion of the per-unit tax is paid by producers?
d. What is the quantity sold after the imposition of the tax?
e. What is the after-tax revenue per gallon received by producers?
f. What is the total tax revenue collected by the government?
g. What is the value of the excess burden of the tax?
-Refer to Figure 4-20. The figure above represents demand and supply in the market for gasoline. Use the diagram to answer the following questions.
a. How much is the government tax on each gallon of gasoline?
b. What portion of the per-unit tax is paid by consumers?
c. What portion of the per-unit tax is paid by producers?
d. What is the quantity sold after the imposition of the tax?
e. What is the after-tax revenue per gallon received by producers?
f. What is the total tax revenue collected by the government?
g. What is the value of the excess burden of the tax? (Essay)
4.7/5 (85)
(85) Figure 4-9  Figure 4-9 shows the demand and supply curves for the almond market. The government believes that the equilibrium price is too low and tries to help almond growers by setting a price floor at Pf.
-Refer to Figure 4-9. What area represents the portion of consumer surplus that has been transferred to producer surplus as a result of the price floor?
Figure 4-9 shows the demand and supply curves for the almond market. The government believes that the equilibrium price is too low and tries to help almond growers by setting a price floor at Pf.
-Refer to Figure 4-9. What area represents the portion of consumer surplus that has been transferred to producer surplus as a result of the price floor? (Multiple Choice)
4.9/5 (84)
(84) Table 4-7
 Table 4-7 shows the demand and supply schedules for the labor market in the city of Pixley.
-Refer to Table 4-7. Suppose that the quantity of labor demanded increases by 40,000 at each wage level. What are the new free market equilibrium hourly wage and the new equilibrium quantity of labor?
Table 4-7 shows the demand and supply schedules for the labor market in the city of Pixley.
-Refer to Table 4-7. Suppose that the quantity of labor demanded increases by 40,000 at each wage level. What are the new free market equilibrium hourly wage and the new equilibrium quantity of labor? (Multiple Choice)
5.0/5 (84)
(84) Figure 4-6  Figure 4-6 shows the market for granola. The market is initially in equilibrium at a price of P1 and a quantity of Q1. Now suppose producers decide to cut output to Q2 in order to raise the price to P2.
-Refer to Figure 4-6. At the price P2, consumers are willing to buy the Q2 pounds of granola. Is this an economically efficient quantity?
Figure 4-6 shows the market for granola. The market is initially in equilibrium at a price of P1 and a quantity of Q1. Now suppose producers decide to cut output to Q2 in order to raise the price to P2.
-Refer to Figure 4-6. At the price P2, consumers are willing to buy the Q2 pounds of granola. Is this an economically efficient quantity? (Multiple Choice)
4.9/5 (84)
(84) Figure 4-18  Figure 4-18 shows the market for cigarettes. The government plans to impose a per-unit tax in this market.
-Refer to Figure 4-18. As a result of the tax, is there a loss in producer surplus?
Figure 4-18 shows the market for cigarettes. The government plans to impose a per-unit tax in this market.
-Refer to Figure 4-18. As a result of the tax, is there a loss in producer surplus? (Multiple Choice)
4.9/5 (79)
(79) What is marginal benefit? Which curve is also referred to as a marginal benefit curve?
(Essay)
4.9/5 (84)
(84) The actual division of the burden of a tax between buyers and sellers in a market is called
(Multiple Choice)
4.7/5 (70)
(70) Equilibrium in a competitive market results in the greatest amount of economic surplus from the production of a good or service.
(True/False)
4.8/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)