



 Chat with AI
Exam 11: Technology, Production, and Costs

Exam 1: Economics: Foundations and Models459 Questions
Exam 2: Trade-Offs, Comparative Advantage, and the Market System492 Questions
Exam 3: Where Prices Come From: the Interaction of Demand and Supply476 Questions
Exam 4: Economic Efficiency, Government Price Setting, and Taxes420 Questions
Exam 5: Externalities, Environmental Policy, and Public Goods262 Questions
Exam 6: Elasticity: the Responsiveness of Demand and Supply293 Questions
Exam 7: The Economics of Health Care337 Questions
Exam 8: Firms, the Stock Market, and Corporate Governance512 Questions
Exam 9: Comparative Advantage and the Gains From International Trade377 Questions
Exam 10: Consumer Choice and Behavioral Economics304 Questions
Exam 11: Technology, Production, and Costs326 Questions
Exam 12: Firms in Perfectly Competitive Markets296 Questions
Exam 13: Monopolistic Competition: the Competitive Model in a More Realistic Setting272 Questions
Exam 14: Oligopoly: Firms in Less Competitive Markets256 Questions
Exam 15: Monopoly and Antitrust Policy279 Questions
Exam 16: Pricing Strategy258 Questions
Exam 17: The Markets for Labor and Other Factors of Production279 Questions
Exam 18: Public Choice, Taxes, and the Distribution of Income258 Questions
Exam 19: Gdp: Measuring Total Production and Income260 Questions
Exam 20: Unemployment and Inflation290 Questions
Exam 21: Economic Growth, the Financial System, and Business Cycles251 Questions
Exam 22: Long-Run Economic Growth: Sources and Policies261 Questions
Exam 23: Aggregate Expenditure and Output in the Short Run305 Questions
Exam 24: Aggregate Demand and Aggregate Supply Analysis286 Questions
Exam 25: Money, Banks, and the Federal Reserve System278 Questions
Exam 26: Monetary Policy280 Questions
Exam 27: Fiscal Policy313 Questions
Exam 28: Inflation, Unemployment, and Federal Reserve Policy257 Questions
Exam 29: Macroeconomics in an Open Economy277 Questions
Exam 30: The International Financial System258 Questions
Select questions type


Which of the following statements correctly describes the distinction between technology and technological change?
(Multiple Choice)
4.9/5  (87)
(87) Average fixed cost can be calculated using any of the formulas below except
(Multiple Choice)
4.9/5 (95)
(95) In a diagram showing the average total cost and average variable cost curves, the minimum point of the average total cost is
(Multiple Choice)
4.9/5 (74)
(74) Which of the following explains why the marginal cost curve has a U shape?
(Multiple Choice)
4.7/5 (86)
(86) Consider a firm that uses two inputs, labor and capital, to produce its output. Assume labor is measured on the horizontal axis and capital on the vertical axis. Which of the following best explains why the marginal rate of technical substitution decreases in absolute value as we move down an isoquant?
(Multiple Choice)
4.9/5 (82)
(82) Fill in the missing values in the following table. Draw one graph showing how total output increases with the quantity of workers hired, and another graph showing the marginal product of labor and the average product of labor.
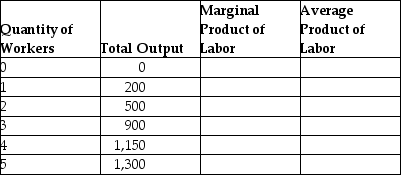
(Essay)
4.8/5 (83)
(83) As the level of output increases, what happens to the value of average fixed cost, and what happens to the difference between the value of average total cost and average variable cost?
(Essay)
4.9/5 (70)
(70) Figure 11-13  -Refer to Figure 11-13. The lines shown in the diagram are isocost lines. Which of the following shows an increase in the firm's total cost while the price of labor and capital remain unchanged?
 (Multiple Choice)
4.8/5 (88)
(88) A characteristic of the long run that is not available in the short run is that a firm is free to vary its output.
(True/False)
4.8/5 (71)
(71) What is the difference between "diminishing marginal returns" and "diseconomies of scale"?
(Multiple Choice)
4.8/5 (87)
(87) If 11 workers can produce 53 units of output while 12 workers can produce 56 units of output, what is the marginal product of the 12th worker?
(Multiple Choice)
4.8/5 (89)
(89) The process a firm uses to turn inputs into outputs of goods and services is called technology.
(True/False)
5.0/5 (89)
(89) Figure 11-13
-Refer to Figure 11-13. The lines shown in the diagram are isocost lines. If the price of labor is $50 per unit, what is the price of capital along the isocost CE?
-Refer to Figure 11-13. The lines shown in the diagram are isocost lines. If the price of labor is $50 per unit, what is the price of capital along the isocost CE? (Multiple Choice)
5.0/5 (73)
(73) Is it possible for technological change to be negative? If so, give an example.
(Essay)
4.8/5 (77)
(77) If a producer is not able to expand its plant capacity immediately, it is
(Multiple Choice)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)